Chips Bounce After the Rout. Payrolls Are the Next Test.
Snapshot, not opening prices
Prepared from the 7:25 AM ET brief. Futures are stamped about 6:37 AM ET; Robinhood extended-hours quotes are around 7:20 AM ET. The October jobs report is scheduled for 8:30 AM ET.
A bounce in the wreckage
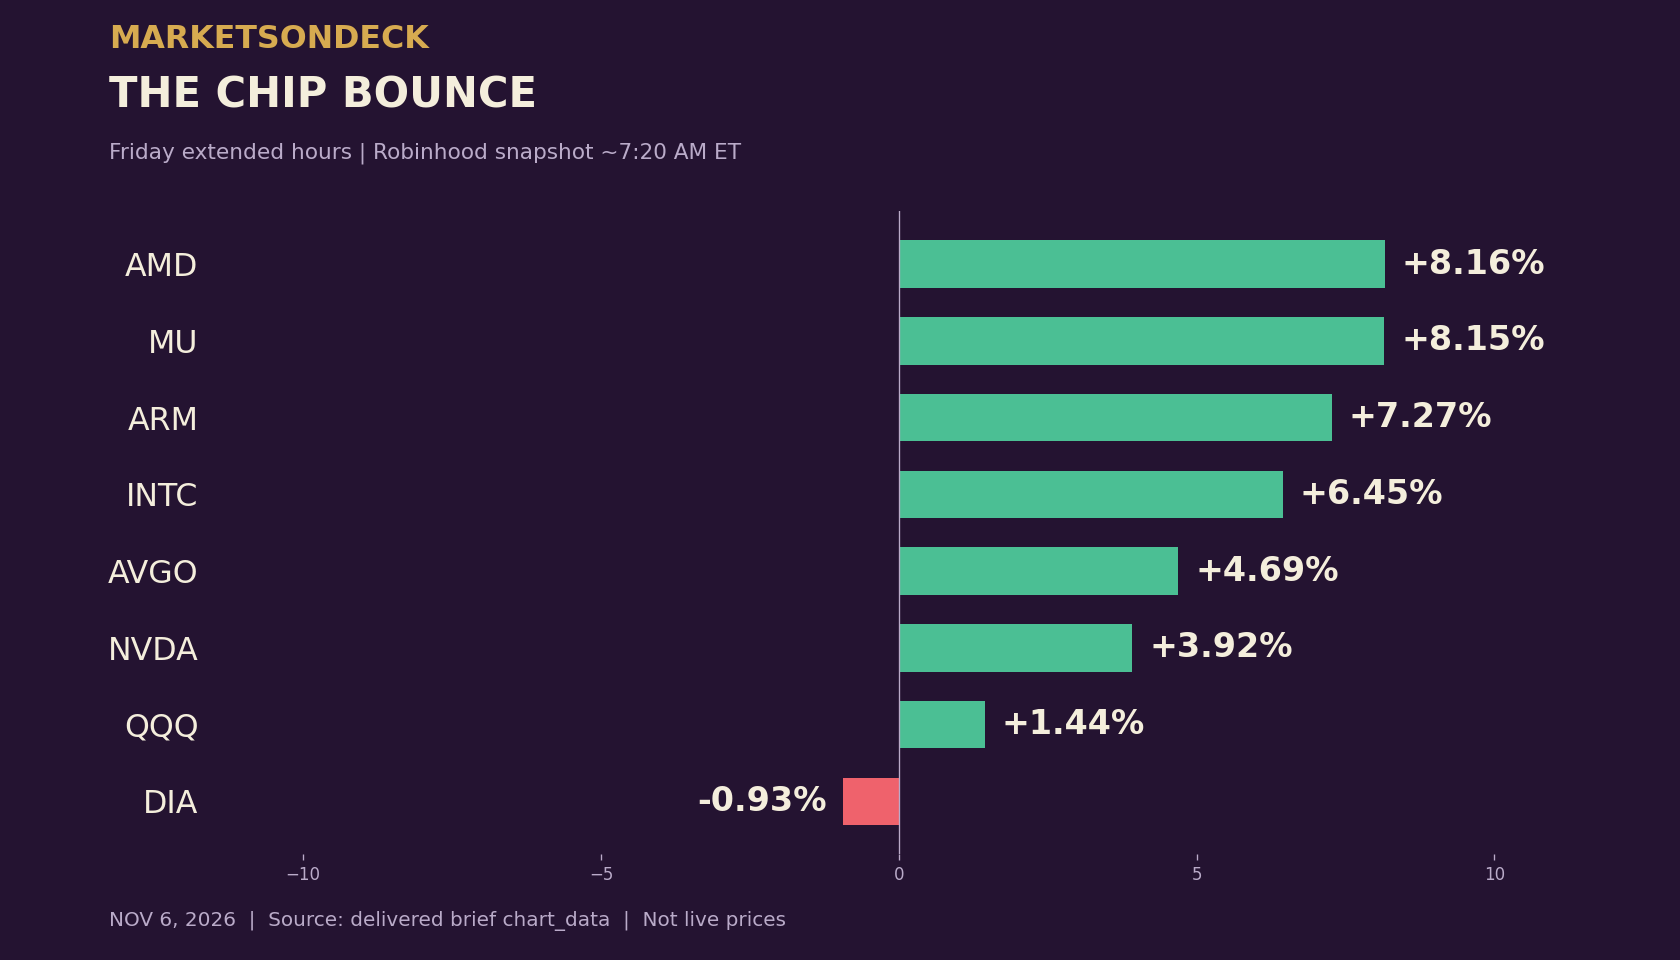
AMD is up 8.16% and Micron 8.15% in the delivered Robinhood extended-hours snapshot after Thursday's semiconductor selloff. Nasdaq-100 futures are up 1.43%, S&P 500 futures 0.29%, while Dow futures are down 0.90%. These are different instruments and timestamps, not a promise about the opening bell.
Thursday's damage
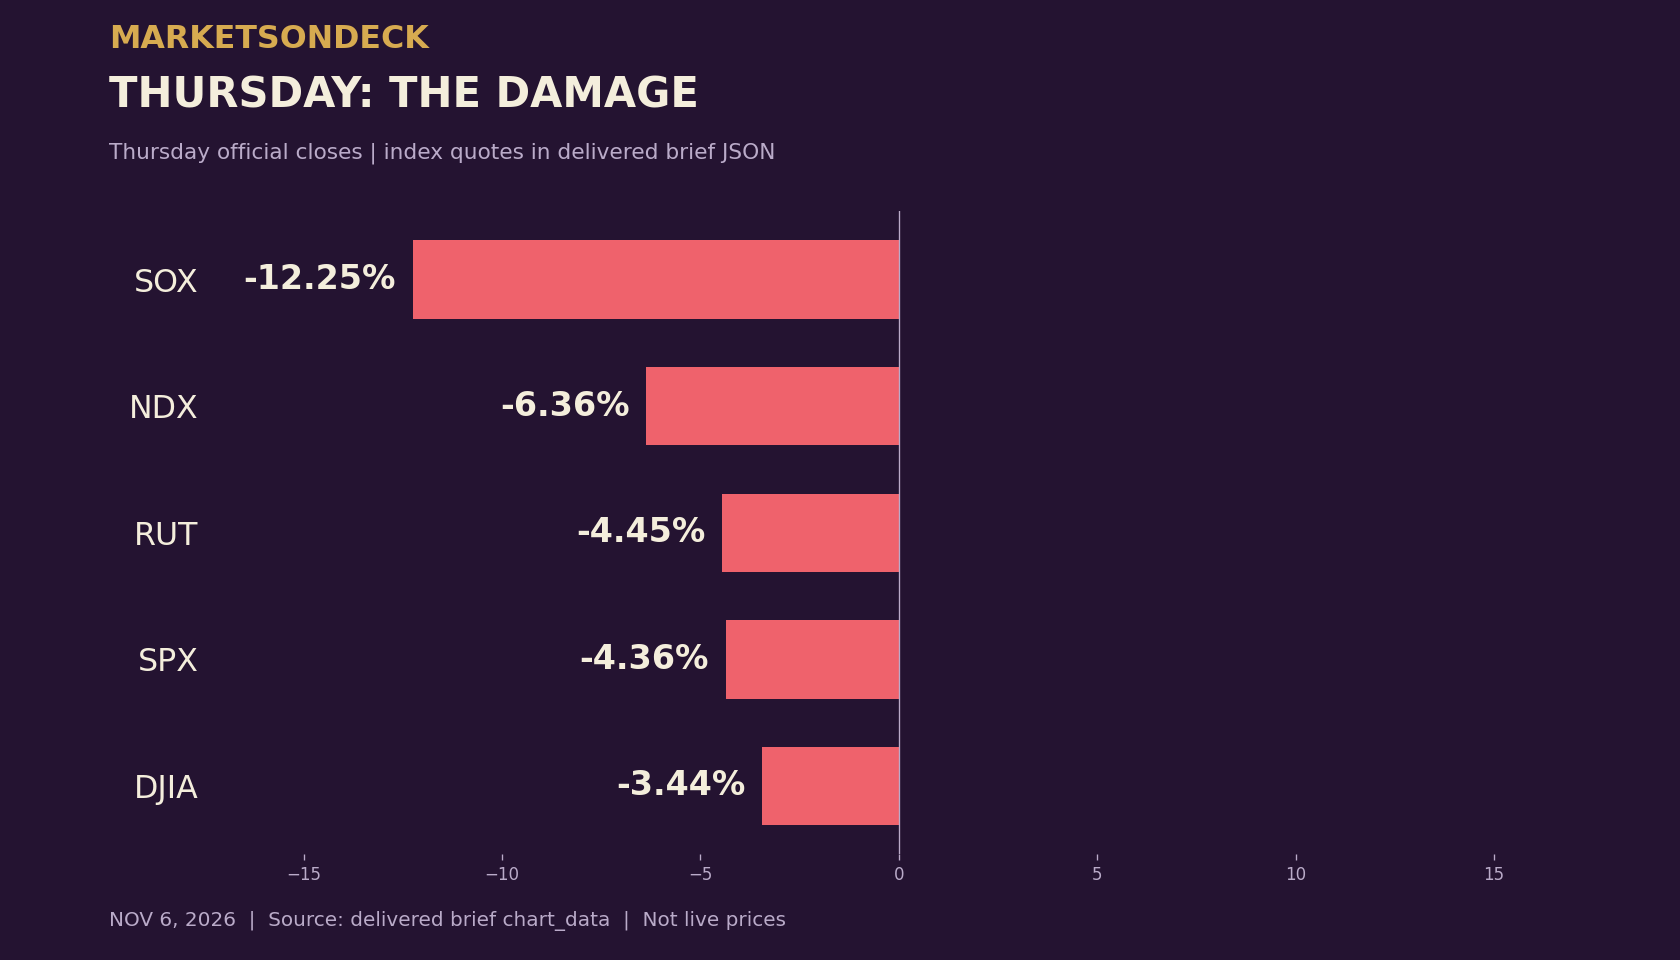
The S&P 500 fell 4.36% to 7,353.73, its worst day since April 2025. The Dow lost 1,833.06 points, or 3.44%, to 51,523.06. The Nasdaq-100 fell 6.36% to 26,629.81, while the Nasdaq Composite fell about 5.5% into correction territory. The Philadelphia Semiconductor Index dropped 12.25% and the VIX rose 69.66% to 28.18. Reuters reported investor concerns about AI regulation and a slower data-center buildout after the midterm elections.
Chips lead, the rest is mixed
Nvidia is up 3.92% to $188.70 in the Robinhood extended-hours snapshot, following Thursday's 9.26% decline. AMD is at $435.37 and Micron $712.00. Broadcom is up 4.69%, Intel 6.45% and Arm 7.27%. QQQ is up 1.44%, SPY 0.26% and DIA down 0.93%. All are premarket indications.
Earnings prices tell different stories
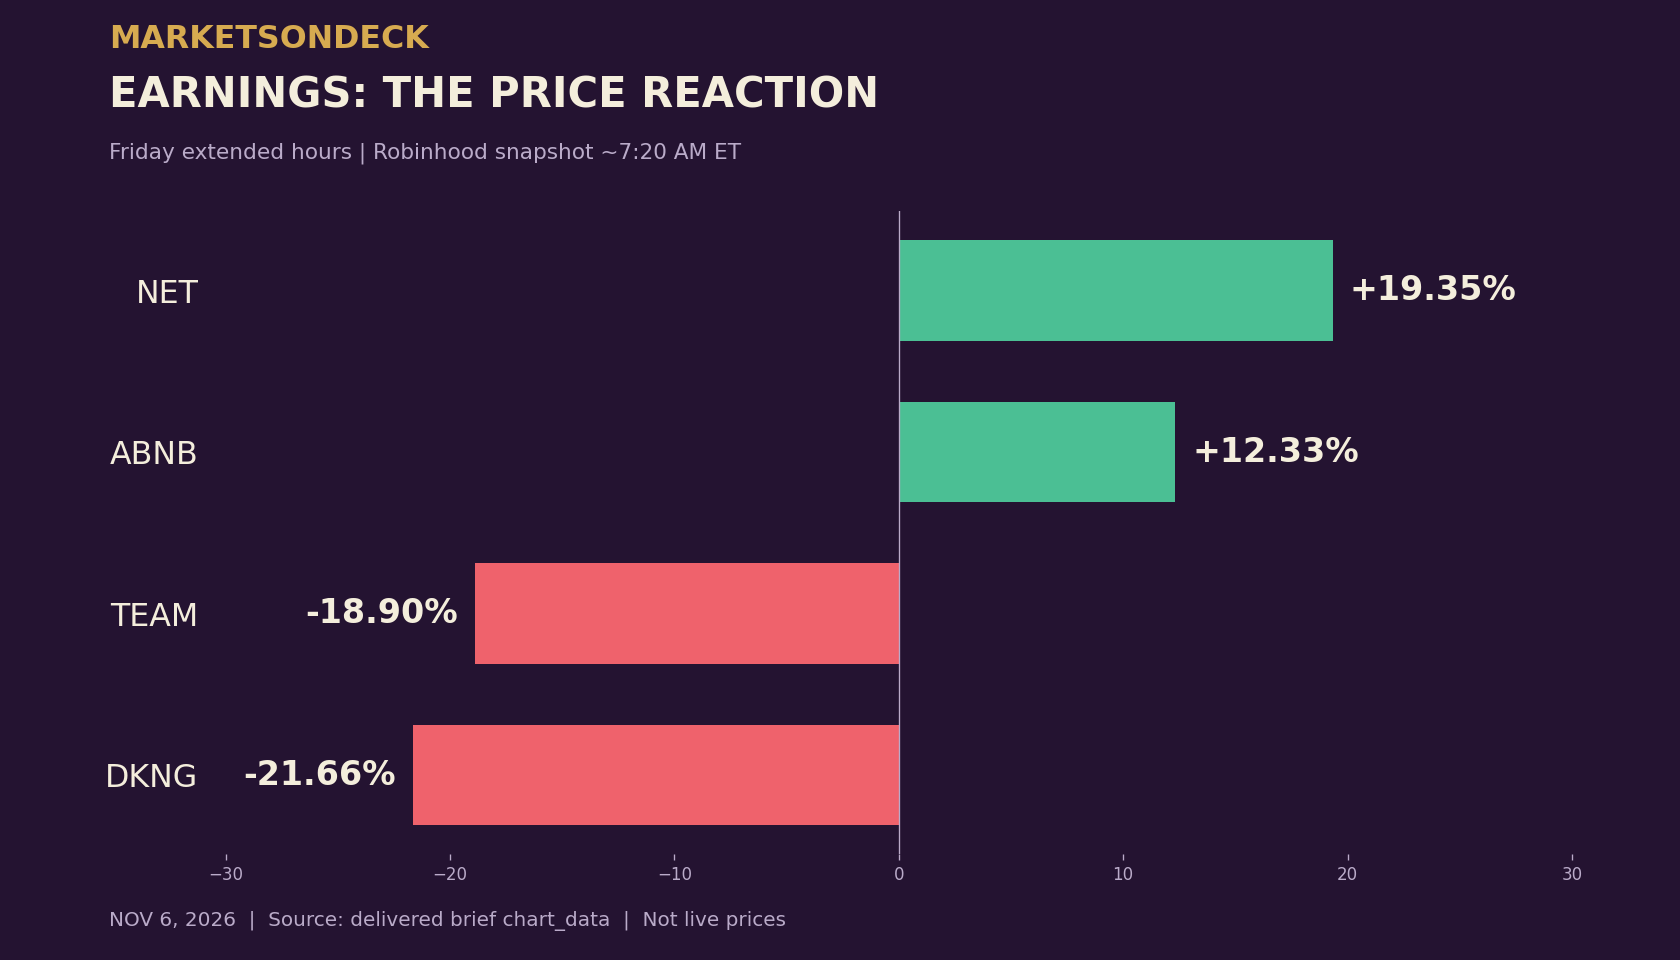
The delivered Friday extended-hours snapshot has Cloudflare up 19.35% and Airbnb up 12.33%, while Atlassian is down 18.90% and DraftKings down 21.66%. These are price reactions, not a comparison of earnings against a single consensus source.
Updated 9:25 AM ET: The 8:30 AM jobs report is out. BLS reports October payrolls rose 165,000, unemployment was 4.1%, and average hourly earnings rose 0.4% month over month and 3.1% year over year. The pre-release Reuters poll below was 65,000 / 4.2% / 0.3% / 2.9%. Earlier market quotes remain premarket snapshots, not live prices. BLS release.
What to watch
The October jobs report is due at 8:30 AM ET. The Reuters poll expects 65,000 payroll additions after September's 29,000, unemployment of 4.2%, and wages up 0.3% month over month and 2.9% year over year. Reuters reports traders pricing more than a 65% chance of a December Fed hike. The question for the open is whether the chip bounce survives the labor-market news. October CPI follows Tuesday, November 10.
Sources: Reuters: premarket setup | Reuters: jobs preview | AP: Thursday closes | BLS: release calendar
MarketsOnDeck - November 6, 2026, premarket. Not investment advice.
Qualcomm Beat Earnings and Dropped 10% — the Chip Hangover Is Dragging Nasdaq Futures After the Dow's 1,569-Point Day
Thursday, November 5, 2026. Prepared premarket. Futures below are stamped ~5:04 AM ET; stock indications are extended-hours marks around 7:16 AM ET, not opening prices.
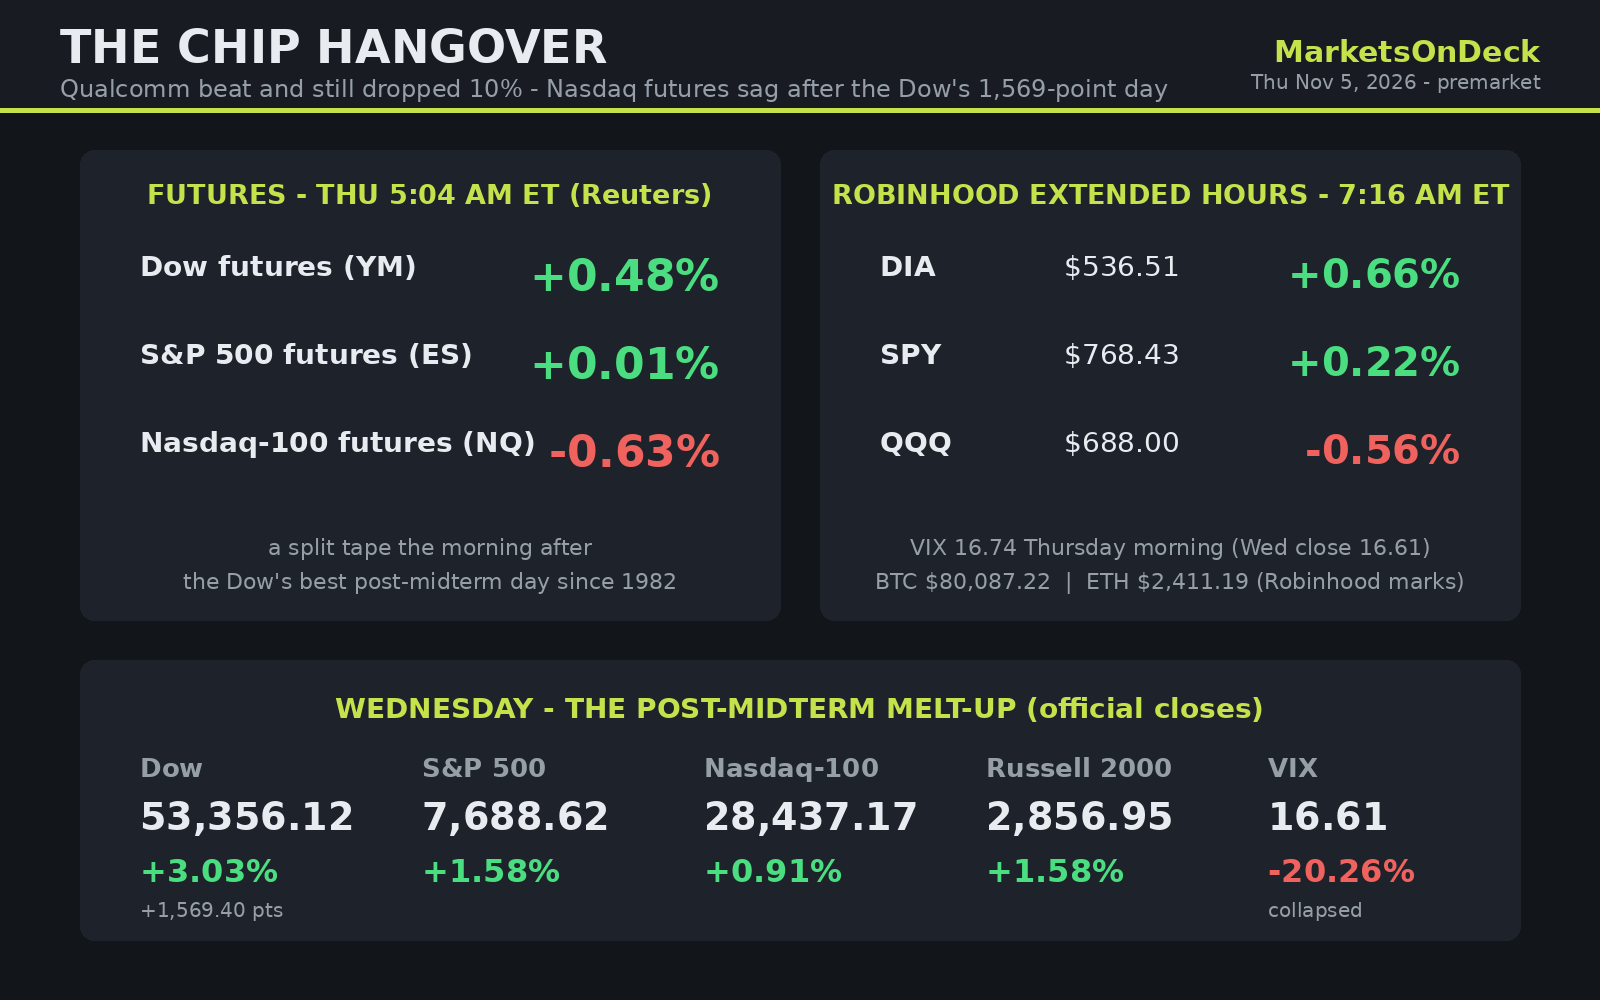
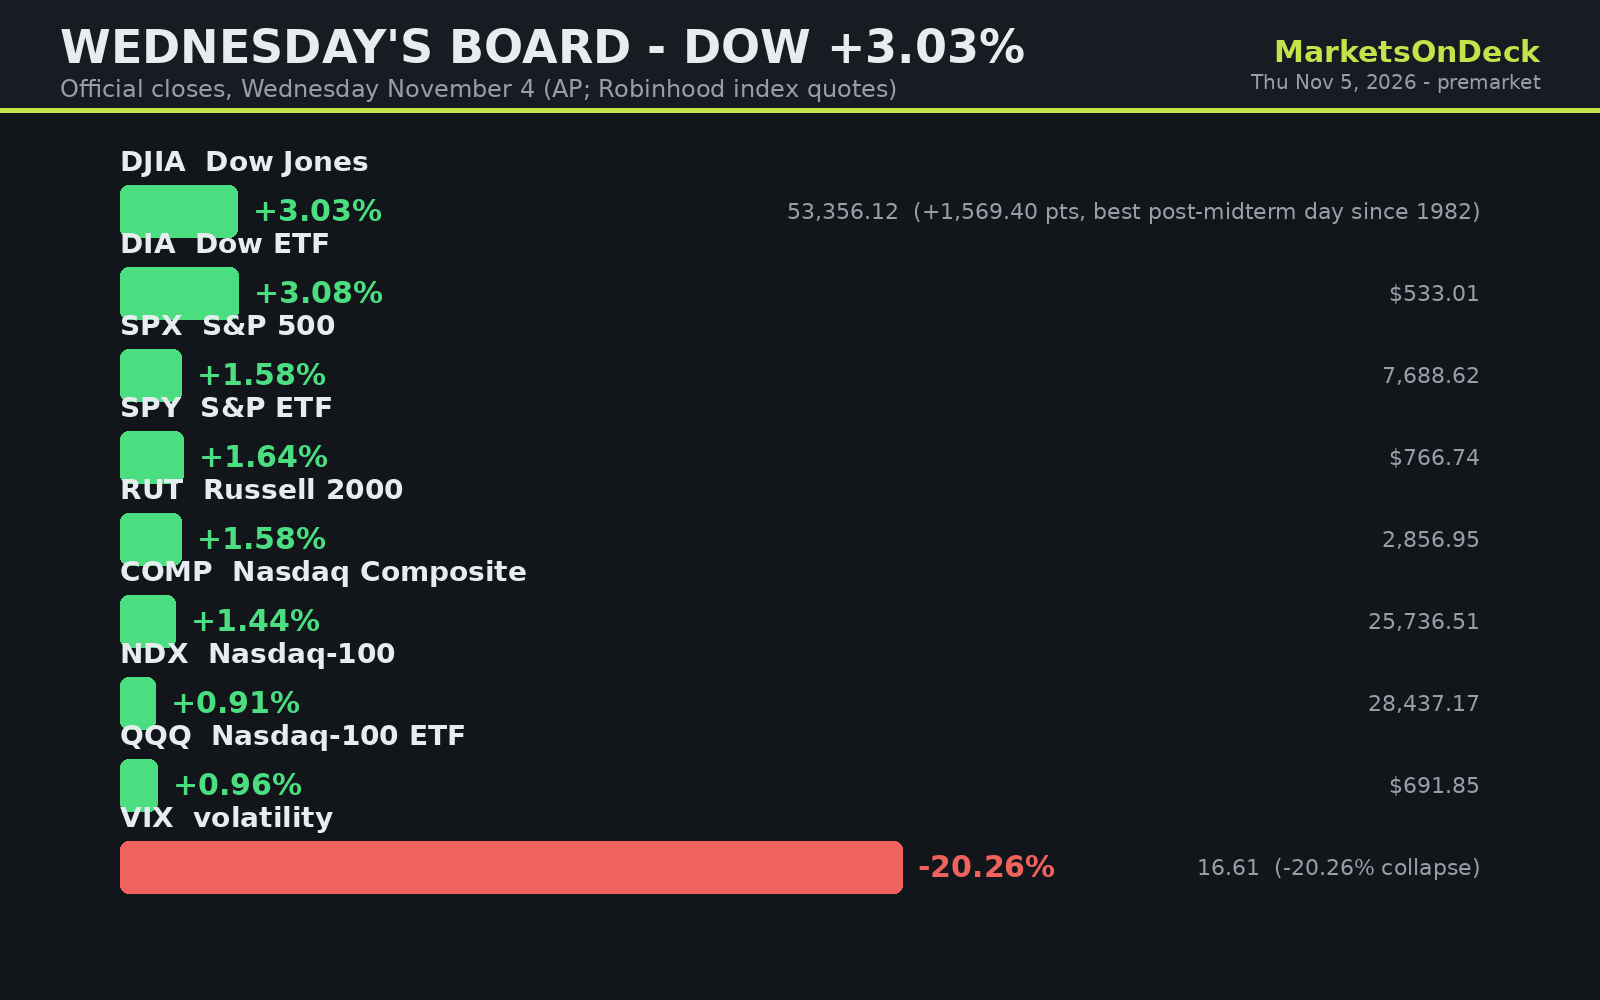
S&P 500 +1.58% · Nasdaq-100 +0.91% · Dow +3.03% — Wednesday's closes, percent only (Robinhood index quotes; Dow Jones Industrial Average per AP).
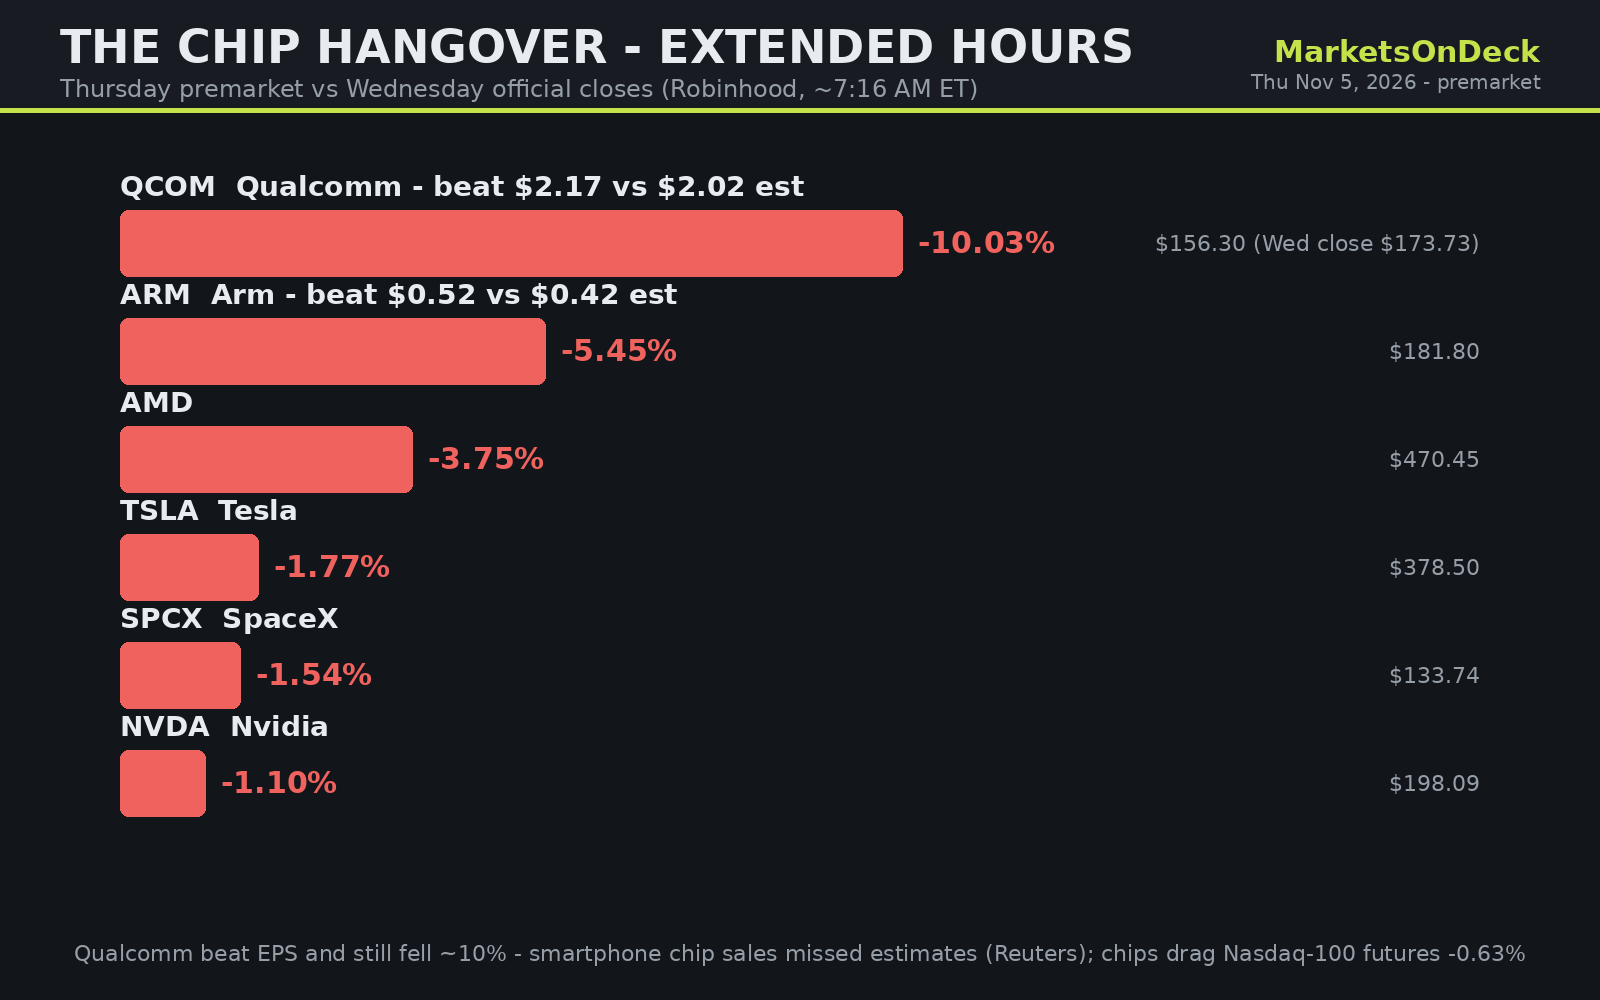
Qualcomm beat on earnings — $2.17 vs $2.02 estimated (Robinhood earnings calendar) — and is still down 10.03% in Robinhood extended hours, because its smartphone chip sales missed Wall Street estimates (Reuters): Nasdaq-100 futures are down 0.63% while Dow futures are up 0.48% (Reuters, 5:04 AM ET), the morning after the Dow's best post-midterm day since 1982.
The setup. Wednesday was the post-midterm melt-up: the Dow Jones Industrial Average ripped 1,569.40 points, +3.03% to 53,356.12 — its best post-midterm day since 1982 (AP via CNN; CFRA via CNN) — the S&P 500 rose 1.58% to 7,688.62, the Nasdaq-100 rose 0.91% to 28,437.17 and the Russell 2000 rose 1.58%, while the VIX collapsed 20.26% to 16.61 (Robinhood). Thursday's futures are the hangover, and it is a split tape: at 5:04 AM ET Dow E-minis were up 0.48%, S&P 500 E-minis were up 0.01% and Nasdaq-100 E-minis were down 0.63% (Reuters). Robinhood extended-hours marks at 7:16 AM ET agree: DIA +0.66%, SPY +0.22%, QQQ -0.56%, the VIX at 16.74, and Bitcoin's mark at $80,087.22 (Robinhood).
The chips are the drag. Qualcomm reported after Wednesday's close: EPS of $2.17 vs the $2.02 estimate (Robinhood earnings calendar) — a beat — but the stock dropped 10.1% in premarket trading after the chipmaker fell short of Wall Street estimates for fourth-quarter smartphone chip sales on sluggish demand and declining Apple-related revenue (Reuters); Robinhood extended hours show Qualcomm at $156.30, -10.03% vs Wednesday's $173.73 close. Arm beat too ($0.52 vs $0.42, Robinhood) and is still -5.45% extended. AMD, which closed Wednesday +1.00% at $488.76, is -3.75% extended, and Nvidia — Wednesday's Mag 7 laggard at $200.29, -3.10% — is -1.10% extended to $198.09 (Robinhood). The rest of the Mag 7 is holding Wednesday's gains: Alphabet +1.58% extended, Amazon +1.53%, Meta +1.33%, Apple +0.93% and Microsoft +0.43%, while Tesla is -1.77% and SpaceX -1.54%, extending losses (Robinhood; Reuters).
Earnings are landing both ways. Wednesday night's other reports (Robinhood earnings calendar): AppLovin beat ($4.30 vs $4.01), Motorola Solutions beat ($4.69 vs $4.34), Coherent beat ($2.09 vs $1.93) and HubSpot beat big ($3.81 vs $2.80), while MercadoLibre missed ($8.83 vs $9.30). Thursday morning's reported beats: ConocoPhillips ($3.27 vs $3.03), Cigna ($7.98 vs $7.50), Tapestry ($1.82 vs $1.56), Zoetis ($1.75 vs $1.51), Kimberly-Clark ($1.70 vs $1.65) and Becton Dickinson ($4.15 vs $4.07) (Robinhood).
What to watch today:
- This morning — weekly initial jobless claims fell to 189,000, the fewest since mid-July (AP; about 197,000 expected, 194,000 the prior week); the Bank of England hiked to 4% from 3.75%, its first increase in over three years, on an 8-1 vote (BBC).
- The open — whether the chip hangover (Qualcomm -10.03% extended, Arm -5.45%, AMD -3.75%) spreads past the Nasdaq, and whether the Dow's futures lead (+0.48%, Reuters) survives the claims print.
- After the close — Airbnb ($2.85 estimated EPS), Affirm ($0.76), Atlassian ($1.19), Cloudflare ($0.28), BILL ($0.91), DraftKings (-$0.26) and Monster Beverage ($0.30) (Robinhood earnings calendar).
- Friday, November 6 at 8:30 AM ET — the October jobs report closes the week.
The OnDeck Book
Trading fell 12.64% on Wednesday and Agentic rose 0.23% on Wednesday (percent only, Robinhood Wednesday-close pulls in 2026-11-04-tape.json) vs SPY +1.64%, QQQ +0.96% and DIA +3.08%. Thursday premarket, extended-hours equity is -2.01% for Trading and -0.04% for Agentic vs Wednesday's core close (percent only). Positions (Wednesday official closes, Robinhood; re-verified line-by-line against this run's portfolio pull): SPCX 300 shares, avg $133.96, close $135.83 (-3.88% on Wednesday), +1.40% vs avg cost, unrealized +$560.73. NVDL 450 shares, avg $28.26, close $27.62 (-6.15%), -2.26% vs avg, unrealized -$286.97. SOFI 200 shares, avg $17.10, close $17.39 (+3.70%), +1.71% vs avg, unrealized +$58.50. QUBT 700 shares, avg $8.21, close $6.435 (+0.08%), -21.62% vs avg, unrealized -$1,242.50. Options (Wednesday close marks, Robinhood; marks sum $4,964 vs this run's portfolio option_market_value of $4,976 — the $12 difference is mark timing on the aggregate; quantities and clearing costs re-verified line-by-line): NVDA $215 calls expiring Mon Nov 16, 21 long, clearing cost $5,820, mark $1.29, market value $2,709 — 11 days to expiry; SPCX $140 calls expiring Fri Nov 13, 4 long, clearing cost $1,650, mark $3.33, market value $1,332 — 8 days; NVDA $210 calls expiring Fri Nov 13, 2 long, clearing cost $630, mark $1.96, market value $392 — 8 days; SPCX $138 calls expiring Fri Nov 6, 2 long, clearing cost $558, mark $1.83, market value $366 — 1 day; NVDA $205 calls expiring Fri Nov 6, 1 long, clearing cost $360, mark $1.46, market value $146 — 1 day; SPCX $148 calls expiring Fri Nov 6, 1 long, clearing cost $356, mark $0.19, market value $19 — 1 day. Futures: none — the position was fully closed on Oct 22 (web-verified on robinhood.com), and the API aggregate futures market value reads $0 this morning. Crypto: ETH 3.6 coins, clearing cost basis $8,608.00, mark $2,411.19 (Robinhood, ~7:16 AM ET), indicative value $8,680.28; USDG 1.0 unit on the API spot line (the API shows only the un-lent unit; Crypto Earn totals were last web-verified 2026-10-15 at 102.88 units total); dust: CC 1.0, DOGE 1.0, USDC 0.00993.
MarketsOnDeck — market data as cited, Thursday November 5, 2026, pre-market. Not investment advice.
Democrats Swept Both Chambers — Futures Reversed Higher, but Tesla and SpaceX Are Down 5% and AMD's Spike Is Fading
Wednesday, November 4, 2026. Prepared premarket. Futures below are stamped ~5:20 AM ET; stock indications are extended-hours marks around 7:16 AM ET, not opening prices.
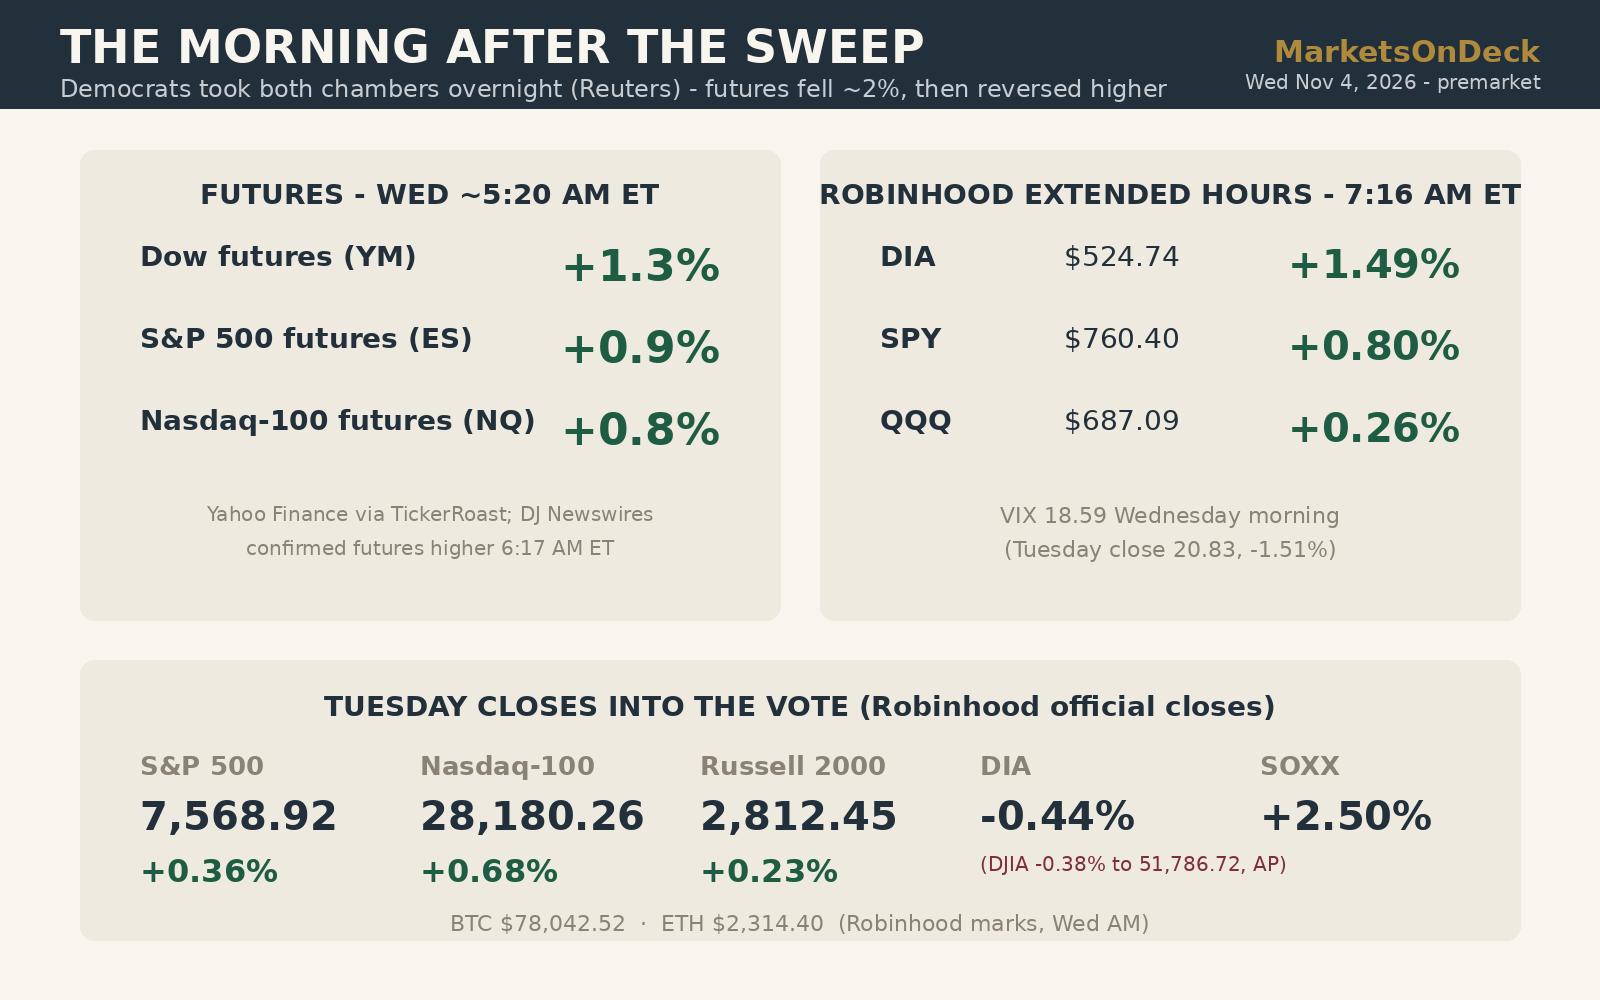
S&P 500 +0.36% · Nasdaq-100 +0.68% · DIA -0.44% — Tuesday's closes, percent only (Robinhood index quotes; DIA).
Democrats seized both the House and the Senate in Tuesday's midterms (Reuters) — index futures that fell as much as 2% overnight have reversed higher, with DIA up 1.49% in Robinhood extended hours, but Tesla is down 5.64% and SpaceX down 5.36% premarket, and AMD's 7.13% post-earnings spike has faded to 0.44% in Robinhood's premarket book.
The setup. Tuesday was a chip-led bounce into the vote: the S&P 500 rose 0.36% to 7,568.92, the Nasdaq-100 rose 0.68% to 28,180.26 and the Russell 2000 rose 0.23% to 2,812.45, while the Dow slipped — DIA -0.44% (Robinhood closes; the Dow Jones Industrial Average fell 0.38% to 51,786.72, AP). SPY closed +0.31% and QQQ +0.62%, the semiconductor ETF (SOXX) rose 2.50% and the VIX eased 1.51% to 20.83 (Robinhood). Then the midterms landed: Democrats seized control of both the Senate and the House, scoring sweeping victories in Republican strongholds (Reuters, Nov 4). Futures whipsawed — Nasdaq-100 futures fell nearly 2% on early returns (Stocktwits/TradingView) — then reversed: by about 5:20 AM ET S&P 500 futures were up about 0.9%, Nasdaq-100 futures about 0.8% and Dow futures about 1.3% (Yahoo Finance via TickerRoast), and Dow Jones Newswires reported futures higher again at 6:17 AM ET as investors weighed the blue win (Morningstar). Robinhood extended-hours marks at 7:16 AM ET agree — DIA +1.49% to $524.74, SPY +0.80% to $760.40, QQQ +0.26% to $687.09, and the VIX down at 18.59 Wednesday morning (Robinhood index quote). Crypto firmed: Bitcoin's Robinhood mark was $78,042.52 and Ether's $2,314.40 on Wednesday morning (Robinhood crypto quotes).
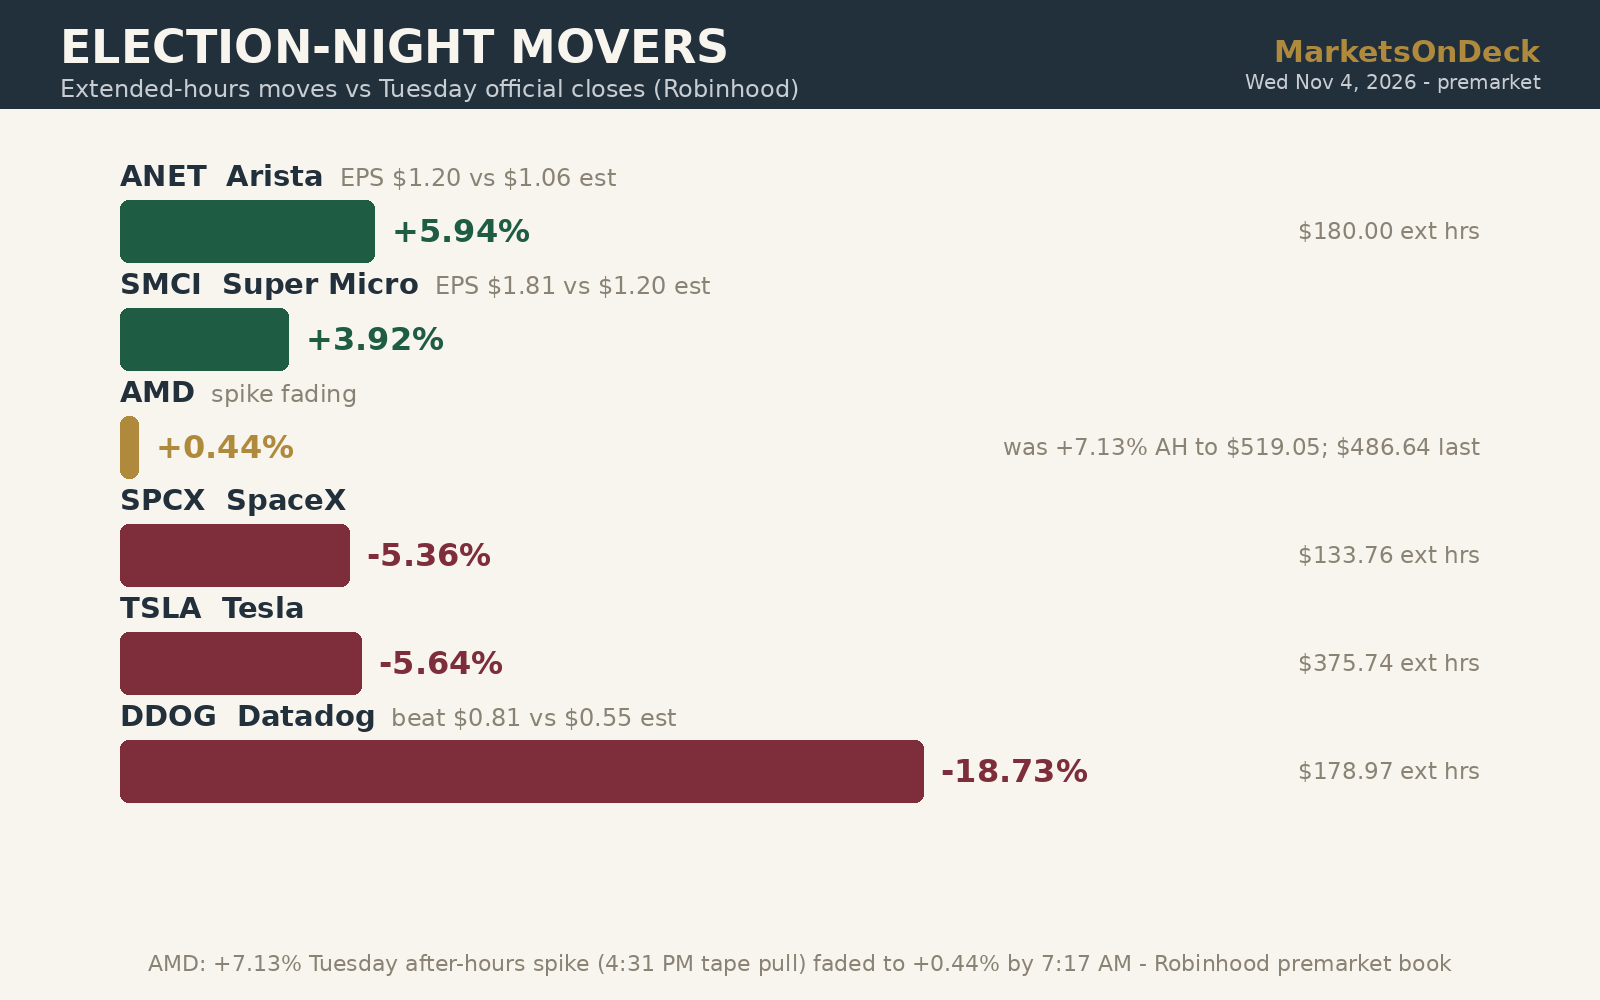
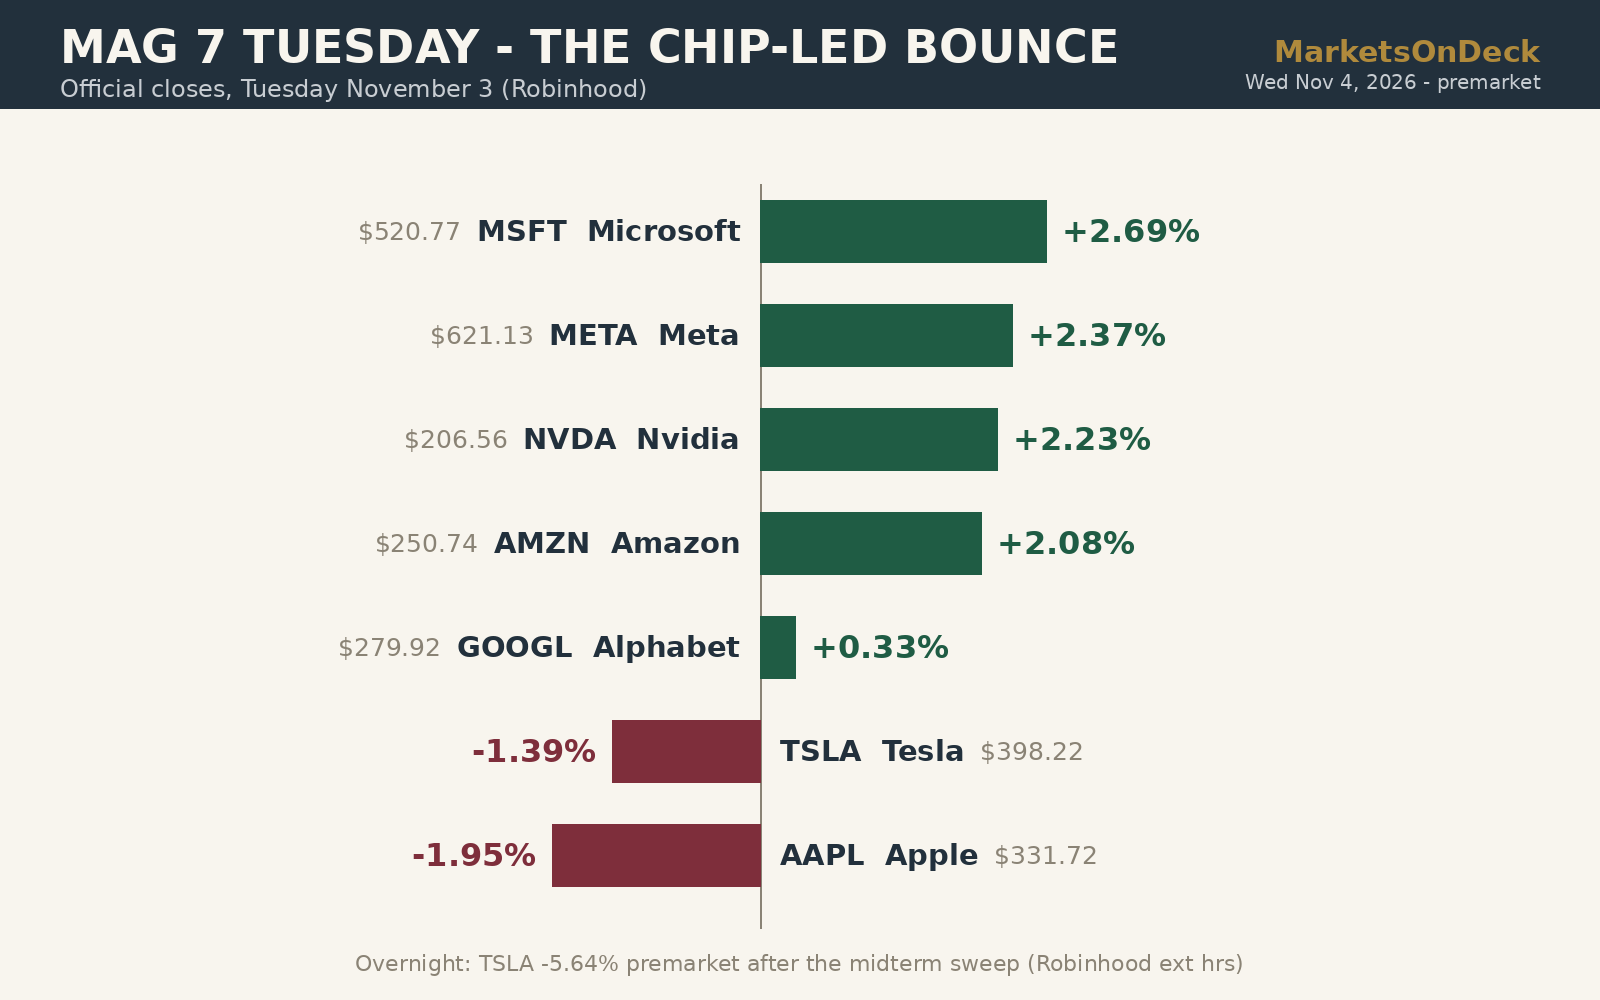
The Musk names are this morning's story. Tuesday's Mag 7 mostly bounced (Robinhood official closes): Microsoft rose 2.69% to $520.77, Meta rose 2.37% to $621.13, Nvidia rose 2.23% to $206.56, Amazon rose 2.08% to $250.74 and Alphabet rose 0.33% to $279.92, while Tesla fell 1.39% to $398.22 and Apple fell 1.95% to $331.72. Overnight, Tesla is down 5.64% in Robinhood extended hours to $375.74 and SpaceX (SPCX) is down 5.36% to $133.76 after Democrats swept the midterms — Dow Jones Newswires had SpaceX -3.6% and Tesla -3.5% at 5:33 AM ET and noted Democratic control could slow a potential SpaceX-Tesla merger (XTB via Morningstar). AMD reported third-quarter non-GAAP EPS of $2.09 vs the $1.95 LSEG consensus, revenue of $13.38 billion (+44.6% year over year) with data-center revenue up 97% to $8.55 billion, and guided fourth-quarter revenue to about $17 billion (AMD release via GlobeNewswire and Reuters). The stock spiked 7.13% in Tuesday after-hours to $519.05 (Robinhood, 4:31 PM ET tape pull) and Reuters put it up 7.3% in early premarket — but Robinhood's live premarket book at 7:17 AM ET showed a last extended-hours trade of $486.64, just +0.44% vs Tuesday's $484.50 close (bid $486.38 / ask $486.69): the spike was fading into the open. Arista Networks beat ($1.20 vs $1.06 estimated, Robinhood earnings calendar) and is +5.94% in extended hours to $180.00 (Robinhood); Super Micro beat bigger ($1.81 vs $1.20) and is +3.92% extended (Robinhood).
Wednesday's data and the calendar. ADP employment at 8:15 AM ET (expected 67K vs 90K prior), the September trade balance at 8:30 AM ET and the October ISM Services PMI at 10:00 AM ET (expected 54.8 vs 54.9 prior) (InvestingLive, Nov 4). This morning's reported earnings (Robinhood earnings calendar): McDonald's beat ($3.57 vs $3.38), CVS Health beat big ($2.09 vs $1.64), Datadog beat ($0.81 vs $0.55) yet is down 18.73% in Robinhood extended hours, Novo Nordisk beat ($0.89 vs $0.81) and Uber missed narrowly ($0.88 vs $0.91). Tuesday night's other beats: Amgen ($6.45 vs $5.77), Booking Holdings ($4.66 vs $4.49) and Block ($1.13 vs $0.96) (Robinhood). After today's close: Qualcomm ($2.02 estimated), Arm ($0.42), AppLovin ($4.01), MercadoLibre ($9.30), Coherent ($1.93) and Motorola Solutions ($4.34) (Robinhood). The week's last big print is the October jobs report on Friday, November 6 at 8:30 AM ET.
What to watch today:
- The futures reversal after Democrats swept both chambers (Reuters) — does it hold through the ISM Services print at 10:00 AM ET (expected 54.8, InvestingLive)?
- Tesla -5.64% and SpaceX -5.36% premarket (Robinhood) — do the Musk names stabilize after the drop?
- AMD's faded spike (+0.44% at 7:17 AM ET, Robinhood) — does it rebuild at the open?
- After the close — Qualcomm and Arm report (Robinhood earnings calendar).
The OnDeck Book
Trading rose 23.99% on Tuesday and Agentic rose 17.29% on Tuesday (percent only, Robinhood Tuesday-close pulls in 2026-11-03-tape.json) vs SPY +0.31%, QQQ +0.62% and DIA -0.44%. Wednesday premarket, extended-hours equity is -4.23% for Trading and +0.50% for Agentic vs Tuesday's core close (percent only) — Trading's premarket drop is led by its SpaceX position: SPCX is -5.36% in extended hours to $133.76 (Robinhood). Positions (Tuesday official closes, Robinhood; re-verified line-by-line against this run's portfolio pull): SPCX 250 shares, avg $133.34, close $141.33 (+3.64% on Tuesday), +5.99% vs avg cost, unrealized +$1,998.48. NVDL 350 shares, avg $28.19, close $29.43 (+4.21%), +4.40% vs avg, unrealized +$434.18. SOFI 200 shares, avg $17.10, close $16.785 (+1.11%), -1.83% vs avg, unrealized -$62.50. QUBT 700 shares, avg $8.21, close $6.44 (+1.74%), -21.56% vs avg, unrealized -$1,239.00. Options (Tuesday close marks, Robinhood; marks sum $4,069 vs this run's portfolio option market value of $4,108 — the $39 difference is this morning's premarket mark move on the aggregate; quantities and clearing costs re-verified line-by-line): NVDA $215 calls expiring Mon Nov 16, 11 long, clearing cost $3,680, mark $3.10, market value $3,410 — 12 days to expiry; NVDA $205 calls expiring Fri Nov 6, 1 long, clearing cost $360, mark $5.00, market value $500 — 2 days; SPCX $148 calls expiring Fri Nov 6, 1 long, clearing cost $356, mark $1.59, market value $159 — 2 days. Futures: none — the position was fully closed on Oct 22 (web-verified on robinhood.com), and the API aggregate futures market value reads $0 this morning. Crypto: ETH 3.6 coins, clearing cost basis $8,608.00, mark $2,314.40 (Robinhood, ~7:16 AM ET), indicative value $8,331.84; USDG 1.0 unit on the API spot line (the API shows only the un-lent unit; Crypto Earn totals were last web-verified 2026-10-15 at 102.88 units total); dust: CC 1.0, DOGE 1.0, USDC 0.00993.
MarketsOnDeck — market data as cited, Wednesday November 4, 2026, pre-market. Not investment advice.
Apple and Palantir Beat Earnings — and Both Are Selling Off on Election Day, With AMD Reporting Tonight
Tuesday, November 3, 2026. Prepared premarket. Futures below are stamped 5:40 AM ET; stock indications are extended-hours marks around 7:18 AM ET, not opening prices.
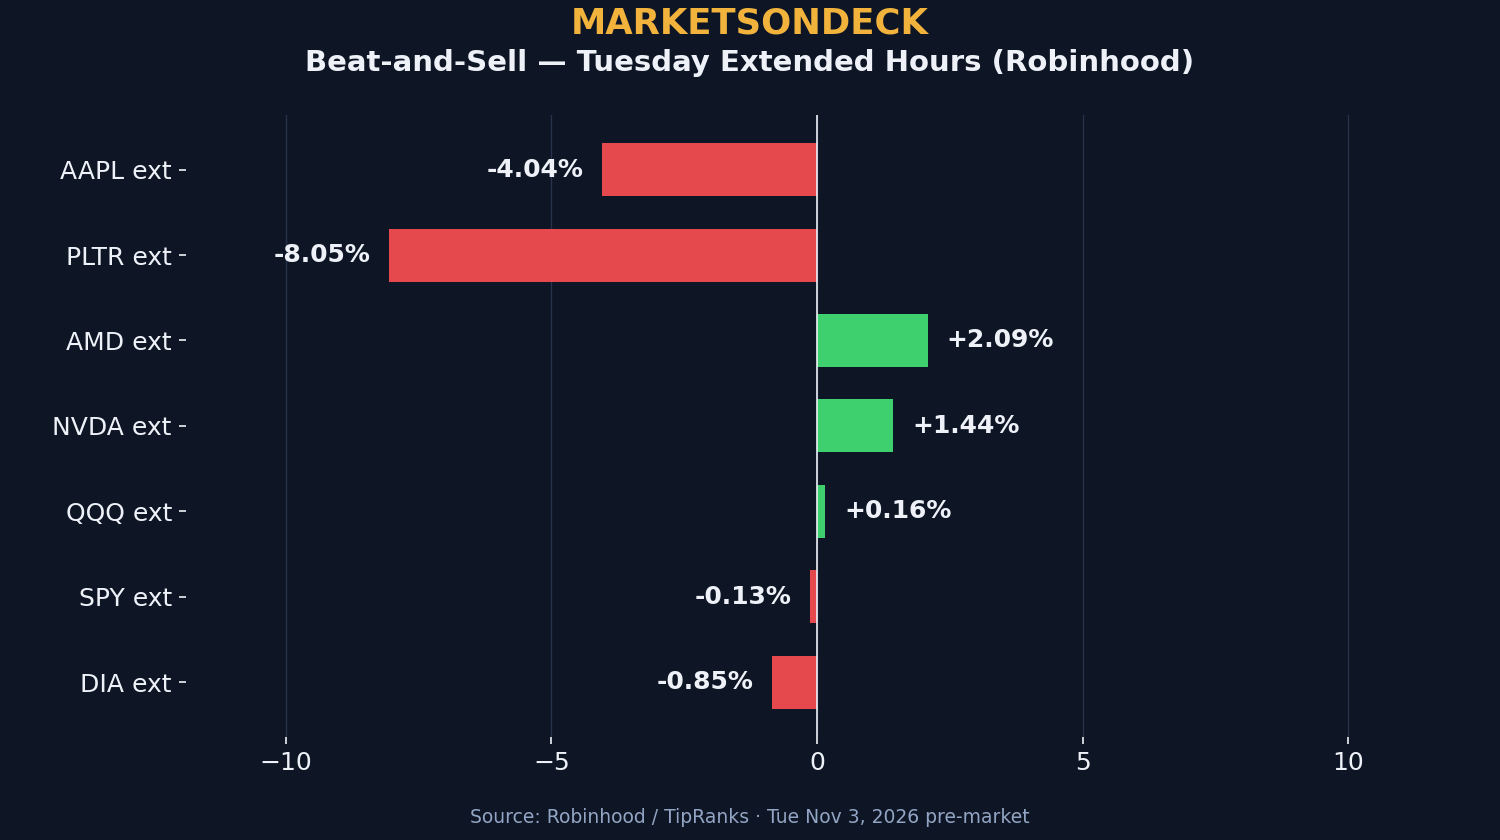
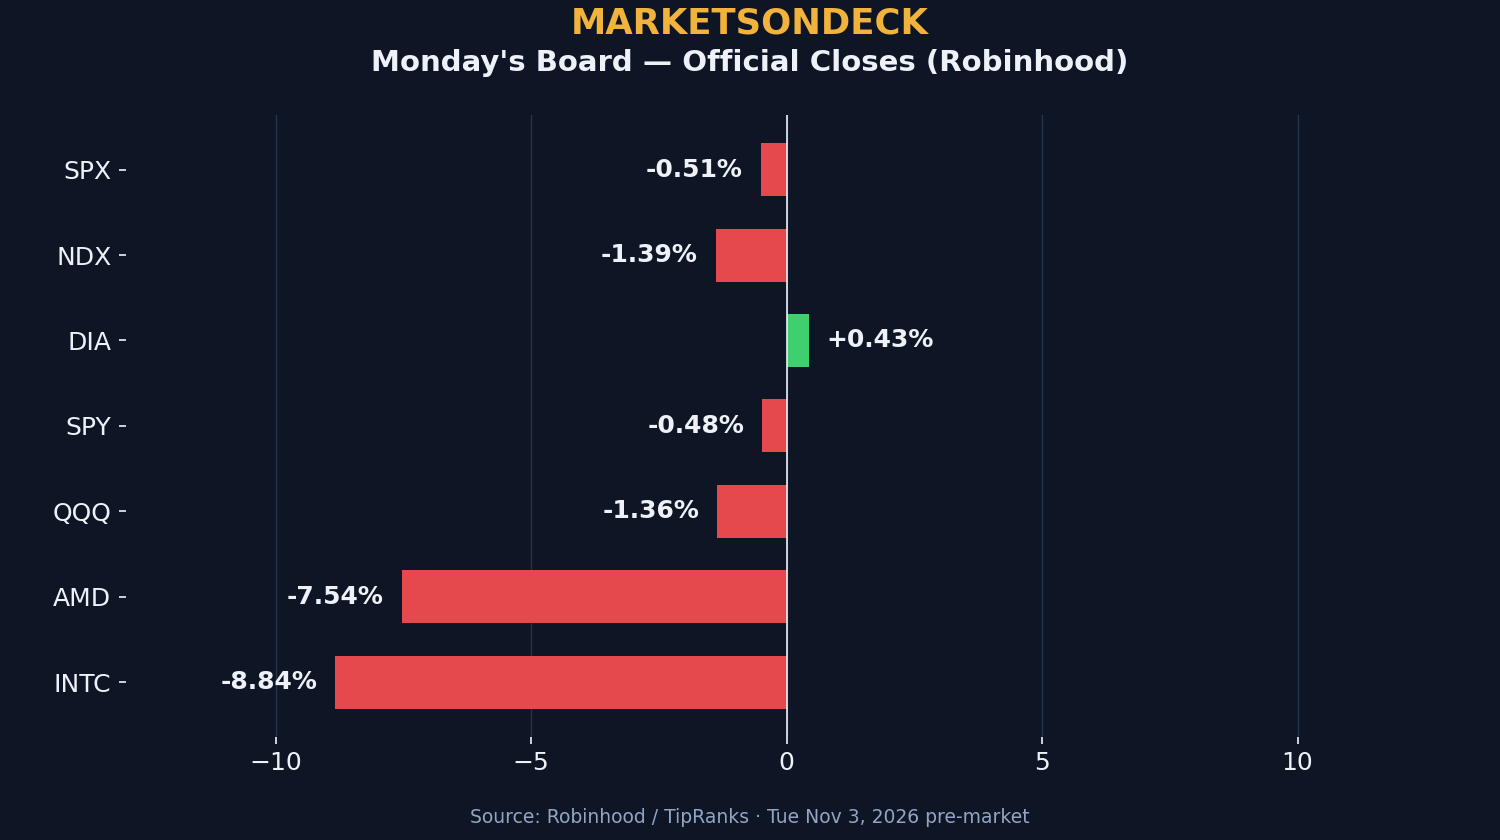
S&P 500 -0.51% · Nasdaq-100 -1.39% · Dow +0.41% — Monday's closes, percent only (Robinhood index quotes; DIA).
Apple fell 4.04% and Palantir fell 8.05% in extended-hours trading after both companies beat on earnings after Monday's close — and today America votes in the midterms, with AMD reporting after the close.
The setup. Monday was a rotation day that tech lost: the S&P 500 fell 0.51% to 7,541.40, the Nasdaq-100 fell 1.39% to 27,989.82 and the Russell 2000 fell 0.21%, while the Dow rose — DIA +0.43% (Robinhood index and ETF closes). SPY closed -0.48% and QQQ -1.36% (Robinhood). Chips were the drag again: AMD fell 7.54% to $466.74, Intel fell 8.84% and the VIX rose 8.91% to 21.15 (Robinhood). Tuesday's premarket is mixed and cautious into the midterm elections: Nasdaq-100 futures +0.40%, S&P 500 futures -0.05%, Dow futures -0.54% as of 5:40 AM ET, with the 10-year Treasury yield at 4.91% (TipRanks). Robinhood extended-hours marks agree — QQQ +0.16%, SPY -0.13%, DIA -0.85%. The VIX was at 21.63 Tuesday morning (Robinhood), Brent crude settled -7.63% at $104.77 on Monday, and Bitcoin's mark was $77,138.36 (Robinhood).
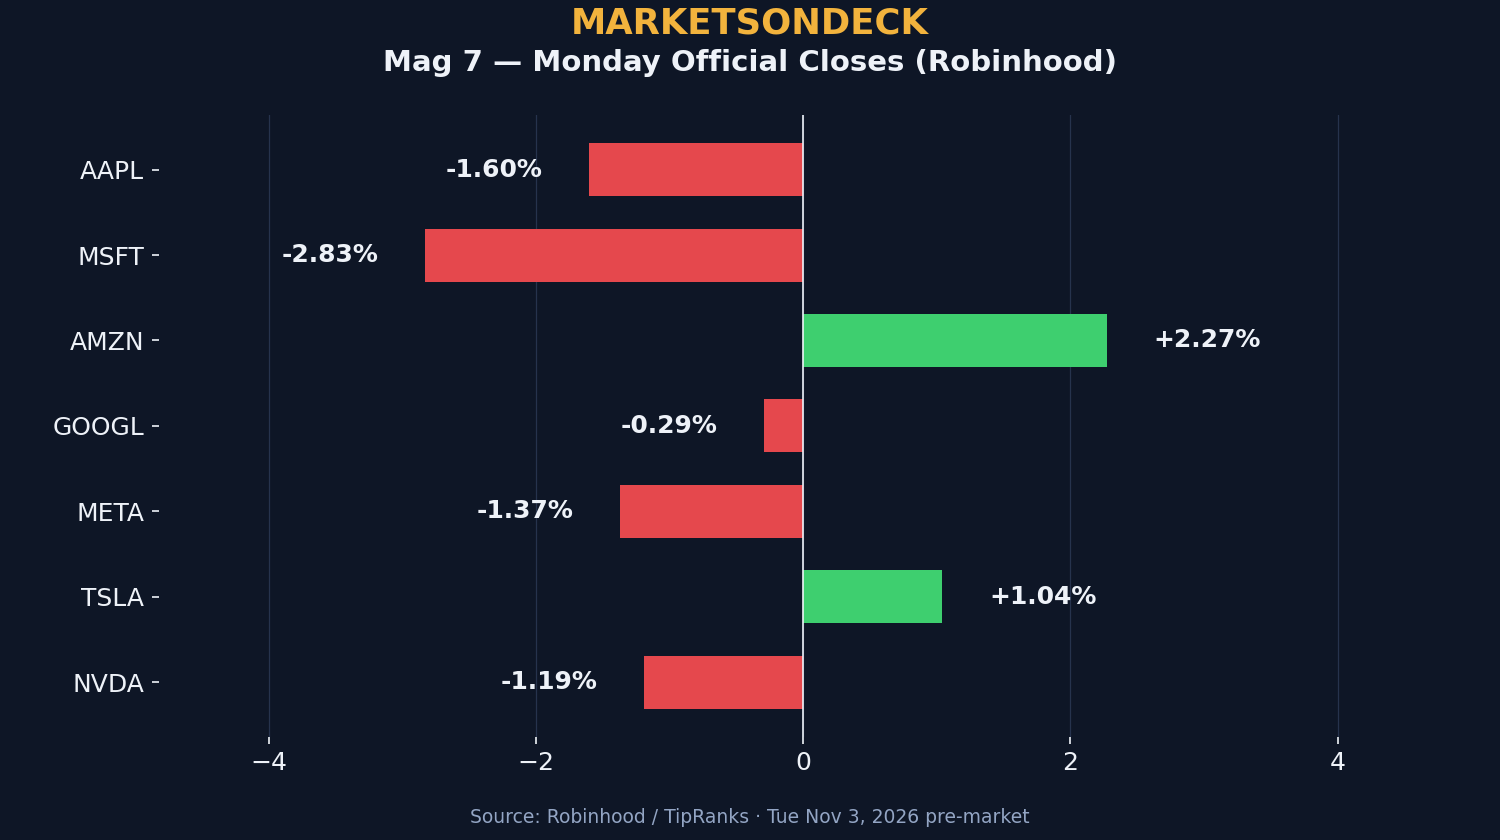
Apple's beat came with a margin warning. Apple closed Monday at $339.11, down 1.60% (Robinhood), then reported fiscal fourth-quarter diluted EPS of $2.10 against the $1.98 Robinhood-calendar estimate, on record September-quarter revenue of $114.48 billion, up 12% year over year (Robinhood earnings calendar; Apple). The problem was the guide: December-quarter gross margin of 45% to 46%, below the 46.3% analysts expected, with revenue guided to grow 7% to 10% (CNBC) — and the stock is down 4.04% in extended hours to $325.42 (Robinhood). Monday's other Mag 7 movers: Amazon +2.27% to $245.80 and Tesla +1.04% rose, while Microsoft fell 2.83%, Meta 1.37%, Nvidia 1.19% to $202.20 and Alphabet 0.29% (Robinhood). Nvidia is +1.44% in extended hours.
Palantir's beat was bigger — and the sell-off is too. Palantir reported EPS of $0.44 vs $0.39 estimated and revenue of $2.313 billion, up 96% year over year, with U.S. commercial revenue passing U.S. government revenue for the first time (Robinhood earnings calendar; SiliconANGLE). It closed Monday at $178.62, down 2.98% (Robinhood), and is down another 8.05% in extended hours to $164.25. The pattern from October is repeating: in this market a beat is the entry fee, not the reward. Monday's other after-close beats: Vertex ($4.76 vs $4.70), Diamondback Energy ($5.86 vs $5.46), Clorox ($1.55 vs $1.05) and Roku ($1.20 vs $0.55) (Robinhood earnings calendar). This morning's reporters mostly beat too: Pfizer ($0.87 vs $0.73), Shopify ($0.49 vs $0.43) and DuPont ($2.09 vs $1.87) (Robinhood).
What to watch today:
- Election Day, Tuesday November 3 — the midterm elections decide control of Congress; markets stay open and results land overnight (TipRanks).
- 10:00 AM ET — September JOLTS job openings (forecast 7.11M, prior 7.08M) and factory orders (forecast +1.2%, prior +0.1%) (FXEmpire week-ahead calendar).
- After the close — AMD ($1.89 estimated EPS, Robinhood), plus Amgen ($5.77), Arista Networks ($1.06), Super Micro ($1.20), Booking Holdings ($4.49) and Block ($0.96) (Robinhood earnings calendar). AMD is +2.09% in extended hours after Monday's -7.54%.
- Friday, November 6 at 8:30 AM ET — the October jobs report closes the week.
MarketsOnDeck — market data as cited, Tuesday November 3, 2026, pre-market. Not investment advice.
Apple Reports Tonight, Futures Are Bouncing — and the Nasdaq Composite Just Posted Its Worst Month Since March 2025
Monday, November 2, 2026. Prepared premarket. Futures below are stamped 1:38 AM ET; stock indications are extended-hours marks around 7:17 AM ET, not opening prices.
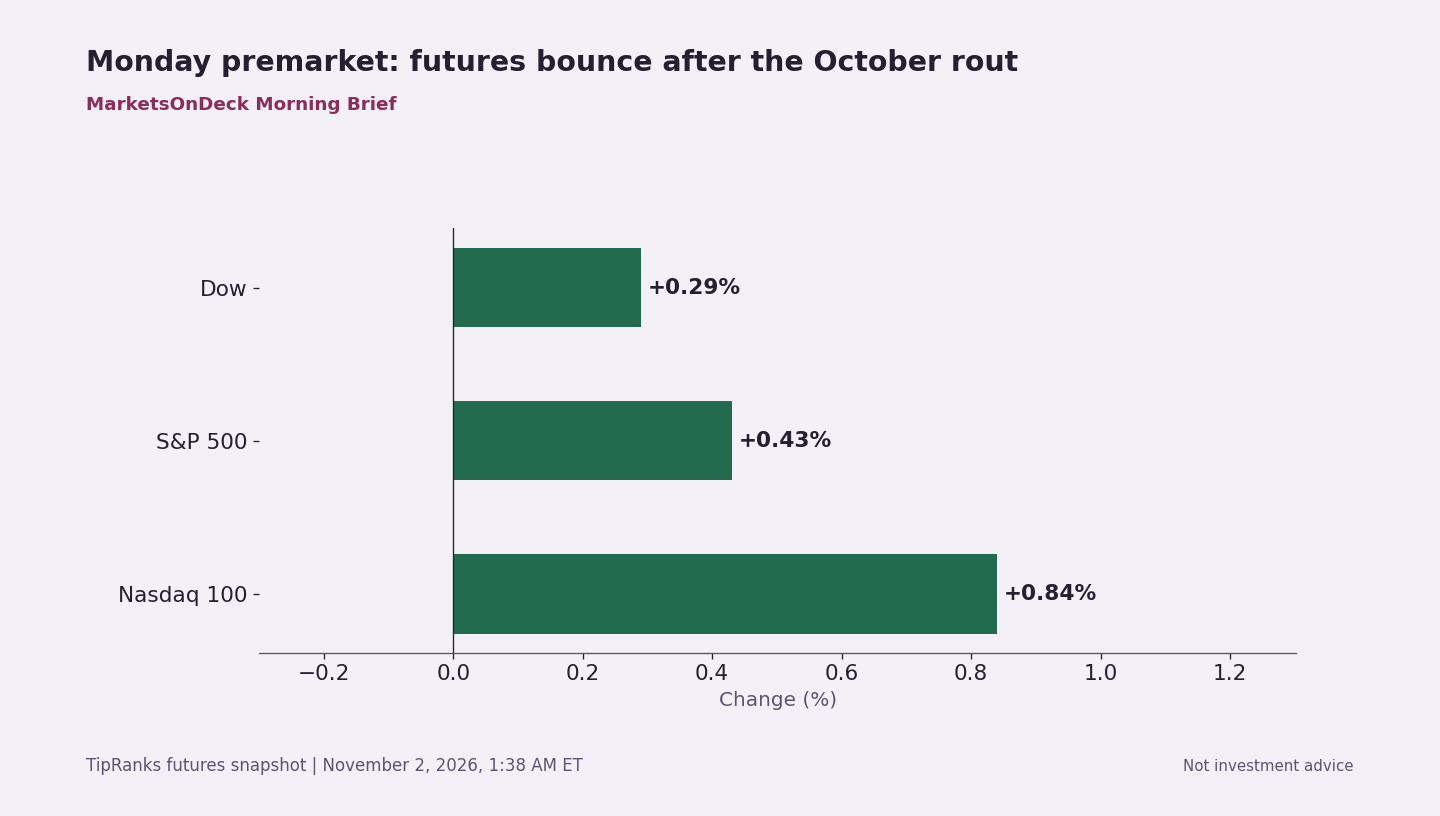
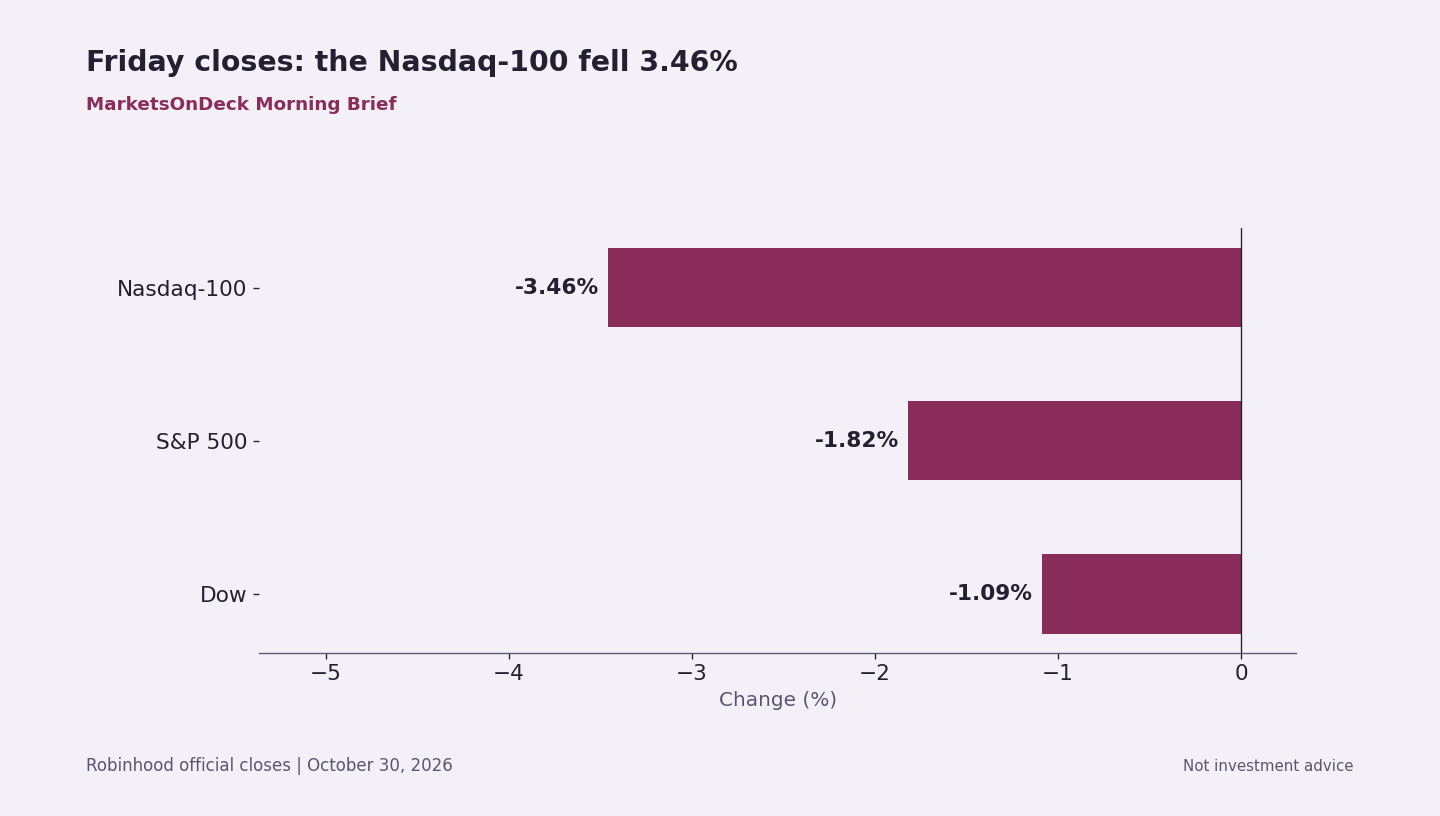
S&P 500 -1.82% · Nasdaq-100 -3.46% · Dow -1.09% — Friday's closes, percent only (Robinhood index quotes; DIA).
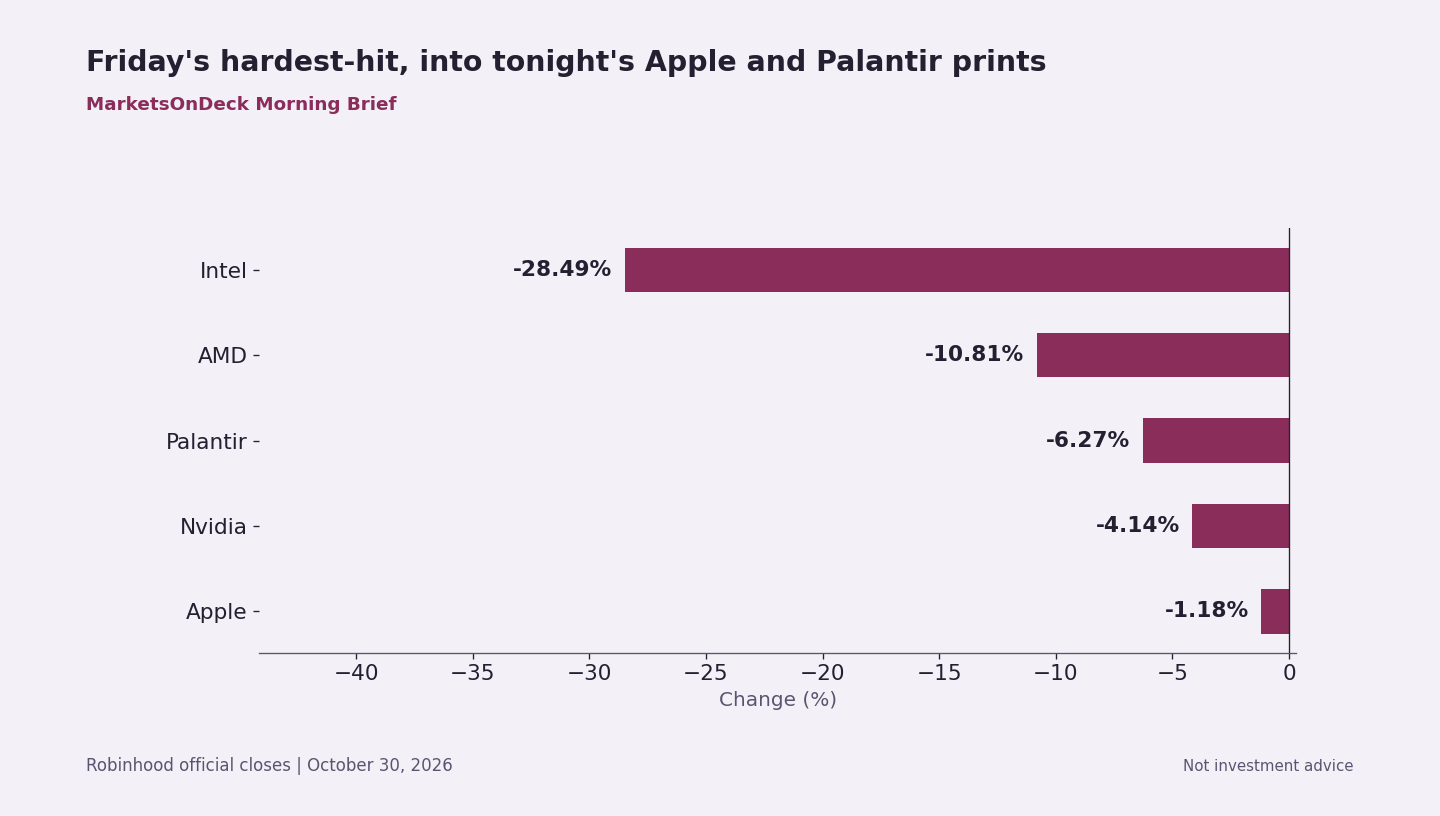
Nasdaq-100 futures are up 0.84% and S&P 500 futures up 0.43% after a Friday rout that cut the Nasdaq-100 3.46% and Intel 28.49% — and tonight Apple and Palantir report after the close, 24 hours before the midterm elections, with October's jobs report waiting on Friday.
The setup. Friday closed out a brutal October: the S&P 500 fell 1.82% to 7,580.07, the Nasdaq-100 fell 3.46% to 28,384.85 and the Dow fell 1.09% (Robinhood index quotes), with SPY -1.78% and QQQ -3.47% at the official closes (Robinhood). Intel fell 28.49% to $65.84, its worst day since 1974, after its fourth-quarter guide missed. For October as a whole, the Nasdaq Composite recorded its biggest monthly decline since March 2025 (TipRanks; MarketWatch and CNN confirm). Monday's premarket is a bounce, not a reversal: Nasdaq-100 futures +0.84%, S&P 500 futures +0.43%, Dow futures +0.29% as of 1:38 AM ET (TipRanks), and Robinhood extended-hours marks agree — QQQ +0.86%, SPY +0.46%, DIA +0.49%. The VIX was at 19.23 Monday morning (Robinhood), Brent crude fell 3.05% to $109.97 (TipRanks), and Bitcoin's mark was $77,918.02 (Robinhood).
Apple tonight is the week's first verdict. Apple closed Friday at $344.80, down 1.18% (Robinhood), and reports fiscal fourth-quarter results after today's close — Robinhood's earnings calendar carries an EPS estimate of $1.98. The guide is the bar: the company previously projected revenue growth of 9% to 11% year over year, iPhone revenue growth in the mid-teens, and gross margin of 47% to 48% (TradingKey). After a month in which the market punished AI spending plans at name after name, Apple's spending and margin commentary will be graded the same way. The rest of Friday's Mag 7 all fell too — Nvidia -4.14% to $204.81, Microsoft -1.55%, Meta -1.53%, Alphabet -1.38%, Amazon -1.36%, Tesla -0.86% (Robinhood) — and Nvidia is leading the early recovery, +1.17% in extended hours.
Palantir is the other after-close print. Palantir closed Friday at $184.10, down 6.27% (Robinhood), and reports tonight with a Robinhood EPS estimate of $0.39 against the company's own third-quarter revenue guide of $2.160 billion to $2.164 billion. It is +1.25% in extended hours. AMD, down 10.81% Friday to $505.18 (Robinhood), reports Tuesday night. This morning's reported names mostly beat: Estée Lauder ($0.72 vs $0.51 estimated), IDEXX ($4.01 vs $3.71), Marriott ($3.02 vs $2.85) and Check Point ($2.49 vs $2.39); CNA missed ($0.75 vs $1.14) (Robinhood earnings calendar).
What to watch today:
- 10:00 AM ET, Monday November 2 — the October ISM Manufacturing PMI (estimate 54.6, prior 54.5 — CoinDesk calendar), the session's only scheduled data test of the bounce.
- After the close — Apple ($1.98 estimated EPS, Robinhood) and Palantir ($0.39 estimated), plus Vertex ($4.70), Diamondback Energy ($5.46), Clorox ($1.05) and Roku ($0.55) (Robinhood earnings calendar).
- The week behind it — the U.S. midterm elections on Tuesday, November 3 (markets stay open), AMD on Tuesday night, and the October jobs report on Friday, November 6 at 8:30 AM ET (Dow Jones poll: +55,000 jobs — via JKN).
MarketsOnDeck — market data as cited, Monday November 2, 2026, pre-market. Not investment advice.
Intel Falls 26% Before the Bell as Nasdaq Futures Slide After Tech Earnings
Friday, October 30, 2026. Prepared premarket. Futures below are stamped 5:36 AM ET; stock indications are extended-hours marks around 7:17 AM ET, not opening prices.
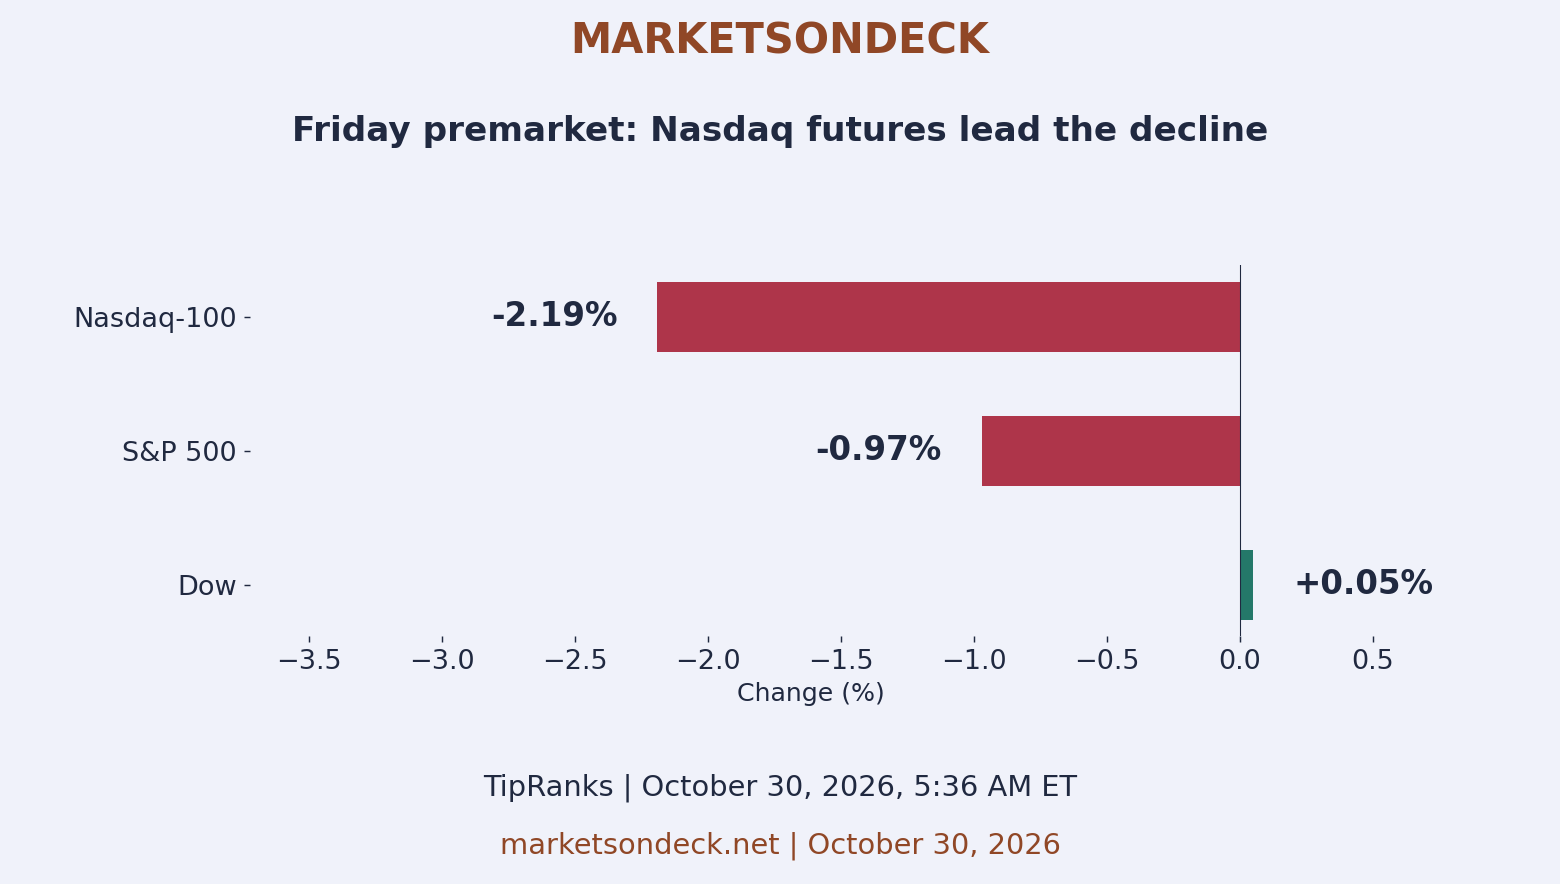
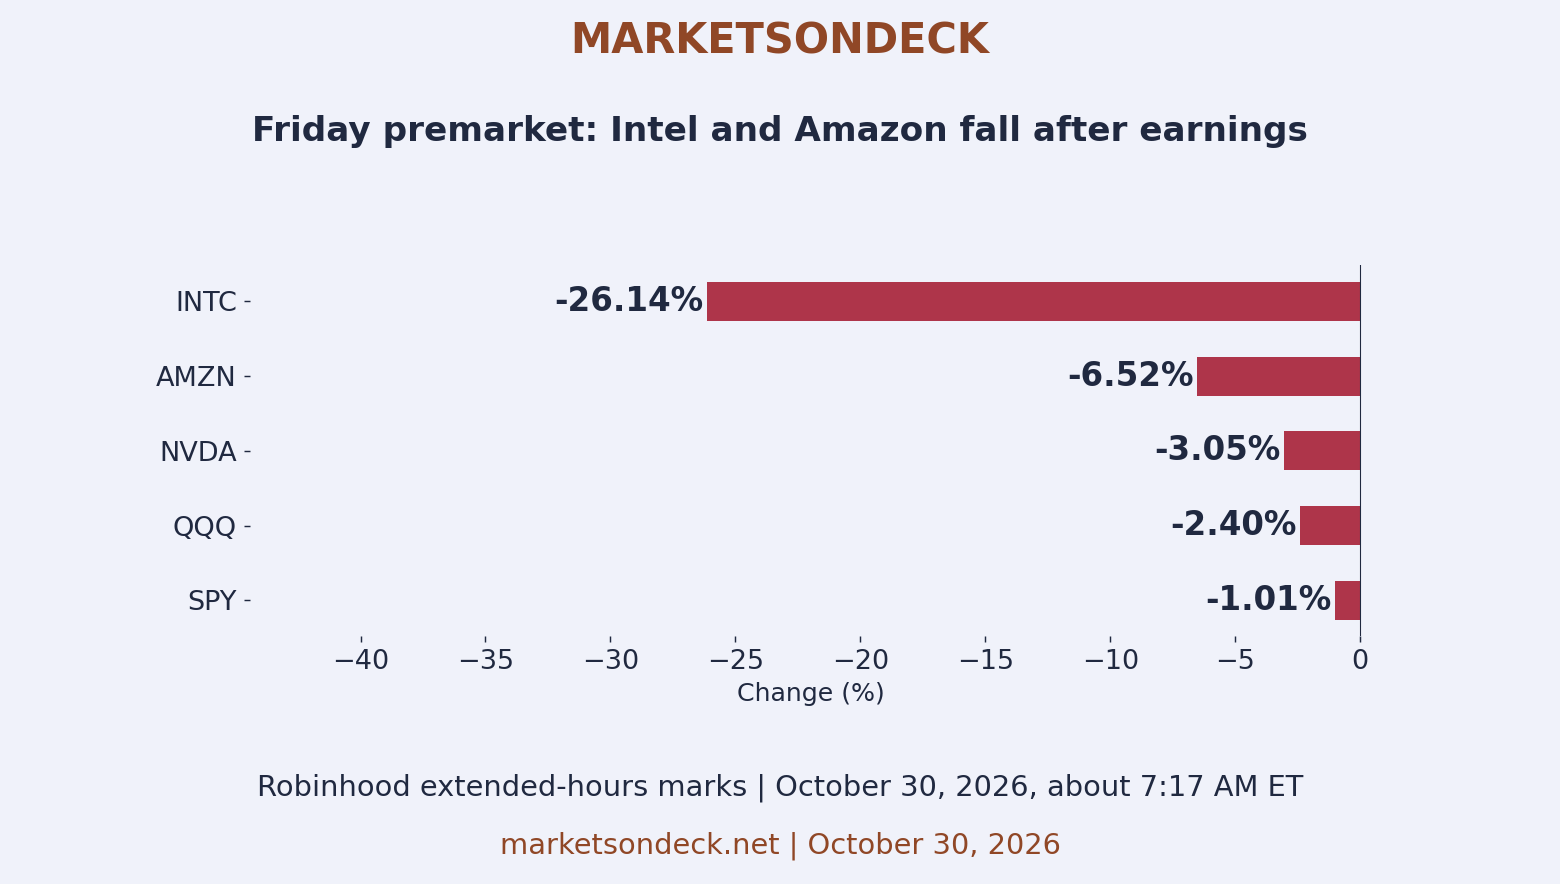
Intel was down 26.14% and Amazon 6.52% in extended-hours trading after Thursday's earnings. Nasdaq-100 futures were down 2.19%, S&P 500 futures 0.97%, while Dow futures edged up 0.05% at 5:36 AM ET, according to TipRanks.
The setup
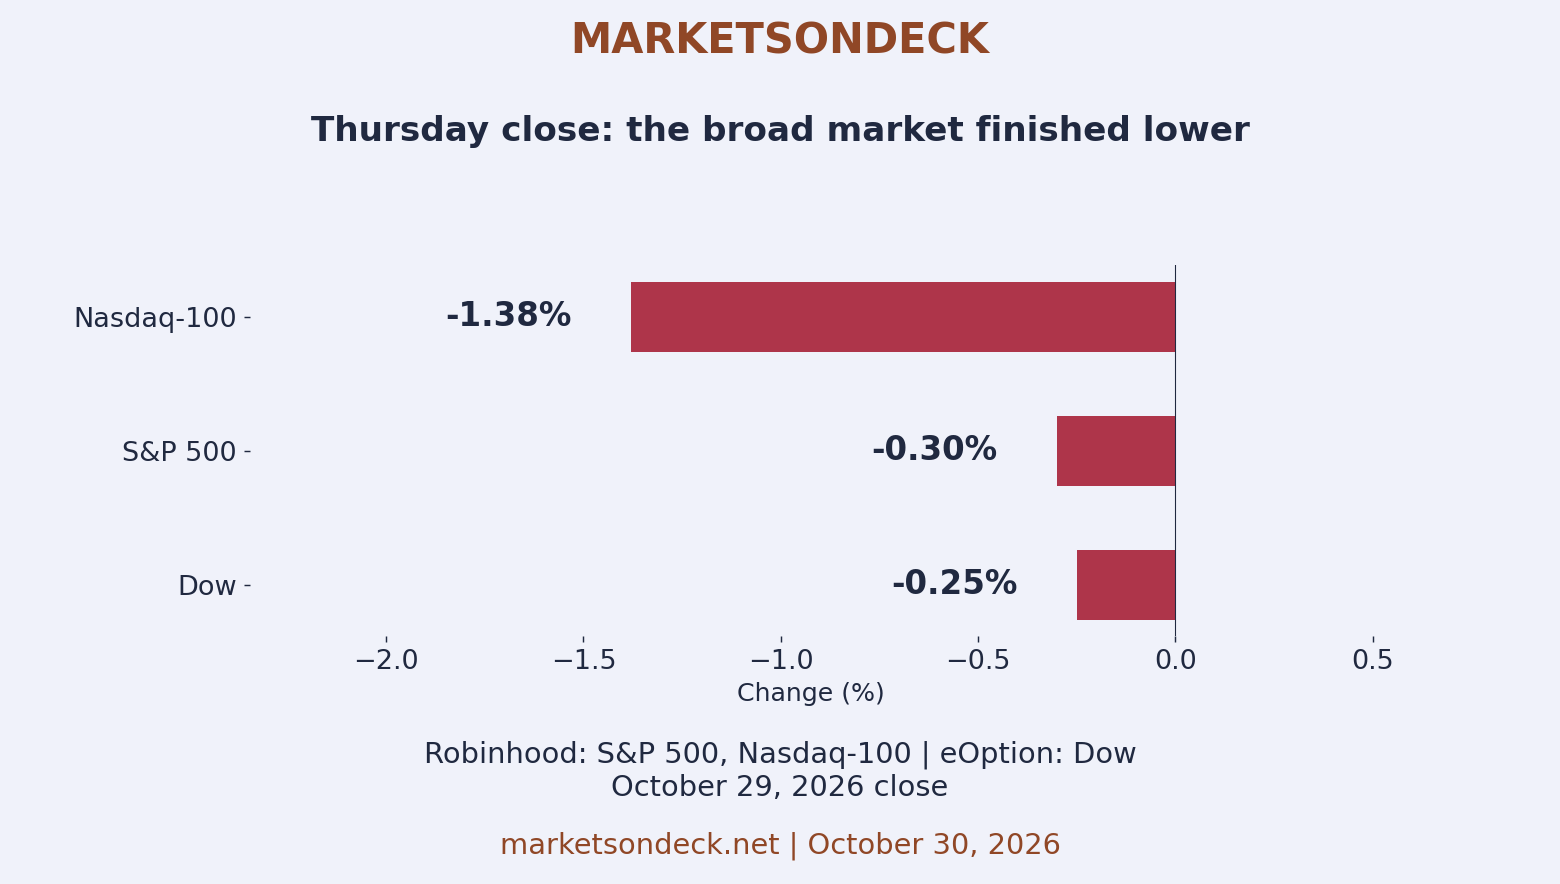
Thursday's S&P 500 fell 0.30% to 7,720.39, the Nasdaq Composite fell 1.38%, and the Dow fell 0.25%. CNBC's closing report attributed the pressure to corporate earnings, including Alphabet's sharp decline.
The Nasdaq-100 also fell 1.38% to 29,402.51, confirmed by Yahoo Finance historical data. Friday's futures snapshot shows the pressure extending into another session, rather than an opening result that has already happened.
Amazon: cloud growth and a cash outflow
Amazon's results showed third-quarter sales of $201.9 billion and diluted EPS of $1.89. AWS sales grew 39% to about $46.0 billion, while operating income rose to $28.1 billion.
The company reported a trailing-12-month free-cash-flow outflow of $42.4 billion and maintained its $220 billion cash capital-spending forecast for 2026. Fourth-quarter sales guidance was $240 billion to $247 billion.
CNBC reported that EPS and revenue missed LSEG consensus of $1.96 and $202.31 billion, respectively. The comparison uses LSEG consensus.
Intel: growth in the quarter, weaker guidance ahead
Intel reported third-quarter revenue of $16.5 billion, up 21%, and adjusted EPS of $0.52. Data Center and AI revenue grew 78% to $7.3 billion, while client computing revenue fell 5% to $8.1 billion.
For the fourth quarter, Intel forecast revenue of $15 billion to $16 billion and adjusted EPS of $0.25. CNBC's LSEG comparison put expectations at $17.1 billion and $0.43. Intel's CFO said the PC slowdown could continue through at least the first half of next year.
Big Oil's different morning
ExxonMobil reported adjusted EPS of $4.23 and Chevron $5.28. Reuters reported that both beat expectations as higher refining margins supported results. Exxon earned more from refining than upstream for the first time in at least six years.
What to watch today
- Employment costs: the third-quarter Employment Cost Index is scheduled for 8:30 AM ET, according to the BLS release calendar. This premarket draft does not contain the released result.
- At the open: whether Intel and Amazon retain their indicated losses, and whether the Dow's early relative strength holds. Premarket prices can change substantially before the bell.
- Month-end: Friday is the last trading day of October. Separate closing flows from any new company or economic news.
The OnDeck Book
Today's account comparison and position details are being updated and are not included in this edition.
MarketsOnDeck. Not investment advice.
Drafted premarket Thursday, October 29, before the opening bell, after Wednesday’s Fed-day close; published mid-morning.
Bloomberg and Two Trading Firms Sign Up for Faster Access to Trump’s Truth Social Posts, Reuters Reports
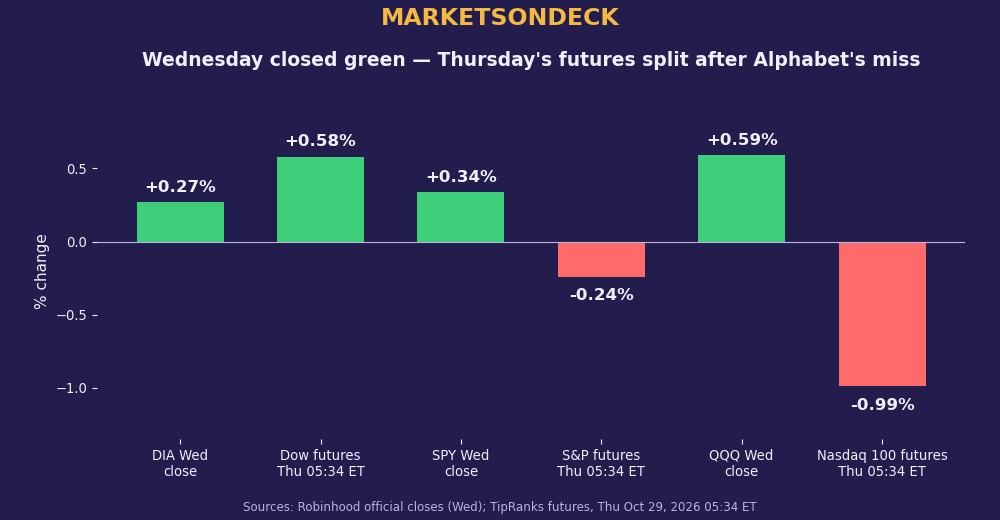
Q3 GDP +3.4% annualized · September PCE +3.6% y/y, core +3.1% — both released at 8:30 AM ET (BEA). Drafted premarket: Nasdaq 100 futures were down 0.99% and Dow futures up 0.58% at 5:34 AM ET (TipRanks) after Alphabet’s miss.
Bloomberg, Susquehanna International Group and Jump Trading have agreed to pay Truth Social for faster access to President Trump's posts, Reuters reported overnight, citing people with direct knowledge — a service with a list price of up to $100,000 a month that delivers about a 50-millisecond head start — on the morning GDP and PCE land at 8:30 AM ET and Nasdaq futures sit about 1% lower after Alphabet's miss.
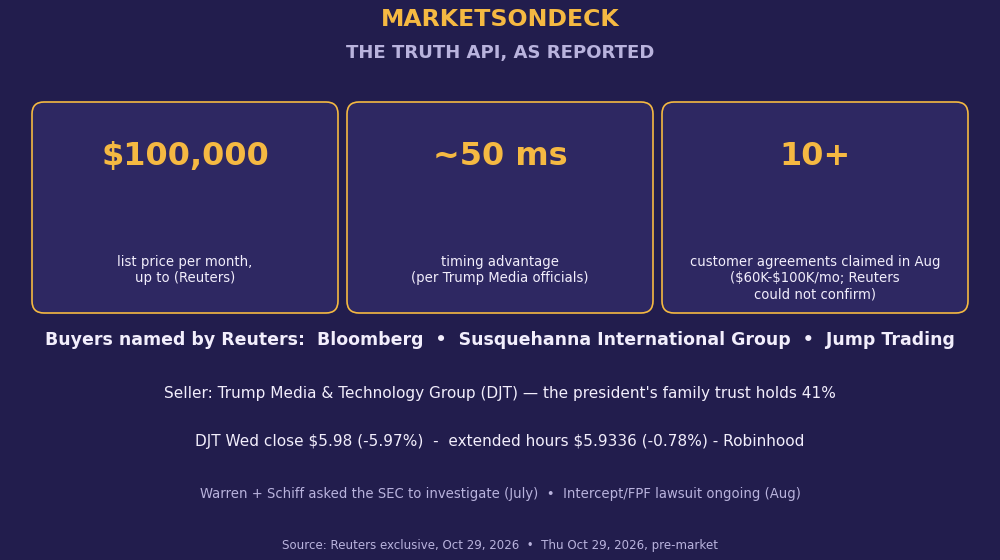
Bloomberg LP and two high-frequency trading firms have agreed to pay Truth Social for faster access to President Trump's posts, Reuters reported overnight, citing people with direct knowledge. The two firms are Susquehanna International Group and Jump Trading, whose software ingests headlines and executes trades in thousandths of a second. The seller is Trump Media & Technology Group (Nasdaq: DJT), the company the president founded, which is 41% owned by his family trust. The product is called Truth API: Trump Media announced it in July and pitched it to trading firms and financial institutions, and it delivers posts from 10 influential Truth Social accounts, including the president's, with archives back to 2022.
Trump Media officials describe the timing advantage as about 50 milliseconds. The service sells for up to $100,000 a month; Reuters did not report what each subscriber agreed to pay. Trump's posts have moved prices — oil futures sank in April after he announced the Iran war ceasefire on Truth Social, Reuters noted — and Reuters says the service has the potential to give Wall Street traders an edge not available to everyday investors on posts that can move markets. The deals likely mark the first time a business tied to a sitting president has sold access to their statements, according to Reuters. Trump Media told investors in August it had signed more than 10 customer agreements at $60,000 to $100,000 a month, a claim Reuters could not confirm; at those prices, 10 clients would represent roughly $7 million to $12 million a year in reported revenue.
The company has lost about $1.76 billion since 2024, including non-cash charges, and its shares are down more than 50% this year, to a market value near $1.8 billion, Reuters reports. DJT closed Wednesday at $5.98 (-5.97%, Robinhood official close) and was at $5.9336 in extended hours Thursday morning (-0.78%, Robinhood).
The critics. Senators Elizabeth Warren and Adam Schiff asked the SEC in July to investigate whether the service violates securities laws, calling it a "shocking abuse" of office by a president seeking personal gain, according to Reuters; the SEC declined to comment. Intercept Media and the Freedom of the Press Foundation sued in August, seeking to block the White House from posting official government announcements exclusively on Truth Social while the paid feed exists; the suit, which is ongoing, alleges that a financial barrier to government information is potentially unconstitutional under the First and Fifth Amendments and favors wealthy Wall Street firms, and the plaintiffs have described the service as "profoundly corrupt." THE RESPONSE: Trump Media calls Truth API an "industry-standard API product" with "significant demand across industries," and says the reporting is misleading information being peddled by anonymous sources; a company spokesperson said congressional Democrats mischaracterize Truth API, citing the distinction between public and nonpublic information. White House spokesman Davis Ingle said neither Trump nor his family is directly involved in portfolio investment decisions, and said Trump only acts in the best interests of the American public. Bloomberg, Jump Trading and Susquehanna declined to comment.
The question the mechanics raise for everyone who is not paying $100,000 a month: when a market-moving statement is sold with a faster lane, what does the public feed's 50-millisecond delay cost the people reading it second? Source: Reuters exclusive, via Investing.com syndication.
The setup. Wednesday was a third straight modest advance into the Fed: the S&P 500 rose 0.28% to 7,743.98 (Robinhood index quote), the Nasdaq Composite rose 0.27% to 26,550 and the Dow rose 0.19% to 52,475 (TalkMarkets/NordFX market pulse), with Robinhood's ETF closes agreeing — SPY $772.31 (+0.34%), QQQ $725.48 (+0.59%) and DIA $524.68 (+0.27%). The Federal Reserve held at 3.75%–4.00% in a 10–2 vote; Governors Cook and Hammack both wanted an immediate hike, December hike odds rose as high as 83%, and the 10-year Treasury yield closed near 5.04% (NordFX/TalkMarkets). Thursday's premarket splits hard on Wednesday night's earnings: Nasdaq 100 futures were down 0.99% and S&P 500 futures down 0.24% at 5:34 AM ET while Dow futures rose 0.58% (TipRanks), and Robinhood extended-hours marks agree — QQQ -0.96%, SPY -0.21%, DIA -0.06% vs Wednesday's closes. Alphabet sank about 10% after hours on a revenue and profit miss — its first double miss in nearly four years, with free cash flow of negative $9.1 billion (Reuters via TradingNerve; Gulf News) — while Microsoft rose after Azure revenue grew 48% (Gulf News). Robinhood extended hours: Alphabet $289.75 (-11.02%), Microsoft $541.18 (+1.78%). Crypto is softer: Bitcoin's Robinhood mark was $80,083.23 and Ether's $2,321.54 on Thursday morning. The VIX sat at 16.98. Brent crude was down 0.82% at $114.38 early Thursday (TipRanks).
Why it moved. Wednesday's Mag 7 (Robinhood official closes): Alphabet $325.63 (+1.58%) led, Amazon $254.65 (+0.61%) and Microsoft $531.73 (+0.08%) edged up, while Tesla $404.46 (-0.74%), Apple $343.86 (-0.93%), Nvidia $215.39 (-1.17%) and Meta $612.41 (-1.26%) fell. After the close the group split on the AI bill: Alphabet missed on both revenue and profit, kept its 2026 capex plan at $195 billion to $205 billion, and posted a second straight quarter of negative free cash flow (CNBC via TradingNerve) — the stock is down 11.02% in Robinhood extended hours. Microsoft beat, with Azure up 48% to $33.2 billion against a $32.3 billion forecast, and guided Azure growth of 49% to 50% this quarter (Gulf News) — up 1.78% in extended hours. The grading rule the market is applying is now plain in the numbers: big AI budgets pass while free cash flow stays positive. Amazon is the next test, after the close Thursday ($1.97 estimated, Robinhood earnings calendar), with its own capital-spending plans under the same microscope.
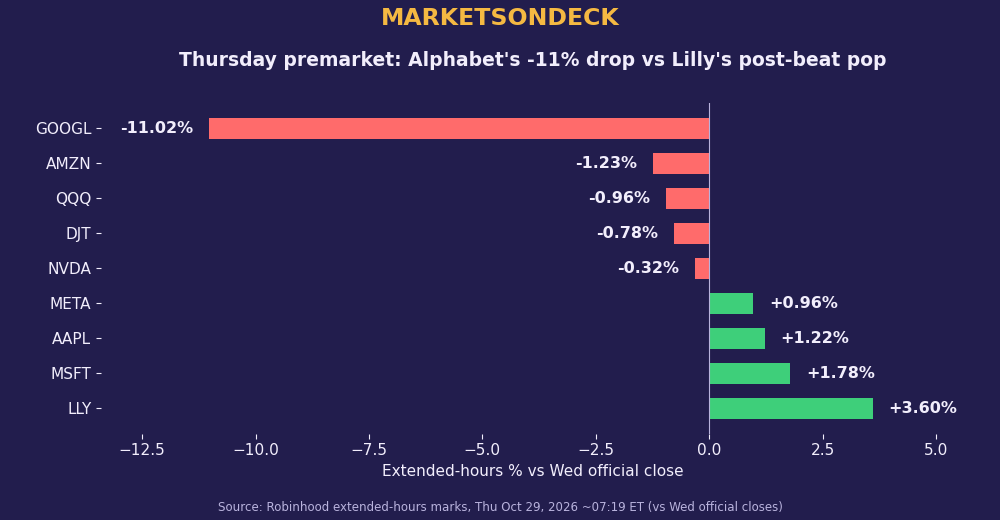
Thursday’s catalysts. Thursday's 8:30 AM ET releases landed close to expectations (BEA): third-quarter GDP grew at a 3.4% annual rate in the advance estimate, up from 2.2% in the second quarter, and September PCE inflation ran 0.5% month over month and 3.6% year over year, with core at 0.3% and 3.1% — the hot monthly headline feeds the December-hike pricing that followed Wednesday's two hawkish dissents. Thursday's pre-open earnings are already landing (Robinhood earnings calendar): Eli Lilly beat, $7.48 actual vs $6.36 estimated, and raised its full-year revenue forecast to $91 billion to $92 billion on weight-loss drug demand, with third-quarter revenue of $24.4 billion vs $22.61 billion expected (Reuters); Lilly was up 3.60% in Robinhood extended hours at $1,335.54. Merck beat ($2.49 vs $2.10) and Caterpillar beat ($7.20 vs $7.05); Mastercard ($5.16 estimated) reports before the open. After the close Thursday: Amazon ($1.97 estimated), Intel ($0.37), SanDisk ($46.36), Gilead ($2.18), Coinbase ($0.02) and Starbucks ($0.71) (Robinhood). The ECB also decides Thursday, with a hold at 2.50% expected (NordFX).
What to watch today. How the morning's GDP (+3.4% annualized) and September PCE (+3.6% year over year, core +3.1%) prints feed or cool the December-hike trade, whether Alphabet's premarket drop (-11.02% before the open) holds, DJT in its first session after the Reuters Truth API story, Eli Lilly's post-beat strength, and Amazon after the close.
The OnDeck Book
Trading fell 7.52% on Wednesday and Agentic rose 0.64% on Wednesday (percent only, Robinhood) vs the S&P 500's +0.28%, the Nasdaq Composite's +0.27% and the Dow's +0.19%. In Thursday's premarket the accounts were about -0.8% and +1.7% respectively against Wednesday's close (Robinhood extended hours). Positions (Wednesday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $145.22 (-2.26% on Wednesday), +9.91% vs avg cost, unrealized +$1,963.47. SOFI 200 shares, avg $17.10, close $17.14 (+4.51%), +0.25% vs avg, unrealized +$8.50. QUBT 700 shares, avg $8.21, close $6.93, -15.59% vs avg, unrealized -$896.00. Options (marks at Wednesday's close, Robinhood; total option market value $10,021; all long calls, all expiring within 8 days — the Nov 4 lines are flagged, expiring within 7 days): SPCX $148 calls expiring Wed Nov 4, 7 long, clearing cost $2,698 total, mark $2.90, market value $2,030 — expiring within 7 days; NVDA $215 calls expiring Wed Nov 4, 2 long, clearing cost $880, mark $4.60, market value $920 — expiring within 7 days; NVDA $217.50 calls expiring Wed Nov 4, 4 long, clearing cost $1,814, mark $3.35, market value $1,340 — expiring within 7 days; SPCX $148 calls expiring Fri Nov 6, 11 long, clearing cost $4,903, mark $3.53, market value $3,883; SPCX $152.50 calls expiring Fri Nov 6, 7 long, clearing cost $1,940, mark $2.02, market value $1,414; NVDA $222.50 calls expiring Fri Nov 6, 2 long, clearing cost $720, mark $2.17, market value $434. Futures: none — the position was fully closed on Oct 22 and nothing is held this morning. Crypto: ETH 3.6 coins, cost basis $8,608.00, marked $2,321.54 in Thursday's premarket (Robinhood), an indicative value of about $8,358; USDG 102.88 units including Crypto Earn (last checked October 15); dust: DOGE 1.0, USDC 0.00993.
Also on Medium: Bloomberg and Two Trading Firms Sign Up for Faster Access to Trump’s Truth Social Posts, Reuters Reports.
Drafted premarket Wednesday, October 28, before the opening bell, after Tuesday’s close.
Micron Is Up 4% Before the Bell, the Fed Decides at 2 PM, and Microsoft and Alphabet Report Tonight — Wednesday Is the AI Trade’s Judgment Day
S&P 500 +0.60% · Nasdaq +1.18% · Dow +0.03% — Tuesday’s closes, percent only (Robinhood index quote; Stocktwits).
Micron is up 3.98% in extended hours after SK Hynix’s quarterly profit jumped more than sevenfold (Reuters), Nasdaq 100 futures rose 0.41% at 4:53 AM ET while Dow futures fell 0.17% — and that is only the warm-up: the Federal Reserve decides at 2 PM ET today, and Microsoft and Alphabet put the AI trade on trial after the close.
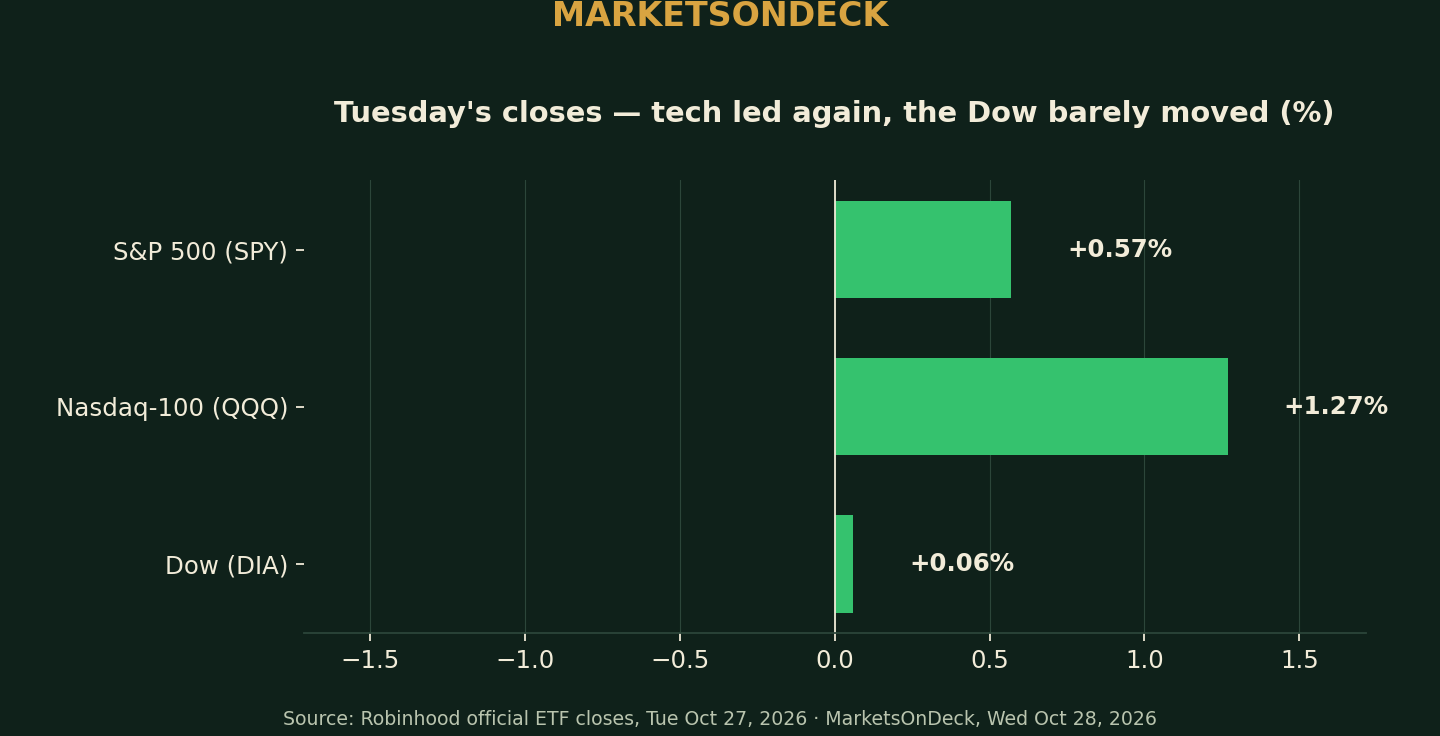
The setup. Tuesday was another tech-led advance: the S&P 500 rose 0.60% to 7,722.60 (Robinhood index quote), the Nasdaq Composite rose 1.18% to 26,477.81 and the Dow edged up 0.03% to 52,377.57 (Stocktwits), with Robinhood’s ETF closes agreeing — SPY $769.72 (+0.57%), QQQ $721.24 (+1.27%) and DIA $523.26 (+0.06%). Broadcom’s $63 billion bank financing to buy chips for Anthropic powered the chip complex on Tuesday (FXStreet), while Boeing’s 10.70% plunge capped the Dow. Wednesday morning the split widens: at 4:53 AM ET, Dow E-minis were down 88 points (-0.17%), S&P 500 E-minis up 7.25 points (+0.10%) and Nasdaq 100 E-minis up 122 points (+0.41%) (Reuters). Treasury yields are the headwind nobody can ignore — the 10-year rose back above 5% and the 30-year traded close to 5.32% ahead of the decision (WSJ). Crypto is firmer: Bitcoin’s Robinhood mark was $81,259.48 on Wednesday morning, back above $80,000, and Ether’s mark was $2,359.68. The VIX sat at 17.50.
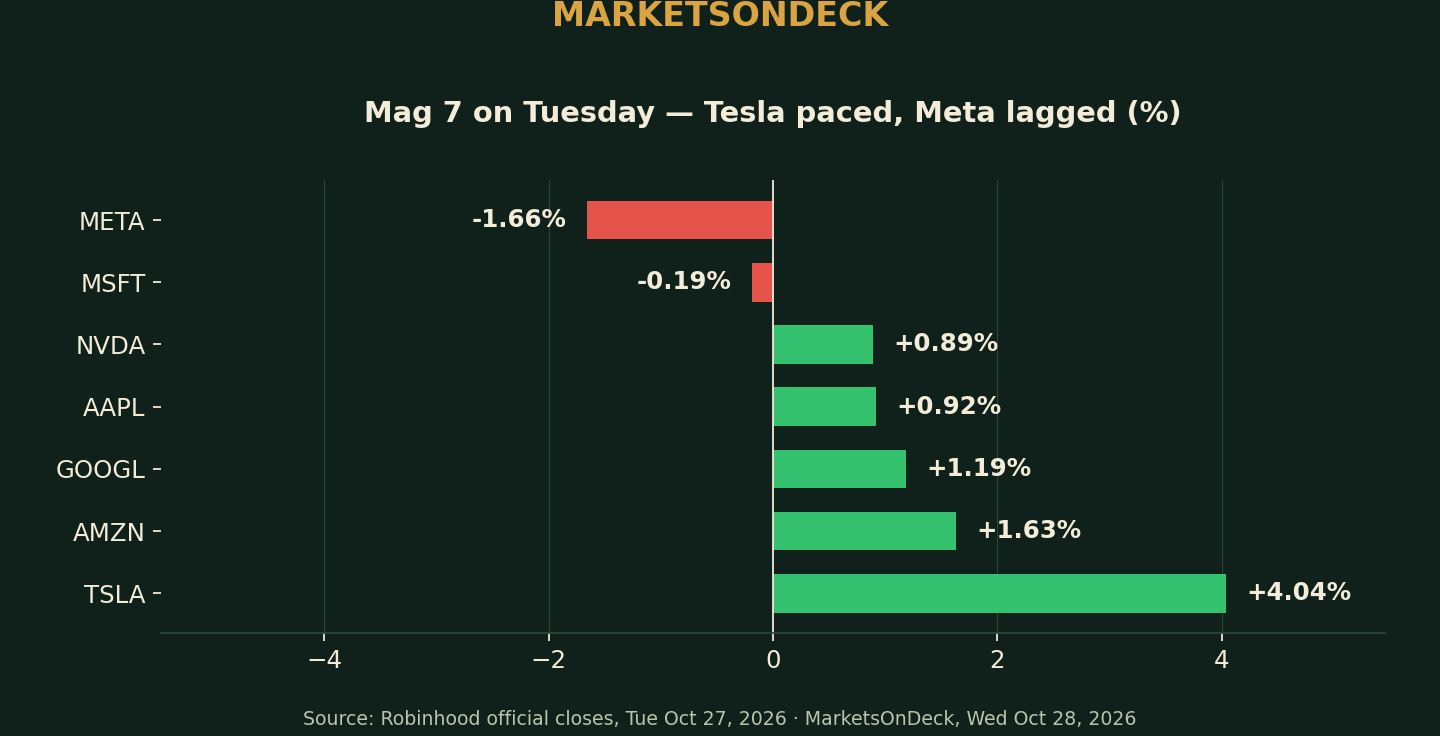
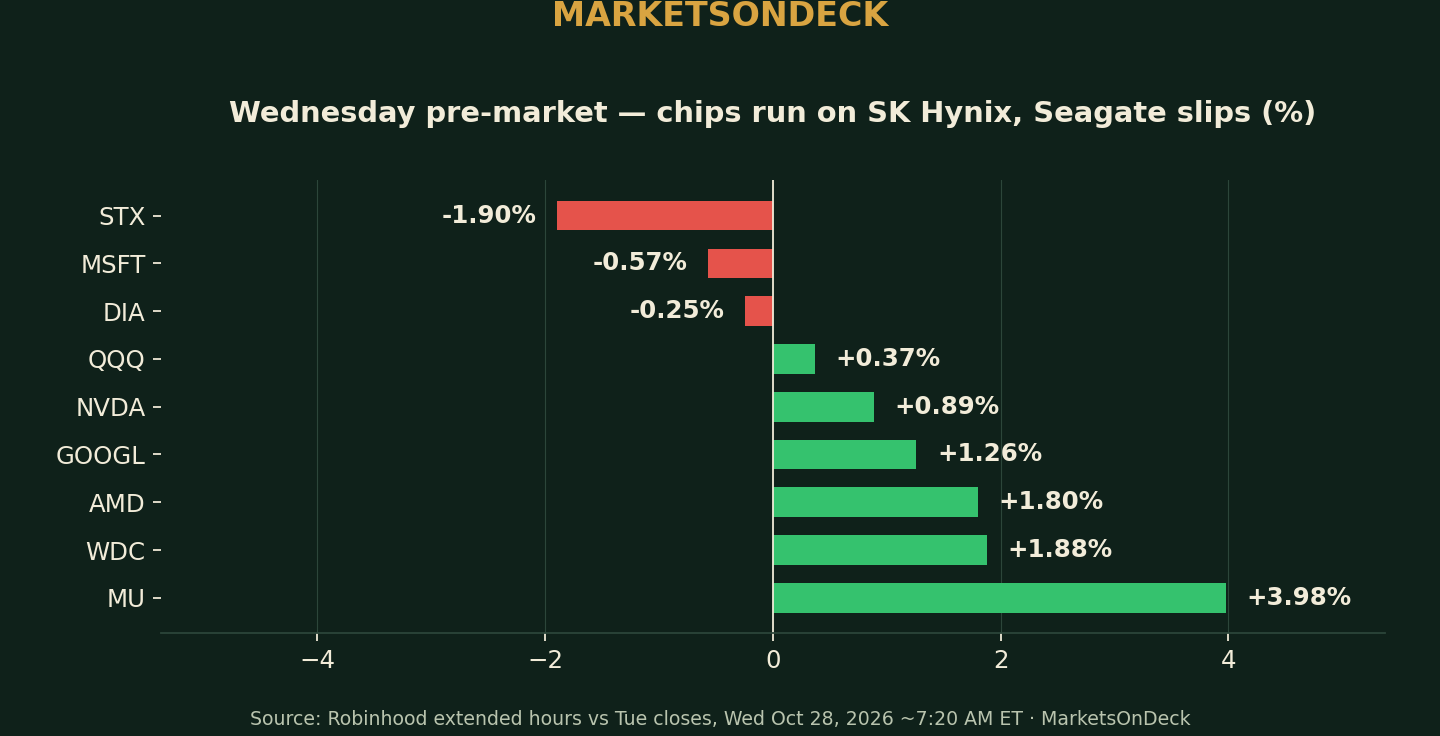
Why it moved. Tuesday’s Mag 7 (Robinhood official closes): Tesla $407.46 (+4.04%) paced the group again, Amazon $253.16 (+1.63%), Alphabet $320.56 (+1.19%), Apple $347.08 (+0.92%) and Nvidia $217.92 (+0.89%) followed, while Microsoft $531.60 (-0.19%) and Meta $620.12 (-1.66%) fell. Wednesday premarket is a chip story (Robinhood extended hours vs Tuesday’s closes): Micron $966.20 (+3.98%) after South Korean rival SK Hynix reported a more than sevenfold jump in quarterly profit — SK Hynix’s US-listed shares jumped 7.8% (Reuters) — with Western Digital +1.88% and AMD +1.80% alongside; Seagate is the outlier, -1.90% in extended hours after its first-quarter results (Reuters had it down 3.7% earlier in the premarket). Alphabet is up 1.26% in extended hours after a media report that OpenAI plans to buy Google’s AI chips (Reuters), Nvidia is up 0.89%, and Microsoft sits -0.57% ahead of its own print tonight. Tonight’s verdicts — Microsoft and Alphabet after the close, with accelerating cloud growth expected and capital-expenditure plans under the microscope (Reuters) — decide whether the AI spending boom gets another leg.
Wednesday’s earnings. Before the open, the beats stacked up (Robinhood earnings calendar): Vertiv $2.21 vs $1.82 estimated, GE Vernova $4.81 vs $4.02, Garmin $2.76 vs $2.38, Etsy $1.00 vs $0.76, Phillips 66 $14.08 vs $11.83 and ADP $2.82 vs $2.77; Lennox missed, $6.84 vs $7.32, and United Microelectronics missed, $0.206 vs $0.23. After the close Wednesday: Microsoft ($4.72 estimated), Alphabet ($2.99), KLA ($1.18), ServiceNow ($0.93), Fortinet ($0.84), Equinix ($9.28), eBay ($1.35), FedEx ($3.36), Chipotle ($0.29), Carvana ($0.44) and Ford ($0.40). Amazon follows Thursday after the close ($1.97 estimated), the same day US GDP and PCE inflation data land.
What to watch today. The Fed decides at 2:00 PM ET: a hold at 3.75%–4.00% is widely expected (about 90.6% odds on CME FedWatch, FXStreet), so Chair Kevin Warsh’s press conference — and any signal on December, where FXStreet notes pricing for a hike — is the real event (WSJ; FXStreet). Then whether the Nasdaq’s chip-led premarket gain (+0.41% at 4:53 AM ET, Reuters) survives the decision, and Microsoft and Alphabet after the close — with Amazon and GDP/PCE on Thursday.
The OnDeck Book
Trading day change +3.39% and Agentic +0.47% (Tuesday session, percent only, Robinhood) vs the S&P 500’s +0.60%, the Nasdaq Composite’s +1.18% and the Dow’s +0.03%; Wednesday premarket, extended-hours equity is +0.39% for Trading and -0.12% for Agentic vs Tuesday’s core close (this run’s Robinhood pulls). Positions (Tuesday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $148.59 (+1.15% on Tuesday), +12.46% vs avg cost, unrealized +$2,468.97 — $149.31 in extended hours Wednesday (+0.48%). SOFI 200 shares, avg $17.10, close $16.395 (+13.38%), -4.11% vs avg, unrealized -$140.50 — $16.525 in extended hours (+0.79%). QUBT 700 shares, avg $8.21, close $6.885 (+7.41%), -16.14% vs avg, unrealized -$927.50 — $6.97 in extended hours (+1.23%). Options (marks at Tuesday’s close, Robinhood; total option market value $4,819, matching the portfolio pull): SPCX $152.50 calls expiring TODAY, Wed Oct 28 — 6 long, clearing cost $1,038 total ($1.73 per share) vs a $0.52 mark, market value $312.00 — expiring today; NVDA $215 calls expiring Wed Nov 4 — 2 long, clearing cost $880 total ($4.40 per share) vs a $6.18 mark, market value $1,236.00; NVDA $217.50 calls expiring Wed Nov 4 — 2 long, clearing cost $934 total ($4.67 per share) vs a $4.70 mark, market value $940.00; SPCX $148 calls expiring Fri Nov 6 — 3 long, clearing cost $1,690 total ($5.63 per share) vs a $5.45 mark, market value $1,635.00; SPCX $152.50 calls expiring Fri Nov 6 — 2 long, clearing cost $800 total ($4.00 per share) vs a $3.48 mark, market value $696.00. The NVDA Oct 28 calls from Tuesday morning’s brief were closed on Tuesday (see Tuesday’s tape). Futures: none — fully closed Oct 22 (web-verified); API aggregate futures market value $0. Crypto: ETH 3.6 coins, clearing cost basis $8,608.00, mark $2,359.68 (Robinhood crypto quote, ~7:20 AM ET), indicative value $8,494.86; USDG 1.0 unit on the API spot line (total incl. Crypto Earn last web-verified Oct 15 at 102.88 units); dust: CC 1.0, DOGE 1.0, USDC 0.00993.
Account totals at the pull: total equity $63,277.71, core portfolio equity $54,563.82 (extended-hours equity $54,777.90), buying power $35,122.97, cash $19,357.82.
Drafted premarket Tuesday, October 27, before the opening bell, after Monday’s close.
Bitcoin Just Lost $80,000, S&P Futures Are Frozen at +0.05% — and Meta’s $97.5 Billion AI Raise Lands the Day Before the Fed Decides
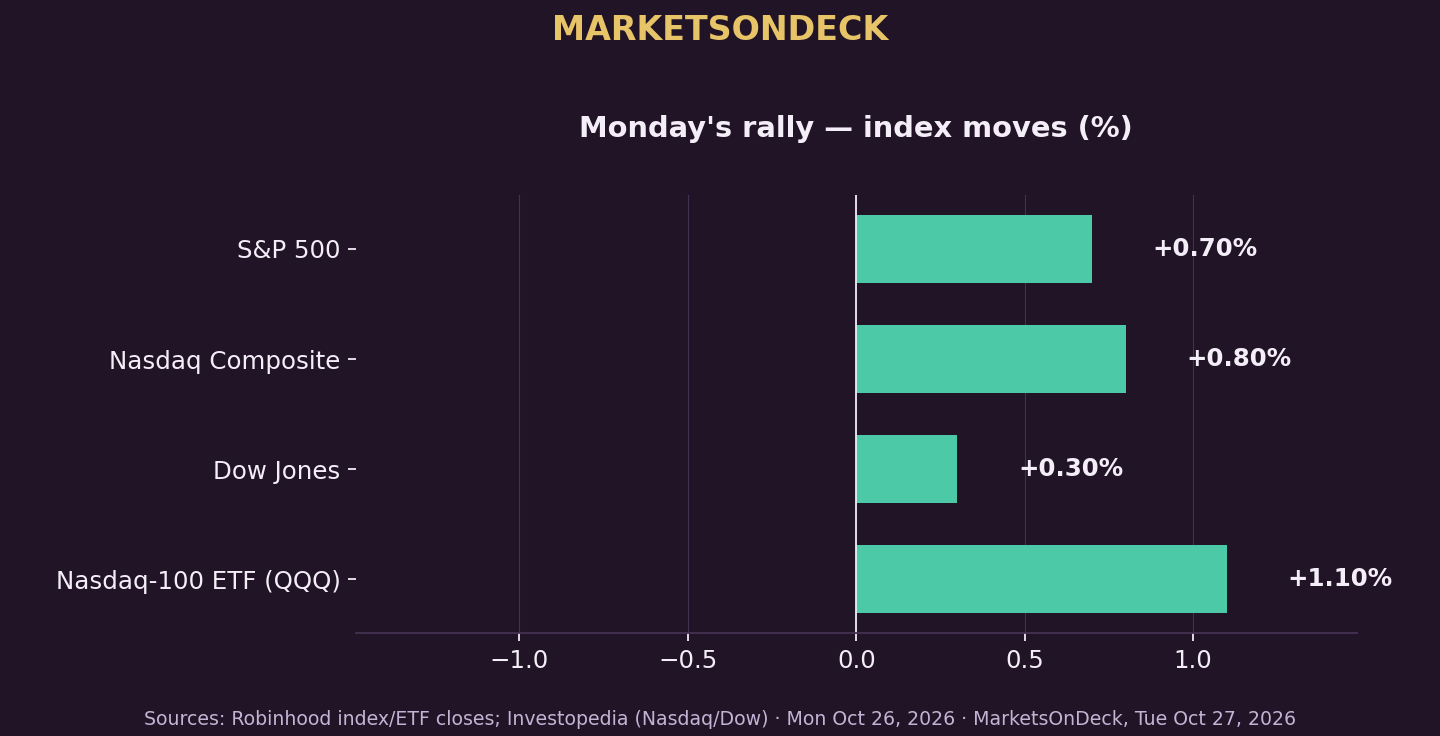
S&P 500 +0.7% · Nasdaq +0.8% · Dow +0.3% — Monday’s closes, percent only (Robinhood index quote; Investopedia).
Bitcoin’s Robinhood mark is $79,747.62 on Tuesday morning — back under $80,000 — S&P 500 futures were up just 0.05% at 5:17 AM ET, and nobody wants to move first: the Fed decides Wednesday, Alphabet and Microsoft report Wednesday, Amazon reports Thursday, and Meta just increased its largest-ever equity fundraising to $97.5 billion to fund AI expansion (Reuters).
The setup. Monday was a tech-led rally: the S&P 500 rose 0.70% to 7,676.77 (Robinhood index quote), the Nasdaq Composite rose 0.8% and the Dow rose 0.3% (Investopedia), with Robinhood’s ETF closes agreeing — SPY $765.29 (+0.70%), QQQ $712.12 (+1.10%) and DIA $522.97 (+0.31%). Anthropic’s public IPO filing helped lift AI-linked names on Monday (Investopedia; WSJ). Tuesday morning, that momentum is paused — at 5:17 AM ET, Dow E-minis were up 70 points (+0.14%), S&P 500 E-minis up 3.75 points (+0.05%) and Nasdaq 100 E-minis up 2 points (+0.01%) (Reuters). Crude oil was slightly higher, with Brent near its highest level since late April (Reuters). Crypto is not confirming any risk-on turn: Bitcoin’s mark was $79,747.62 early Tuesday — under the $80,000 line again — and Ether’s mark was $2,310.20. The VIX sat at 17.83 on Tuesday morning (Robinhood).
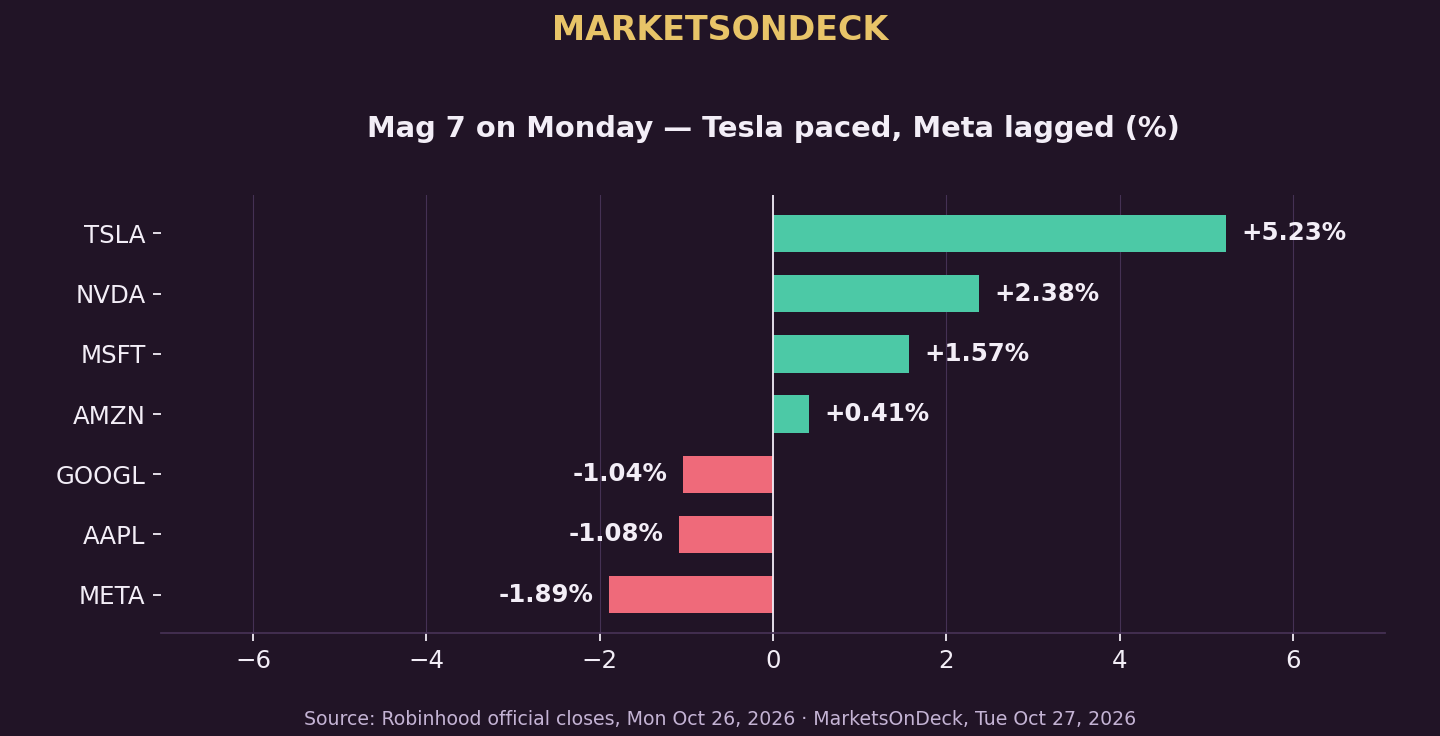
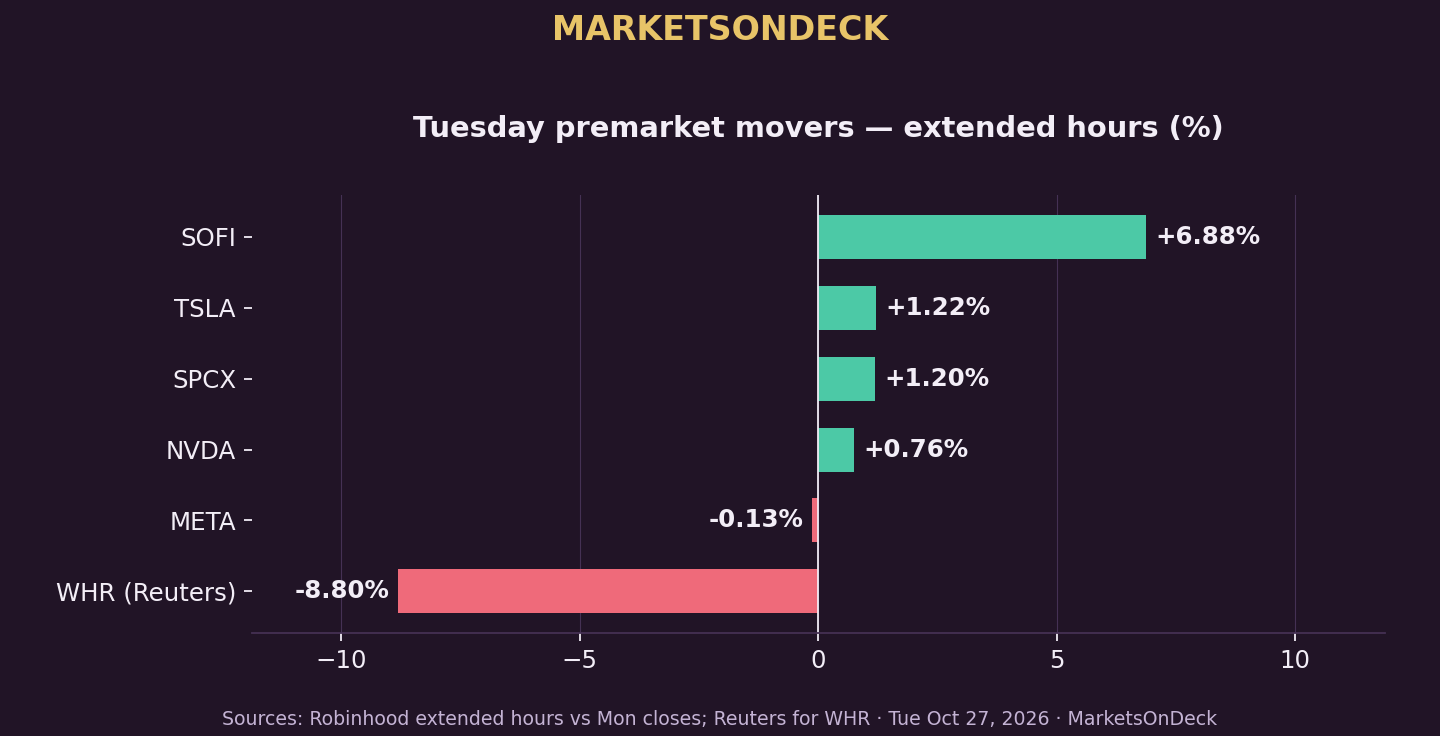
Why it moved. Monday’s Mag 7 split tells the story (Robinhood official closes): Tesla $391.69 (+5.23%) paced the group, with Nvidia $215.99 (+2.38%) and Microsoft $532.75 (+1.57%) behind it; Amazon $249.01 (+0.41%) edged up while Meta $630.47 (-1.89%), Apple $343.98 (-1.08%) and Alphabet $316.89 (-1.04%) fell. Tuesday premarket is a partial follow-through (Robinhood extended hours vs Monday’s closes): Tesla $396.46 (+1.22%) and Nvidia $217.63 (+0.76%), while Microsoft $529.40 (-0.63%), Apple $342.95 (-0.30%) and Meta $629.64 (-0.13%) sit red — Meta flat after increasing its largest-ever equity fundraising to $97.5 billion to fund AI expansion (Reuters), the day before the Fed decides and two of the hyperscalers report.
Tuesday’s earnings. Before the open, Coca-Cola beat ($0.91 vs $0.88 estimated), PayPal beat ($1.45 vs $1.31), UPS beat ($1.69 vs $1.63) and Corning beat ($0.91 vs $0.88); Sherwin-Williams missed ($3.63 vs $3.68) and Whirlpool dropped 8.8% premarket after a third-quarter loss and a revenue miss (Robinhood earnings calendar; Reuters). Boeing (estimated -$0.20) was still pending at pull time. After the close: Visa ($3.44 estimated), Robinhood ($0.56), Seagate ($7.36), F5 ($4.07) and Enphase ($0.44).
What to watch today. All session: whether the frozen futures (+0.14% / +0.05% / +0.01% at 5:17 AM ET, Reuters) break on Tuesday’s earnings digest, and whether Bitcoin reclaims $80,000. After the close: Visa and Robinhood report, in a week where 163 S&P 500 companies post third-quarter results (CoinCentral). Wednesday, October 28: the Federal Reserve’s rate decision (a hold at 3.75%–4.00% is widely expected, Reuters; about 90% odds per CME via CoinCentral), plus Alphabet and Microsoft earnings after the close; Amazon follows Thursday (Investopedia).
The OnDeck Book
Trading day change +2.75% and Agentic +0.58% (Monday session, Robinhood); Tuesday premarket extended-hours equity was +0.95% vs Monday's core close on this run's pull. Positions (Monday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $146.90 (-0.40%), +11.18% vs avg cost, unrealized +$2,215.47. SOFI 200 shares, avg $17.10, close $14.47 (-1.03%), -15.40% vs avg, unrealized -$526.50. QUBT 700 shares, avg $8.21, close $6.42 (-2.13%), -21.80% vs avg, unrealized -$1,253.00. Options (marks at Monday's close, Robinhood): SPCX $152.50 calls expiring Oct 28 — 11 long, clearing cost $1,960 total ($1.78 per share) vs a $0.70 mark, market value $770.00; NVDA $215 calls expiring Oct 28 — 5 long, clearing cost $935 total ($1.87 per share) vs a $3.08 mark, market value $1,540.00; NVDA $215 calls expiring Nov 4 — 2 long, clearing cost $880 total ($4.40 per share) vs a $5.53 mark, market value $1,106.00; SPCX $148 calls expiring Nov 6 — 2 long, clearing cost $1,100 total ($5.50 per share) vs a $5.00 mark, market value $1,000.00. Futures: none — fully closed Oct 22 (web-verified); API aggregate futures market value $0. Crypto: ETH 3.6 coins, clearing cost basis $8,608.00, mark $2,310.20 (Robinhood crypto quote, ~7:20 AM ET), indicative value $8,316.73; dust: DOGE 1.0, USDC 0.00993, CC 1.0.
Account totals at the pull: total equity $61,590.39, core portfolio equity $52,781.49 (extended-hours equity $53,280.32), buying power $34,546.97, cash $18,943.49.
Updated Oct 28 with verified figures.
Drafted premarket Monday, October 26, before the opening bell, after Friday’s close.
Oil Just Fell $7 From $116 — and Tesla Is Leading Futures Into the Biggest Earnings Week of the Year
S&P 500 -0.5% · Nasdaq -0.2% · Dow -1.2% — Friday’s closes (S&P 500 7,624, Nasdaq Composite 25,955, Dow 52,215). Index closes: NordFX morning update.
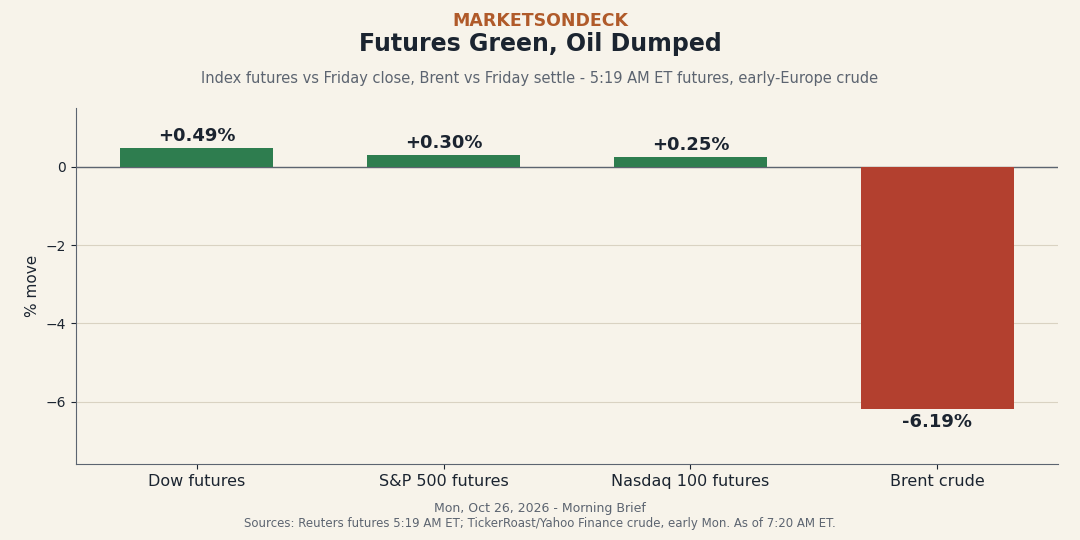
The setup. Friday was a controlled slide, not a rout: the S&P 500 fell 0.5% to 7,624, the Dow fell 1.2% to 52,215 and the Nasdaq Composite fell 0.2% to 25,955. Robinhood’s official ETF closes agree: SPY $759.85 (-0.54%), QQQ $704.39 (-0.01%), DIA $521.40 (-1.23%). The weekend changed the oil story — Brent had closed Friday at $116.72 after a weekly gain of more than 6%, then fell back toward $114.85 late Sunday and was trading near $109.50 early Monday in Europe, down about 6.2% from the settle, after President Trump said there would be no strike on Iran on Sunday (TickerRoast, citing Yahoo Finance). Futures followed the oil relief: at 5:19 AM ET, Dow futures were up 257 points (+0.49%), S&P 500 futures up 23.25 points (+0.30%) and Nasdaq 100 futures up 73 points (+0.25%) (Reuters). The 10-year Treasury yield slipped below 5%, to about 4.97% (TickerRoast).
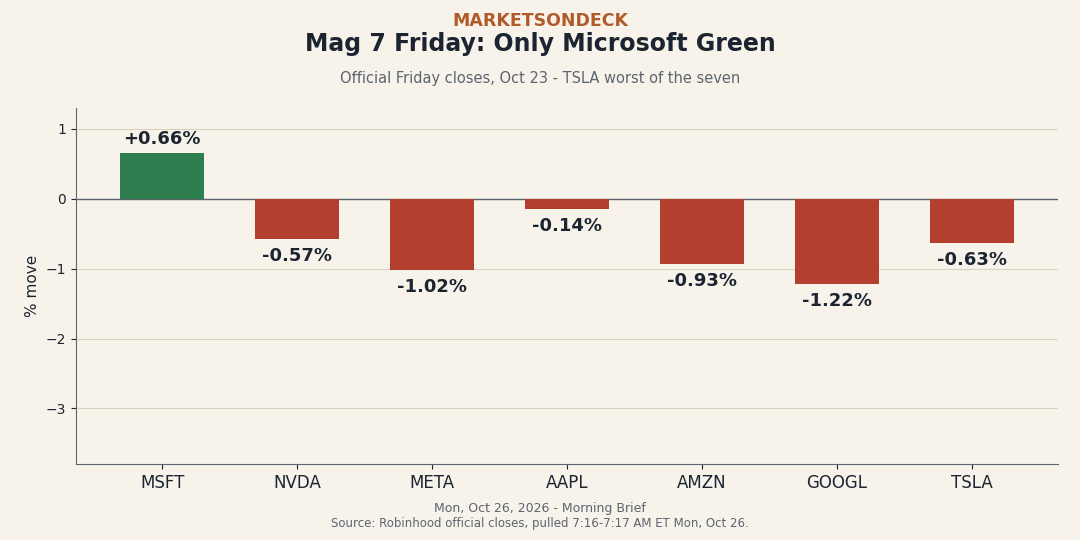
Why it moved. Oil was the switch, and the Mag 7 tells the story underneath it. Friday’s closes (Robinhood official closes): Microsoft $524.53 (+0.66%) was the group’s only green close; Nvidia $211.00 (-0.57%), Tesla $372.22 (-0.63%), Amazon $248.05 (-0.93%), Meta $642.26 (-1.02%), Alphabet $320.27 (-1.22%) and Apple $347.72 (-0.14%). Monday premarket, Tesla is leading the advance, up 2.1% (Reuters) — Robinhood extended hours put it at $379.00, +1.82% vs Friday’s close. The neoclouds are not bouncing: CoreWeave and Nebius fell around 3% premarket after losing more than 30% of their market value this month (Reuters). Crypto sat the relief out: Bitcoin’s mark was $80,167.16 and Ether’s $2,322.26 early Monday (Robinhood, 7:17 AM ET).
Monday’s earnings. Verizon beat before the open ($1.31 vs $1.27 estimated), Cemex beat ($0.28 vs $0.22) and Alliance Resource crushed it ($1.08 vs $0.82); Bank of Hawaii just missed ($1.49 vs $1.51) (Robinhood earnings calendar). After the close: Cadence Design Systems ($1.96 estimated), Nucor ($5.80), Welltower ($0.90), Public Storage ($4.27) and Hartford ($3.17).
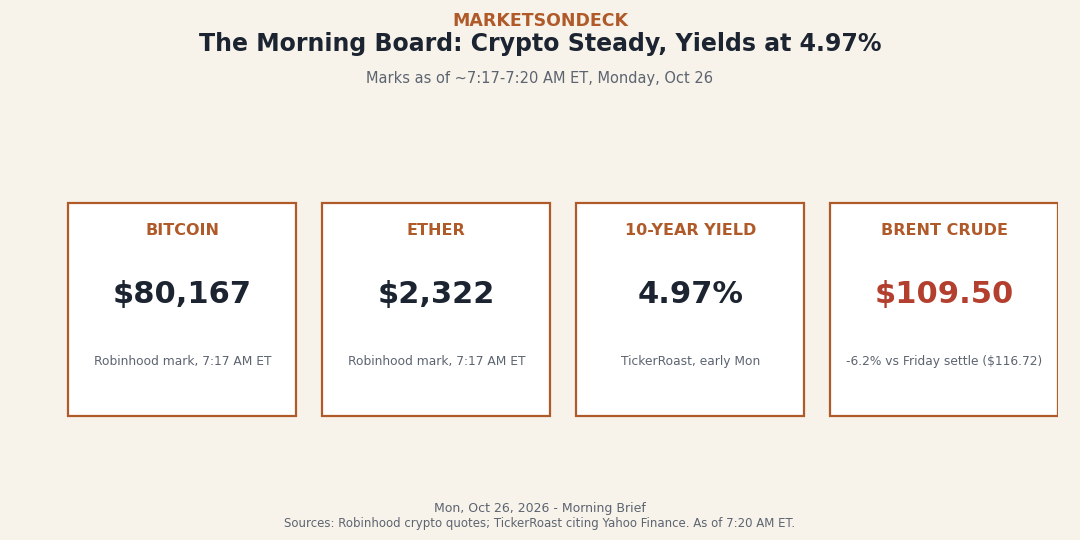
What to watch today. All session: whether Brent holds near $109.50 after Friday’s $116.72 close, and whether the Dow futures’ +0.49% premarket gain holds the cash open. After the close: Cadence Design Systems and Nucor report, the first prints of a week where about one-third of the S&P 500 reports (Reuters). Wednesday, October 28: the Federal Reserve’s rate decision, plus Alphabet and Microsoft earnings after the close; Amazon follows Thursday (Reuters; MarketChameleon).
The OnDeck Book
Trading day change -1.37% and Agentic -0.72% (Friday session, Robinhood). Positions (Friday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $147.50 (+1.90%), +11.63% vs avg cost, unrealized +$2,304.72. SOFI 200 shares, avg $17.10, close $14.62 (-1.05%), -14.52% vs avg, unrealized -$496.50. QUBT 700 shares, avg $8.21, close $6.56 (-0.53%), -20.16% vs avg, unrealized -$1,158.50. Options (marks at Friday's close, Robinhood): SPCX $152.50 calls expiring Oct 28 — 11 long, clearing cost $1,960 total ($1.78 per share) vs a $1.53 mark, market value $1,683.00; NVDA $215 calls expiring Oct 28 — 20 long, clearing cost $5,380 total ($2.69 per share) vs a $1.89 mark, market value $3,780.00; NVDA $215 calls expiring Nov 4 — 2 long, clearing cost $880 total ($4.40 per share) vs a $3.90 mark, market value $780.00; SPCX $148 calls expiring Nov 6 — 2 long, clearing cost $1,100 total ($5.50 per share) vs a $5.98 mark, market value $1,196.00. Futures: none — fully closed Oct 22 (web-verified); API aggregate futures market value $0. Crypto: ETH 3.6 coins, clearing cost basis $8,608.00, mark $2,322.26 (Robinhood crypto quote, ~7:20 AM ET), indicative value $8,360.14 — the position rose from 1.6 coins over the weekend (added cost basis $4,691.02, matching the cash drop vs Friday's tape pull); dust: DOGE 1.0, USDC 0.00993, CC 1.0.
Account totals at the pull: total equity $59,722.26, core portfolio equity $51,363.96 vs a $51,297.42 adjusted prior close (Monday premarket change +$66.54, +0.13%, transfer-adjusted), buying power $29,944.47, cash $14,289.21.
Updated Oct 28 with verified figures.
Drafted premarket Friday, October 23, before the opening bell, after Thursday’s close.
Meta Beat Earnings and Still Lost 7% — the Nasdaq’s Worst Day Since June Meets Brent at $114
S&P 500 -1.21% · Nasdaq -2.60% · Dow +0.02% — Thursday’s official closes (S&P 500 7,663.43, Nasdaq Composite 26,008.86). Index closes: TipRanks; Seoul Economic Daily, Oct 22.
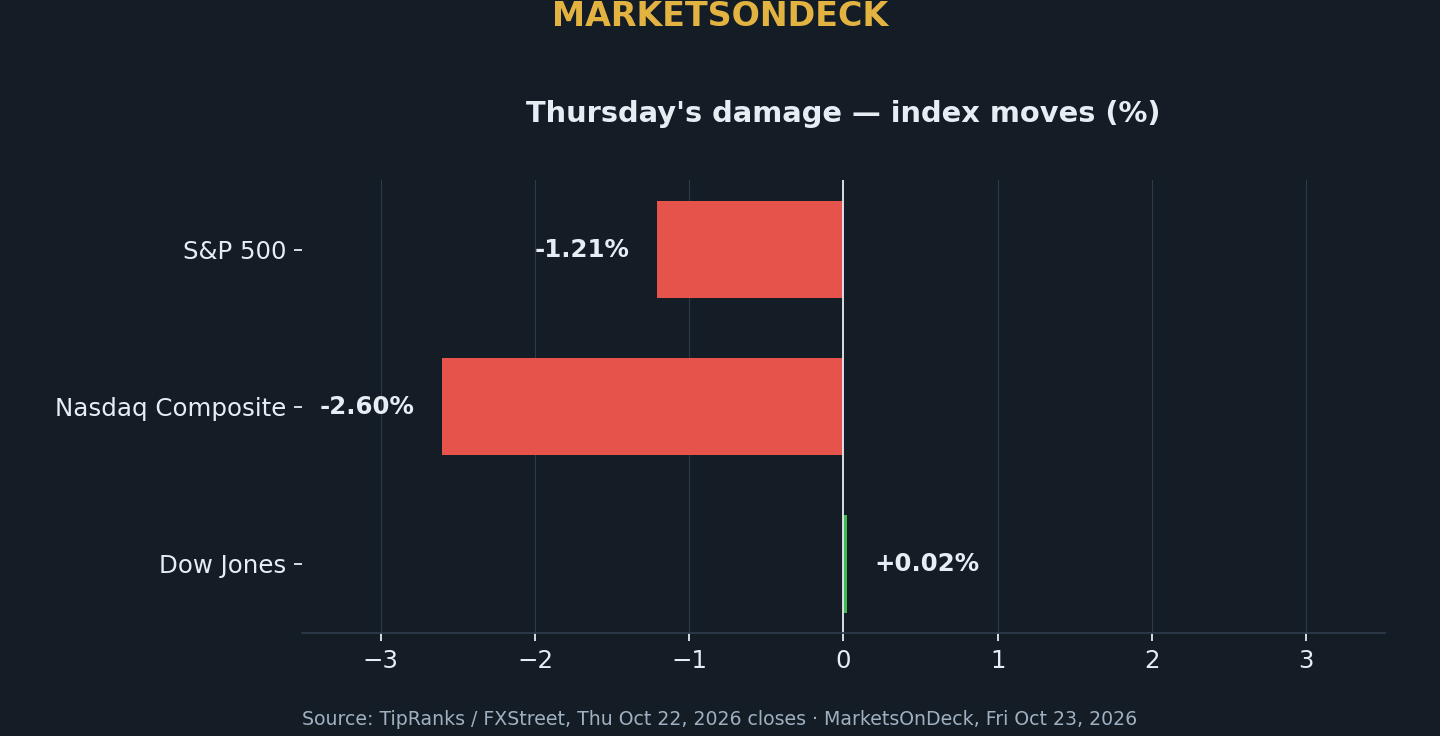
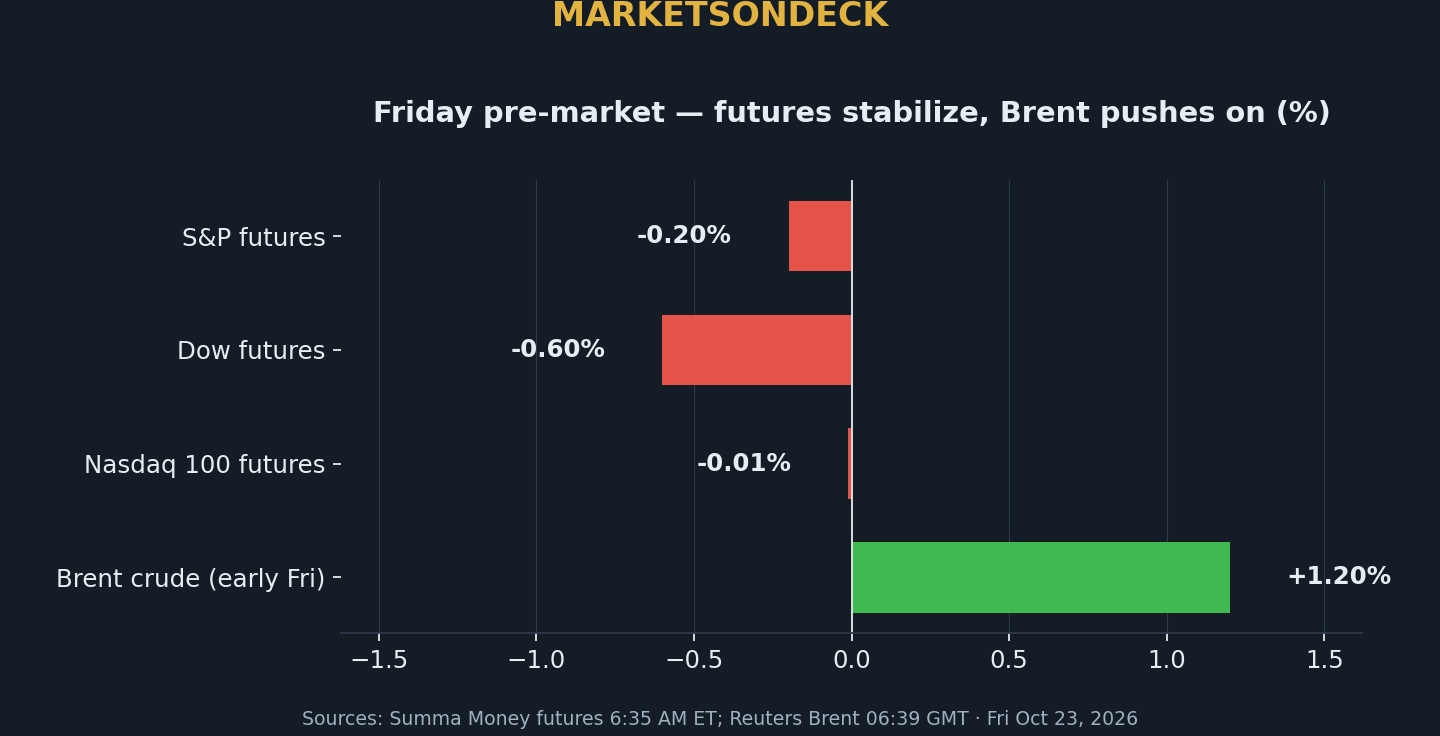
The setup — the AI bill coming due. The Nasdaq Composite fell 2.60% to 26,008.86 — its worst day since June — and the S&P 500 fell 1.21% to 7,663.43, its biggest daily loss since July, while the Dow edged up 0.02%. The trigger was not bad earnings: Meta beat and still fell, leaving capex guidance unchanged with little color on future plans, and Tesla cut its full-year capex guide by 20% — flipping the fear from “spending too much” to “the AI investment boom may have peaked” (TheStreet, quoting Capital.com’s Kyle Rodda). Friday futures are trying to stabilize: at 6:35 AM ET, S&P 500 futures were 7,688 (-0.2%), Dow futures 52,749 (-0.6%) and Nasdaq 100 futures 29,139 (-0.01%) (Summa Money). Robinhood extended hours at ~7:17 AM ET agree: SPY $762.14 (-0.24%), QQQ $703.99 (-0.09%), DIA $524.91 (-0.56%). Investors hid in Treasurys on Thursday — the 10-year yield dropped 18.5 basis points to 4.961% (TipRanks).
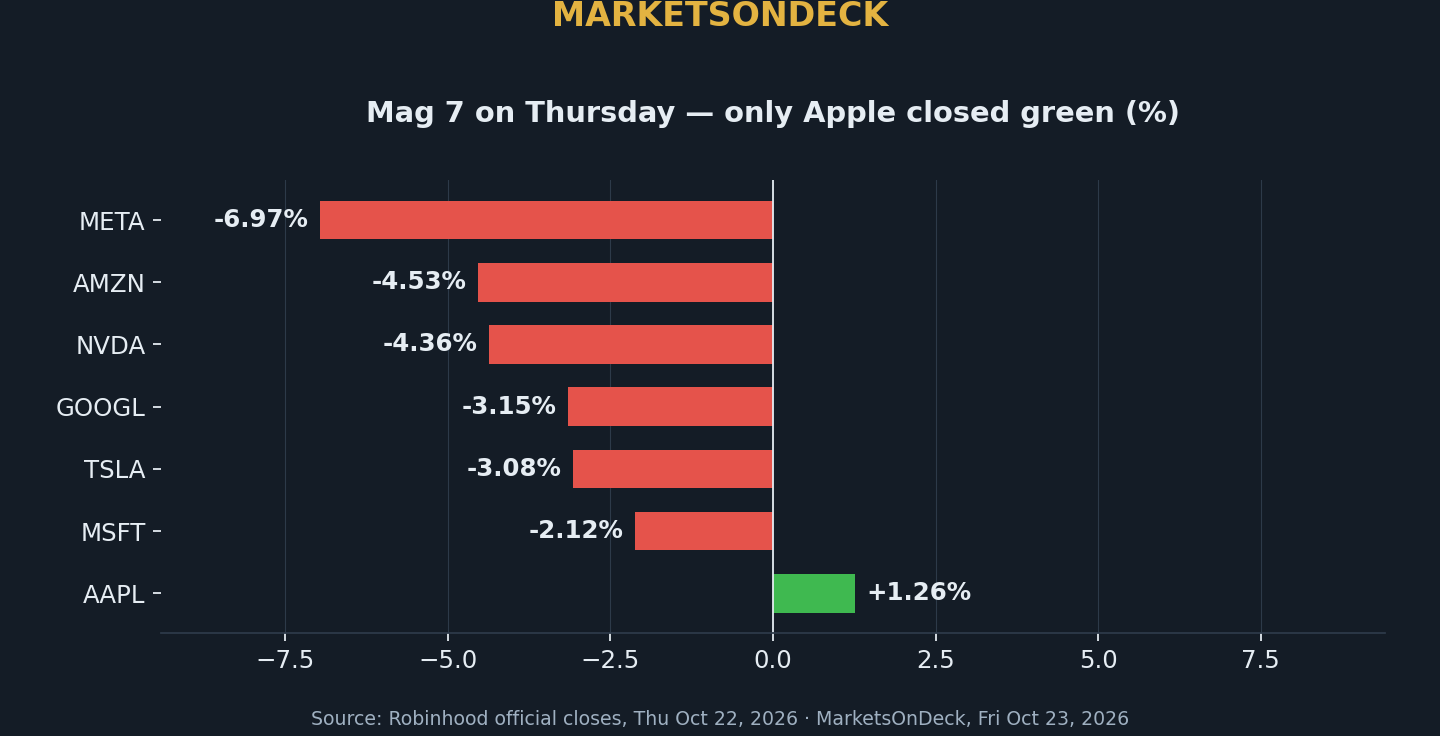
The Mag 7 — only Apple closed green. At Thursday’s official closes (Robinhood): Meta $648.87 (-6.97%), Amazon $250.48 (-4.53%), Nvidia $212.29 (-4.36%), Alphabet $324.22 (-3.15%), Tesla $374.57 (-3.08%), Microsoft $521.64 (-2.12%) — and Apple $348.32 (+1.26%), the group’s only green close. The Philadelphia semiconductor index fell 6.72%, its worst day since June, and CoreWeave fell 10.06% to its lowest since May 2025 (FXStreet, citing Deutsche Bank). In Friday extended hours (~7:17 AM ET), Nvidia $212.91 (+0.29%) and Tesla $375.15 (+0.15%) are inching back while Meta $645.40 (-0.53%) and Microsoft $518.70 (-0.56%) are still leaking — stabilization, not a bounce.
Oil — the second front. Brent settled Thursday at $113.17, up 4.0% — its highest close since May 4 — after Houthi attacks on Saudi Arabia, and climbed another 1.2% to $114.47 early Friday (Reuters). WTI settled at $99.47 (+2.4%). Crypto went risk-off with equities: Bitcoin mark $81,522.82 and Ether mark $2,394.25 (Robinhood crypto quotes, ~7:17 AM ET), down 2.8% and 2.6% over 24 hours (CoinGecko via CoinStats).
This morning’s earnings. American Express beat ($4.68 vs $4.49 estimated), SLB beat ($0.64 vs $0.62), Booz Allen Hamilton beat ($1.76 vs $1.47) and First Citizens crushed it ($55.37 vs $46.11); Infosys missed ($0.20 vs $0.21) (Robinhood earnings calendar, Oct 23).
What to watch today:
- Fri Oct 23, 9:45 AM ET — flash manufacturing PMI
- Later this morning — final University of Michigan consumer sentiment reading
- All session — whether QQQ holds Thursday’s $704.59 close area after the cash open, and whether Brent over $114 turns a tech story into an inflation story
The OnDeck Book
Positions (Thursday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $144.75 (-9.14% on the day), +9.55% vs avg cost, unrealized +$1,892.22. SOFI 200 shares, avg $17.10, close $14.78 (-0.81%), -13.55% vs avg, unrealized -$463.50. QUBT 700 shares, avg $8.21, close $6.60 (-3.30%), -19.67% vs avg, unrealized -$1,130.50. HD was sold out Thursday (see Thursday's tape). Options (marks at Thursday's close, Robinhood): SPCX $152.50 calls expiring Oct 28 — 16 long, clearing cost $3,345 total ($2.09 per share) vs a $1.65 mark, market value $2,640.00; NVDA $215 calls expiring Oct 28 — 10 long, clearing cost $3,345 total ($3.35 per share) vs a $3.01 mark, market value $3,010.00; SPCX $148 calls expiring Nov 6 — 2 long, clearing cost $1,100 total ($5.50 per share) vs a $5.45 mark, market value $1,090.00. Futures: none — the /METV26 position was fully closed Thursday (web-verified on robinhood.com, 2026-10-22); API aggregate futures market value $0. Crypto: ETH 1.6 coins, clearing cost basis $3,916.98, mark $2,394.25 (Robinhood crypto quote, ~7:17 AM ET), indicative value $3,830.80; USDG 102.881882 units total including Crypto Earn (web holdings verification, 2026-10-15); dust: DOGE 1.0, USDC 0.00993.
Account totals at the pull: total equity $60,937.47, core portfolio equity $56,840.19 vs a $57,671.33 adjusted prior close (day change -$831.14, -1.44%), buying power $36,480.93, cash $20,815.94. Agentic day change 0.00% (Robinhood).
Updated Oct 28 with verified figures.
Drafted premarket Thursday, October 22, before the opening bell, after Wednesday’s close.
Nasdaq Futures Tumble 1.93% as Tesla Slides and Brent Hits $112 — the AI Bill Comes Due
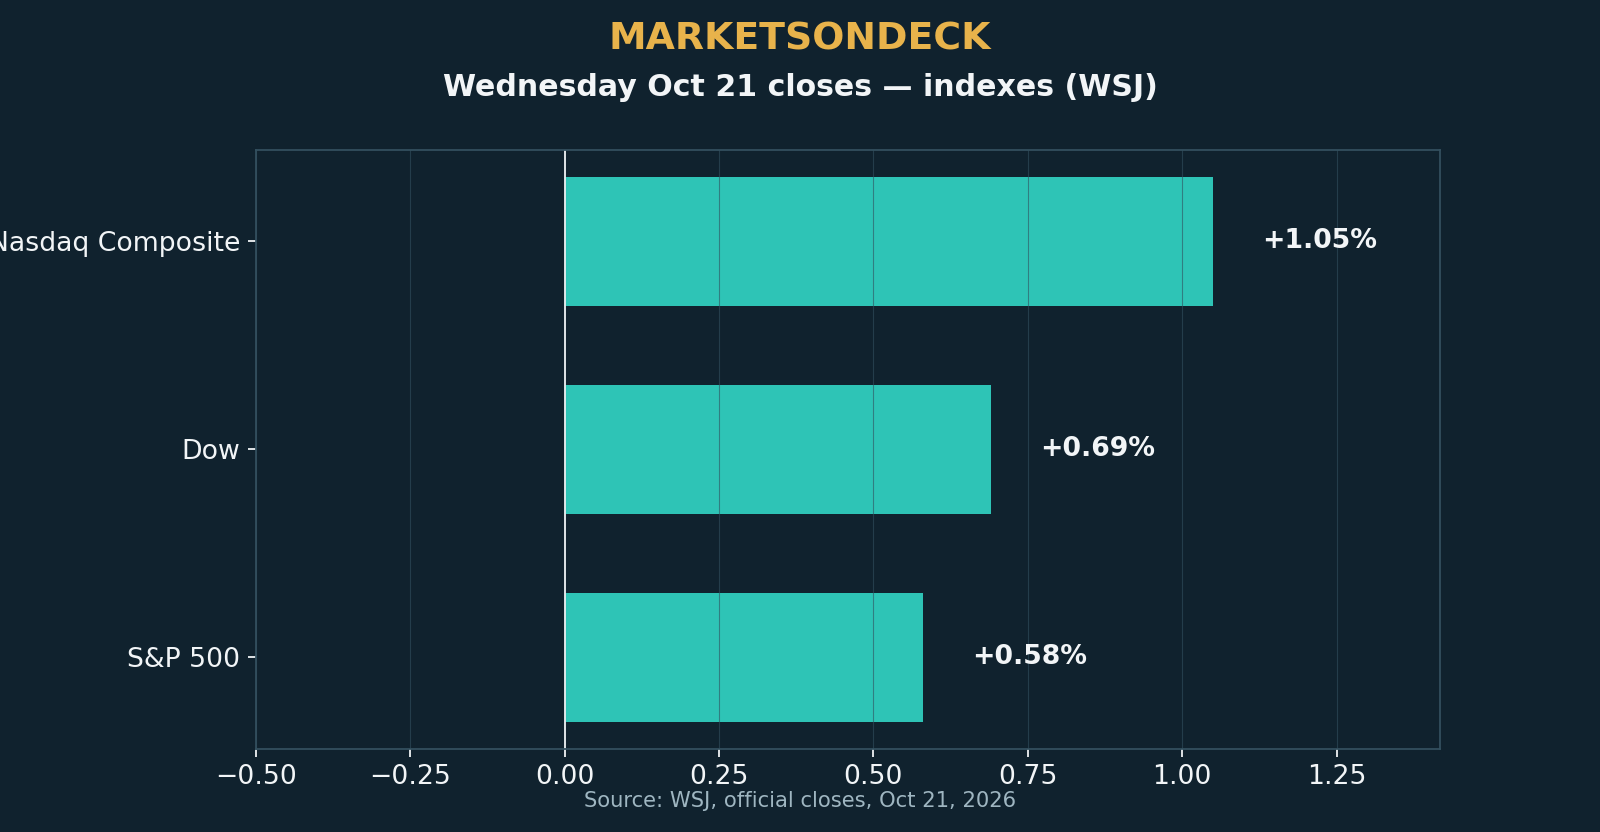
S&P 500 -1.10% · Nasdaq 100 -1.93% · Dow -0.69% — overnight futures vs Wednesday's closes (S&P 500 7,757.17, Nasdaq Composite 26,702.86, Dow 52,856.09). Percents: Reuters futures, 4:56 AM ET; index closes: WSJ, Oct 21.
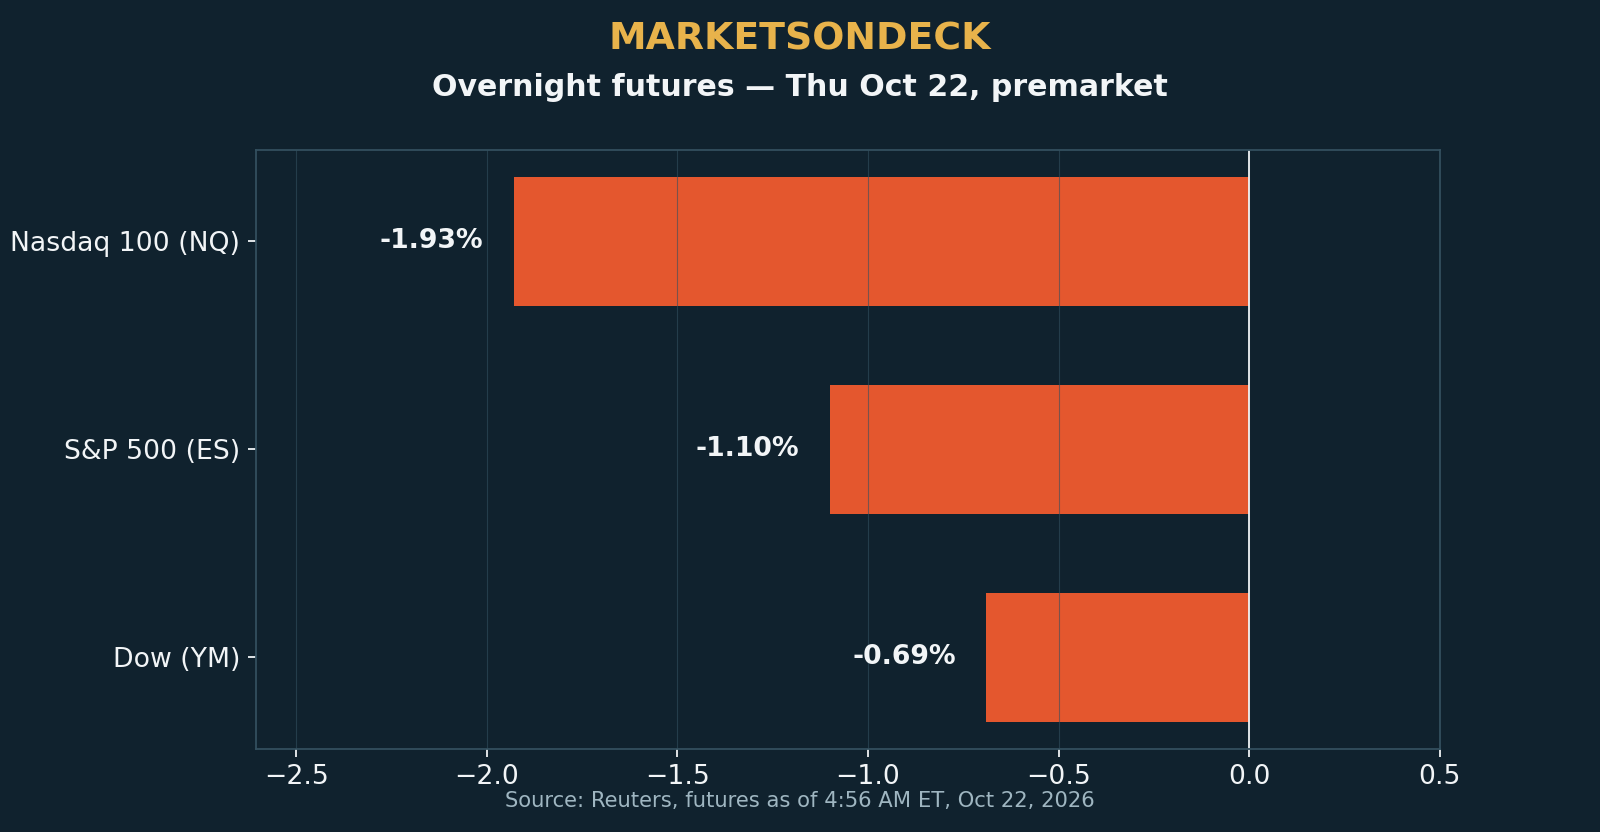
The setup — beats were not enough. Meta topped estimates on $64.60 billion of revenue and Tesla beat on both lines — $0.48 adjusted EPS vs $0.43 expected, $28.05 billion of revenue vs $27.88 billion expected (LSEG via CNBC) — and futures still rolled over. Meta created a new class of non-voting shares to help fund its AI push, and Tesla's GAAP net income fell 43% to $787 million (Reuters; Morningstar/Dow Jones Newswires). The question flipped overnight from what AI earns to what AI costs.
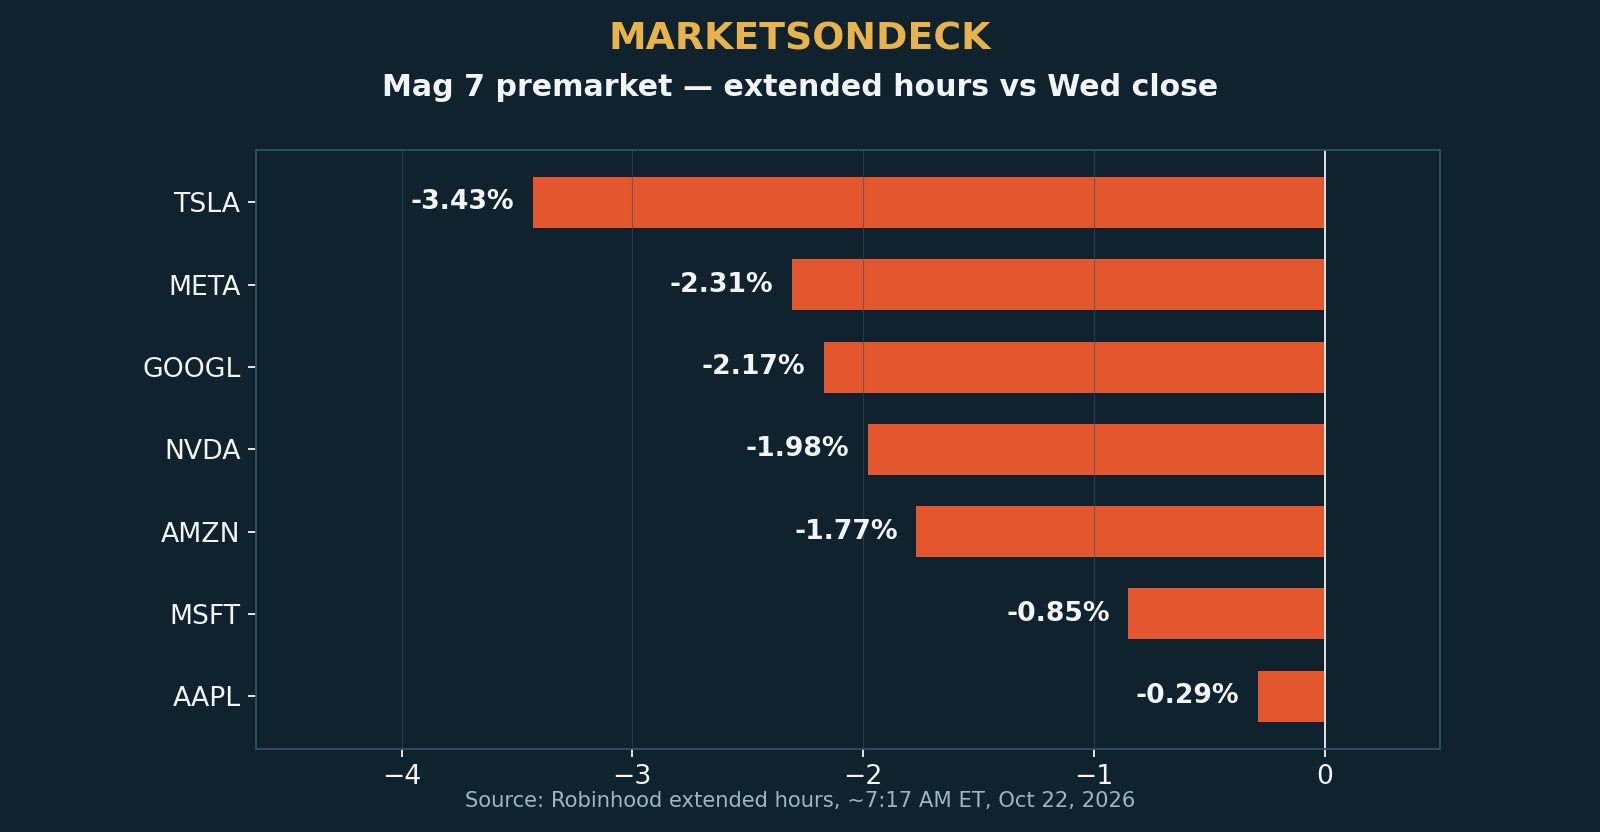
The Mag 7 — every name red before the bell. In Robinhood extended hours (~7:17 AM ET), Tesla traded $373.30 (-3.43%) vs its $386.56 close, Meta $682.29 (-2.31%), Alphabet $327.41 (-2.17%), Nvidia $217.47 (-1.98%), Amazon $257.71 (-1.77%), Microsoft $528.30 (-0.85%) and Apple $343.05 (-0.29%). Chips led the slide: Lam Research -7.31% in extended hours after soft guidance, and SpaceX $155.89 (-2.13%) a day after its first profit as a public company.
Oil — the second headline. Brent crude climbed more than 3% to $112 a barrel, near a five-month high, after Houthi attacks in Saudi Arabia stoked supply fears (Reuters). A flight to safety pulled the 10-year Treasury yield down to around 5.085% (Reuters). Crypto went risk-off with it: Bitcoin $81,881.83 (-1.18%) vs its session open and Ether $2,401.15 (-1.70%) (Robinhood crypto quotes, ~7:17 AM ET).
Earnings — defense and staples carried the morning. Lockheed Martin beat ($7.97 vs $7.51 estimated), Valero crushed it ($23.90 vs $21.20), Procter & Gamble beat ($2.00 vs $1.89), Honeywell beat ($2.27 vs $2.17) and American Airlines lost less than feared (-$0.28 vs -$0.35); Spotify missed ($2.85 vs $3.11) (Robinhood earnings calendar, Oct 22).
What to watch today:
- Thu Oct 22, 8:30 AM ET — initial jobless claims (consensus 200K, prior 199K)
- Thu Oct 22, after the close — Western Digital, Newmont and Deckers report
- All session — whether Brent holds over $112 and turns a tech story into an inflation story
The OnDeck Book
Trading day change +8.90% and Agentic +0.01% (Wednesday session, Robinhood). Positions (Wednesday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $159.28 (+7.77% on the day), +20.55% vs avg cost, unrealized +$4,072.47. HD 30 shares, avg $293.92, close $314.08 (-0.33%), +6.86% vs avg, unrealized +$604.85. SOFI 200 shares, avg $17.10, close $14.91 (+1.53%), -12.82% vs avg, unrealized -$438.50. QUBT 700 shares, avg $8.21, close $6.83 (+5.08%), -16.81% vs avg, unrealized -$966.00. Options (marks at Wednesday's close, Robinhood): SPCX $152.50 calls expiring Oct 28 — 1 long, clearing cost $4.65 per share ($465 total) vs an $8.83 mark, market value $883.00. Futures: API aggregate futures market value $3,285.50 (the /METV26 position was still open at this pull). Crypto: ETH 1.6 coins, clearing cost basis $3,916.98, mark $2,401.15 (Robinhood crypto quote, ~7:17 AM ET), indicative value $3,841.84; USDG 102.881882 units total including Crypto Earn (web holdings verification, 2026-10-15; the API spot line shows only 1.0 unit); dust: DOGE 1.0, USDC 0.00993.
Account totals at the pull: total equity $60,185.97, core portfolio equity $57,691.78 vs a $52,978.04 adjusted prior close (day change +$4,713.74), buying power $35,651.73, cash $15,114.38.
Updated Oct 28 with verified figures.
Drafted premarket Wednesday, October 21, before the opening bell, after Tuesday’s close.
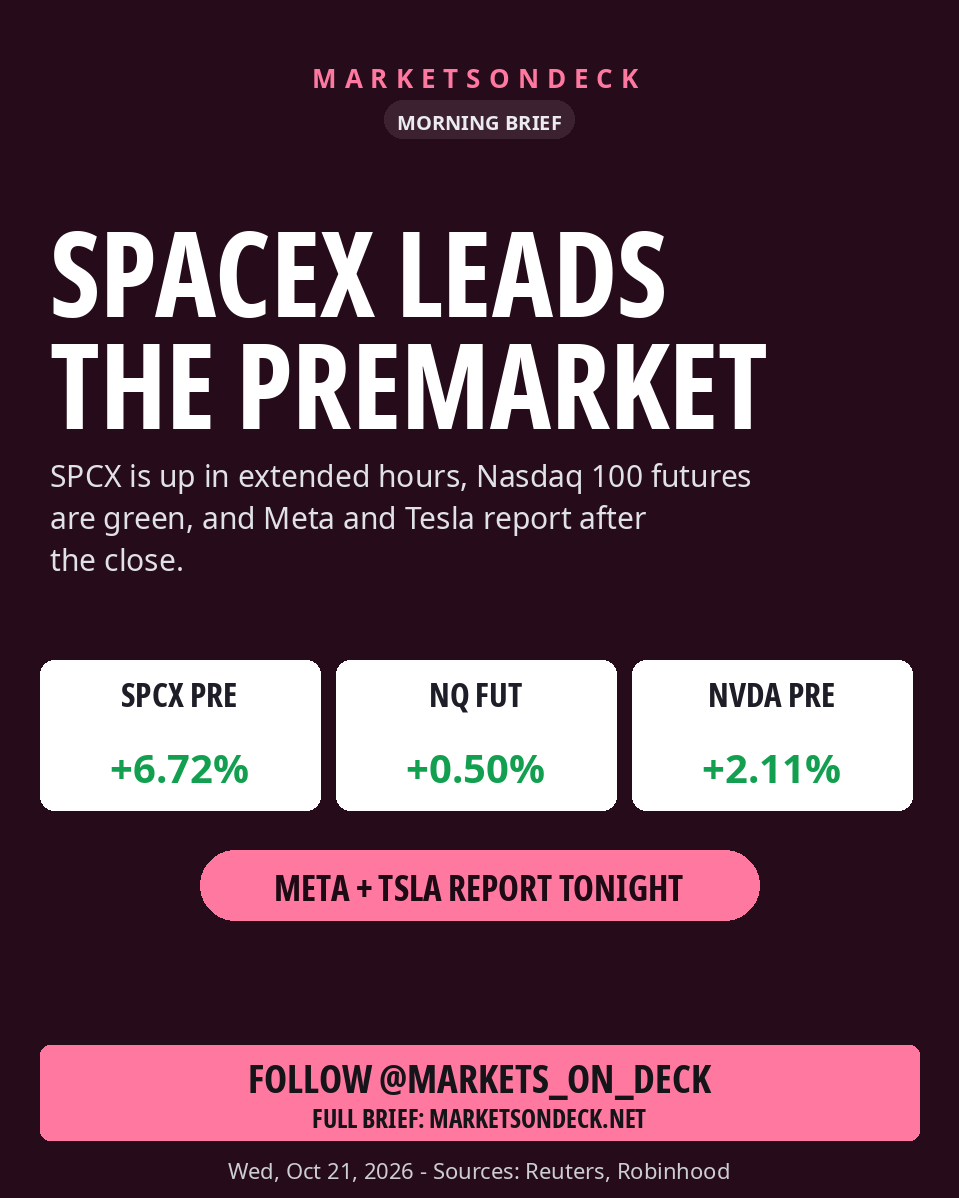
SpaceX Revenue Explodes 161% — and Nasdaq Futures Are Riding It Into a Meta-Tesla Earnings Night
SpaceX just reported third-quarter revenue up 161% year over year to $14.58 billion, its stock is up 6.7% before the bell, and Nasdaq futures are green — hours before Meta and Tesla report after the close.
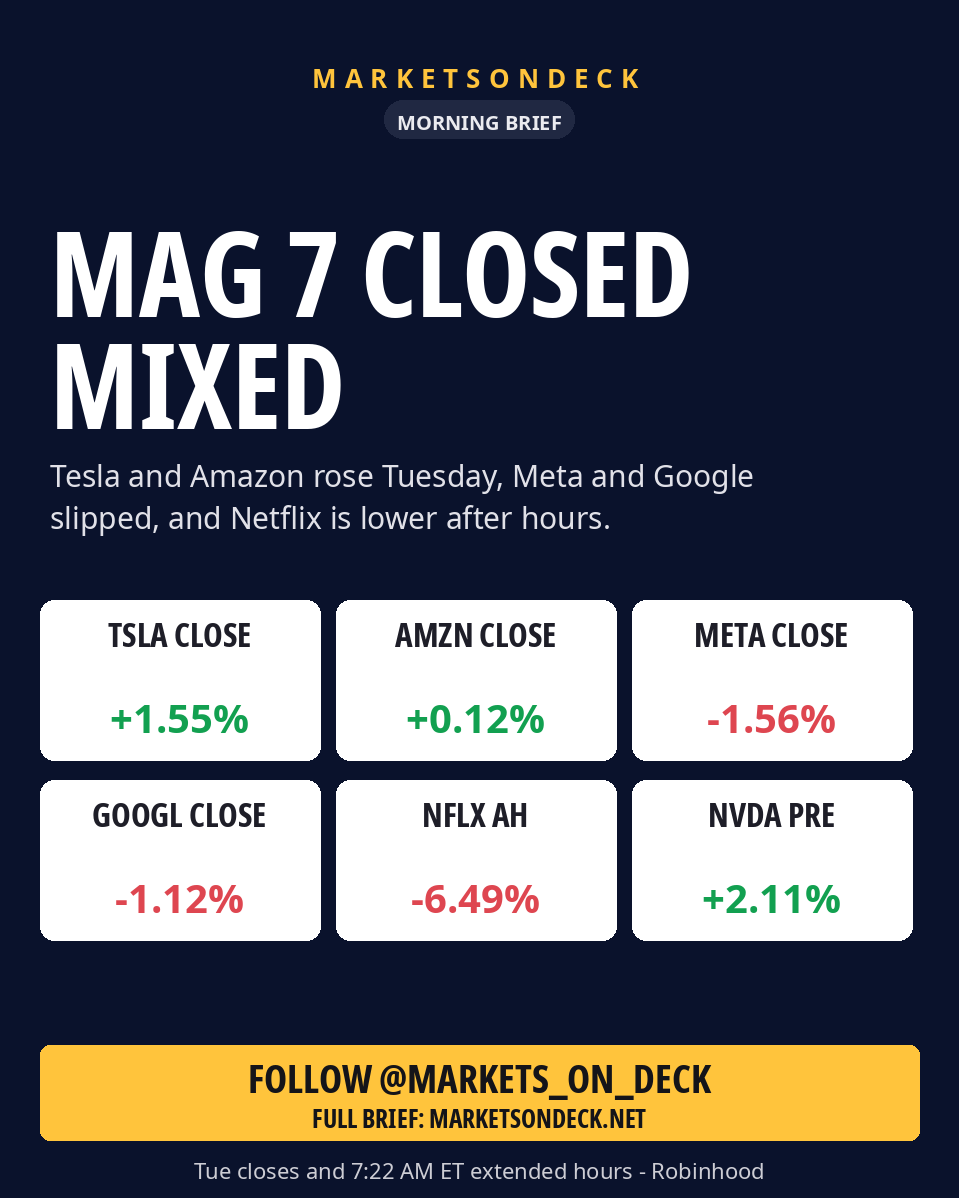
SpaceX just rewrote the morning. The company reported third-quarter revenue of $14.58 billion, up 161% year over year (FXStreet, Oct 21), and SPCX is trading $157.89 in Robinhood extended hours at ~7:22 AM ET — up 6.7% from Tuesday's $147.95 official close. Futures followed the AI complex higher: at 5:42 AM ET (Reuters) Nasdaq 100 e-minis were up 0.50%, S&P 500 e-minis up 0.24% and Dow e-minis up 0.07%. Super Micro's strong preliminary results (up over 13% premarket, FXStreet) pulled the chip trade with it — NVDA is $221.05 in extended hours, +2.1% vs its $216.48 close, with Intel +2.3% and AMD +1.8% premarket (Reuters). The offset is Netflix: NFLX is $64.21 after hours, -6.5% vs its $68.67 close, after a softer fourth-quarter outlook (Reuters; Robinhood extended-hours print). Tuesday's official closes are the bar: S&P 500 7,712.57 (+0.28%), Nasdaq Composite 26,424.82 (-0.02%), Dow 52,495.88 (+1.02%) (WSJ), Nasdaq-100 29,490.28 (Robinhood index quote), VIX 17.32 this morning. The Mag 7 closed mixed Tuesday — TSLA $373.78 (+1.55%) and AMZN $262.76 (+0.12%) up; META $694.44 (-1.56%), GOOGL $340.32 (-1.12%), AAPL $339.73 (-0.94%), MSFT $532.13 (-0.26%) and NVDA $216.48 (-0.28%) down (Robinhood official closes). Brent crude is still over $110 a barrel, near a five-month high (Reuters), and the Fed meets next week with CME FedWatch pricing an 85% chance of a hold (FXStreet). Crypto is bid with risk: BTC mark $83,309.50 (+0.80% vs its session open) and ETH mark $2,460.24 (+0.75%), Robinhood crypto quotes at ~7:21 AM ET.
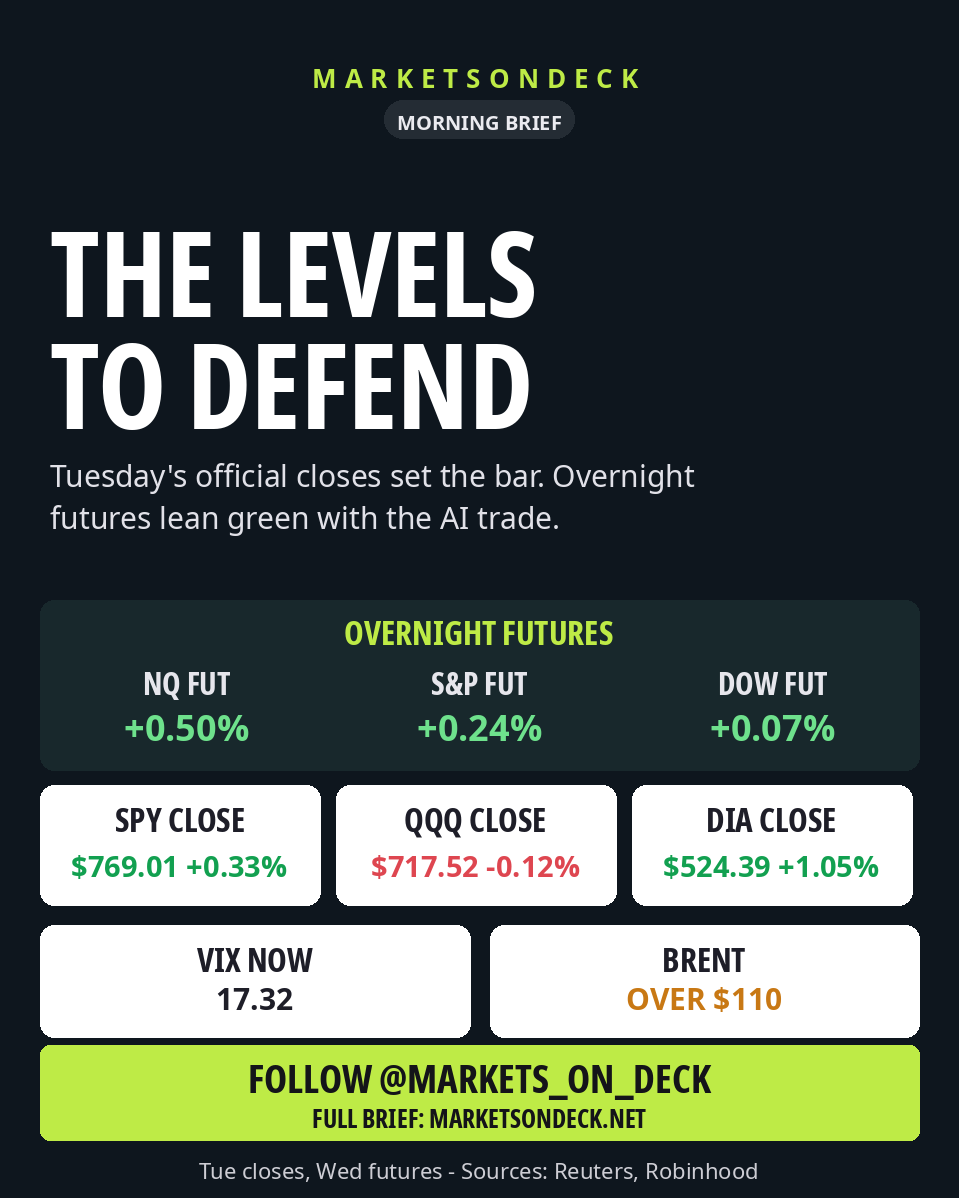
The pre-open earnings slate is a clean sweep of beats so far (Robinhood earnings calendar, Oct 21): AT&T (T) $0.65 vs a $0.60 estimate, Thermo Fisher (TMO) $6.68 vs $6.40, Danaher (DHR) $2.11 vs $1.92 and Philip Morris (PM) $2.37 vs $2.31; Abbott (ABT), estimate $1.42, also reports this morning. The day is decided after the close: Meta (META, estimate $5.74) and Tesla (TSLA, estimate $0.40) headline, with IBM ($2.87) and Texas Instruments ($2.42) also reporting (Robinhood earnings calendar). Levels that matter: SPCX's $157.89 premarket print vs its $147.95 close, NVDA's $221.05 premarket vs $216.48, and the S&P 500 defending 7,712 with Brent above $110. Watch today: whether SPCX holds its premarket gain into the close, the 10-year yield with oil above $110, and Meta and Tesla after the bell — the two reports that decide whether the AI rebound is real.
The OnDeck Book
Trading day change -1.23% and Agentic +0.04% vs the S&P 500's +0.28% Tuesday. Positions (Tuesday official closes, Robinhood): SPCX 150 shares, avg $132.13, close $147.95 (-0.01% on the day), +11.97% vs avg cost, unrealized +$2,372.97 — and $157.89 premarket on the earnings beat. HD 30 shares, avg $293.92, close $315.16 (+1.70%), +7.23% vs avg, unrealized +$637.25. SOFI 200 shares, avg $17.10, close $14.69 (+2.73%), -14.08% vs avg, unrealized -$481.50. QUBT 700 shares, avg $8.21, close $6.49 (+1.09%), -20.95% vs avg, unrealized -$1,204.00. Options (marks at Tuesday's close, Robinhood): SPCX $148 calls expiring Fri Oct 23 — 3 long, mark $5.98 vs $5.16 clearing cost per contract, expiring in 2 days; SPCX $155 calls expiring Oct 23 — 6 long, mark $3.18 vs $2.30; SPCX $152.50 calls expiring Oct 28 — 7 long, mark $4.78 vs $4.71. Total option market value $7,048.00. With SPCX at $157.89 premarket, the $148s are in the money and the $155s are at the strike into Friday's expiry. Futures: /METV26 (Micro Ether, Oct 2026; last trade Oct 30, 2026) long 65 contracts, avg 2,549.89 — web-verified baseline (robinhood.com, 2026-10-14; quantity/avg re-verified 2026-10-15), reported alongside the API aggregate futures market value of $7,999.00. Crypto: ETH 1.6 coins, clearing cost basis $3,916.98, mark $2,460.24 (Robinhood crypto quote, ~7:21 AM ET), indicative value $3,936.38; USDG 102.881882 units total including Crypto Earn (web holdings verification, 2026-10-15; the API spot line shows only 1.0 unit); dust: DOGE 1.0, USDC 0.00993.
Account day change vs adjusted prior close (Tuesday session, Robinhood): Trading -1.23%, Agentic +0.04%.
Drafted premarket Tuesday, October 20, before the opening bell, after Monday’s rebound.
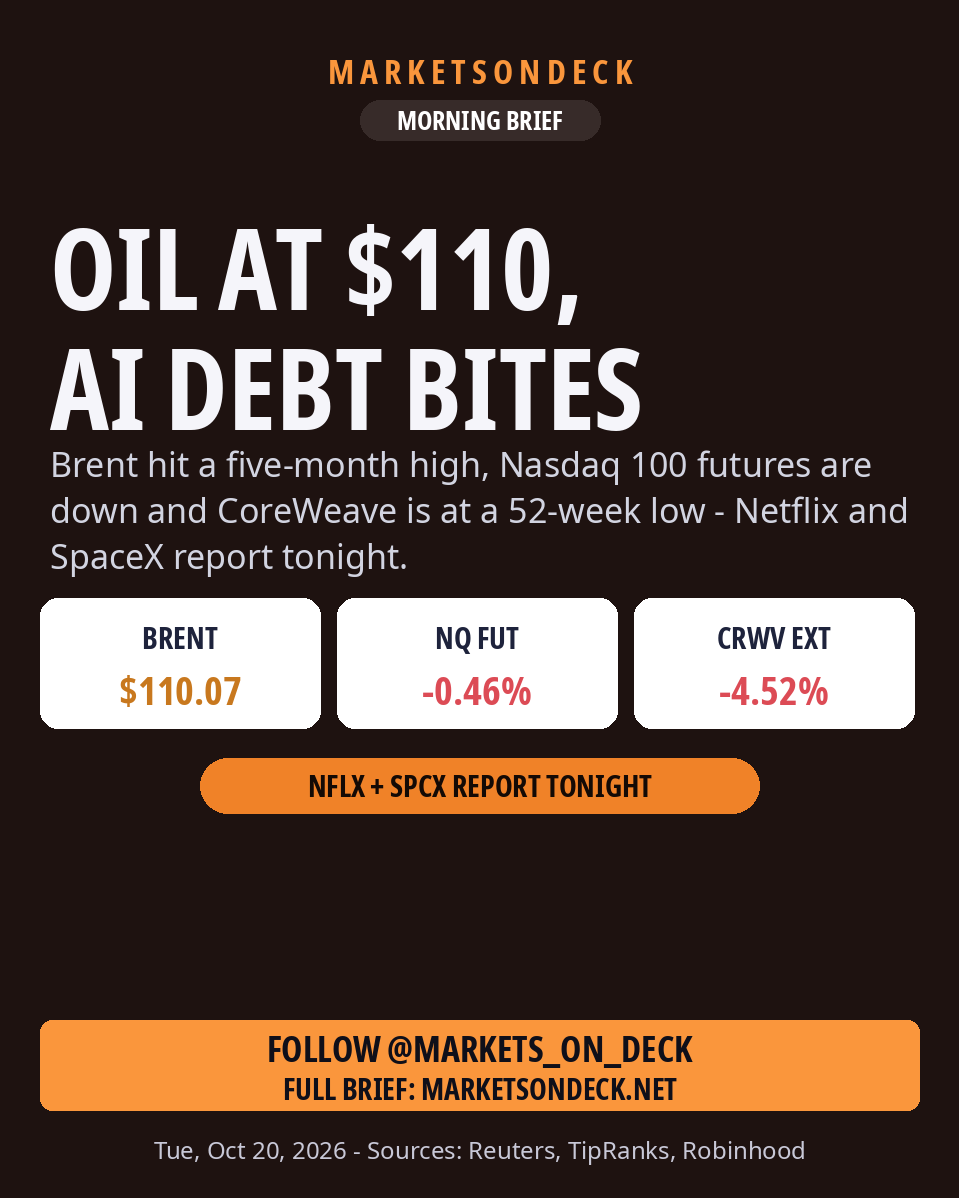
Oil Just Hit $110, CoreWeave Hit a 52-Week Low — and Netflix Reports Tonight
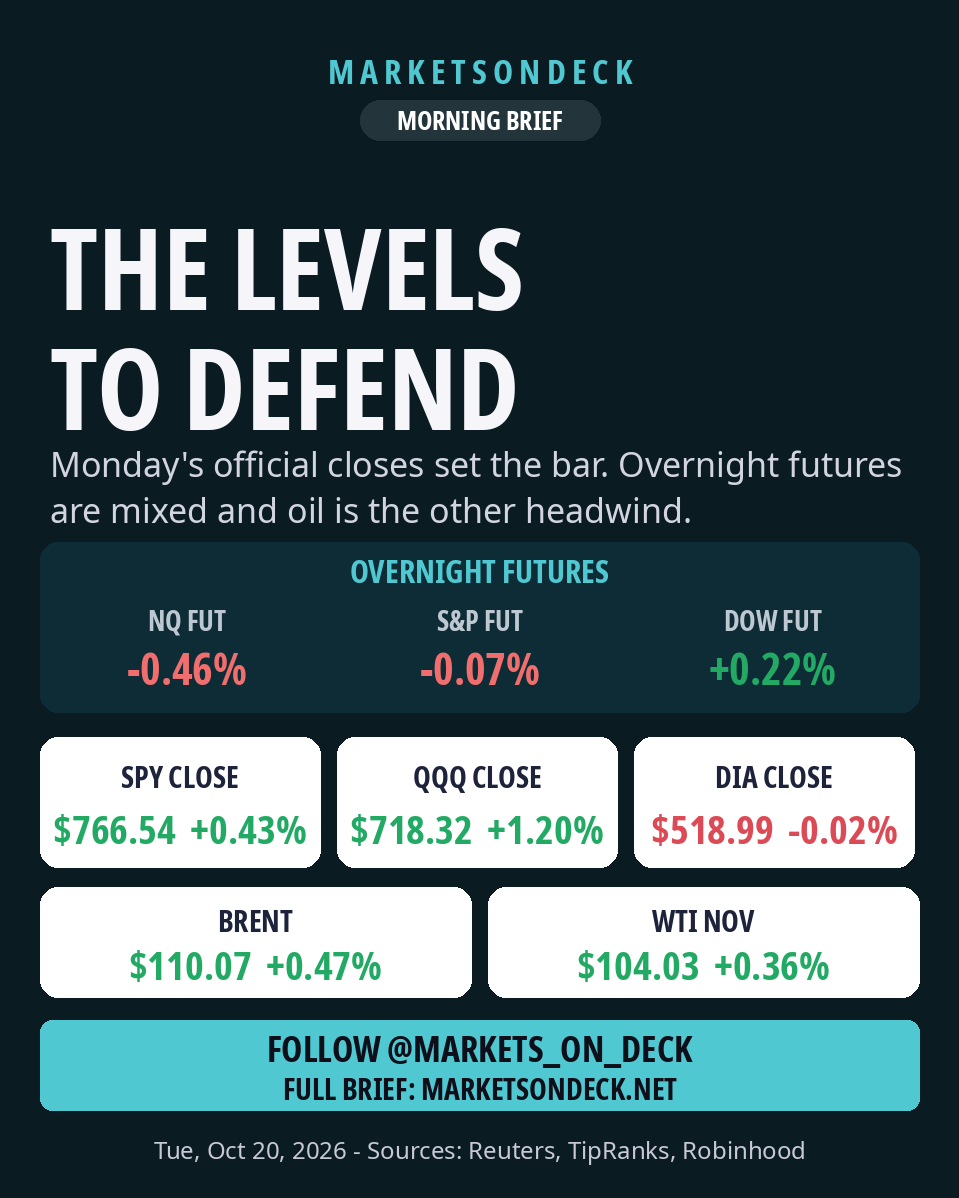
Monday's rebound lifted the Nasdaq 100 ETF 1.20% — this morning Brent crude sits at $110.07, a five-month high, Nasdaq 100 futures are down 0.46% on AI debt fears, and tonight Netflix and SpaceX deliver the first verdicts of earnings week.
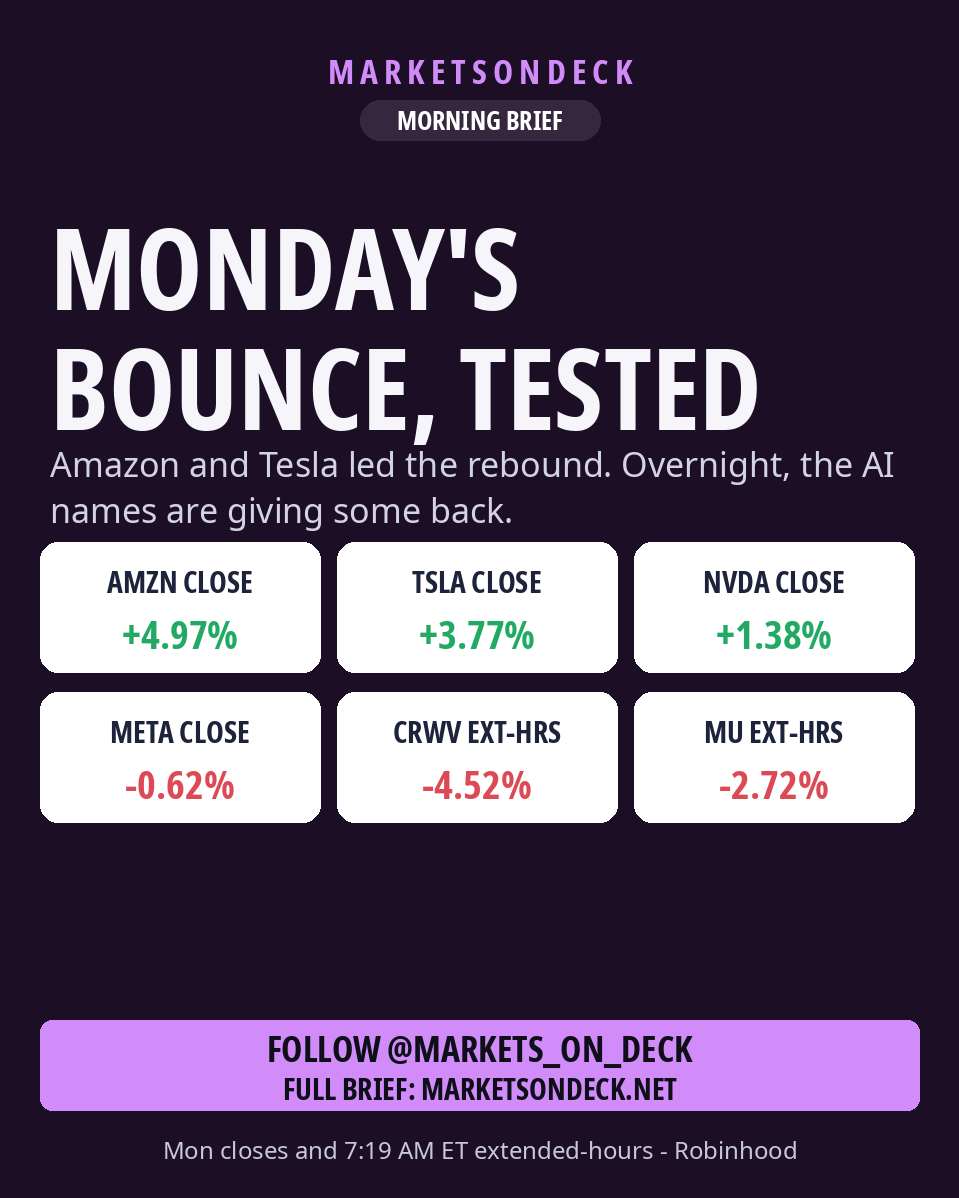
Futures are mixed-to-lower after Monday's rebound. As of 5:34 AM ET (TipRanks): Nasdaq 100 futures -0.46%, S&P 500 futures -0.07% and Dow futures +0.22%. The drag is the AI complex again — debt-funded AI buildout worries pushed CoreWeave to a 52-week low (TipRanks), and in Robinhood extended-hours prints (~7:19 AM ET) CRWV traded $58.35 (-4.52% vs its Monday close), MU $880.68 (-2.72%), INTC $90.35 (-1.76%), NVDA $215.80 (-0.59%) and QQQ $714.12 (-0.58%). Oil is the other headwind: Brent crude futures rose 0.47% to $110.07 a barrel by 0628 GMT, hovering near a five-month high ($110.70 on Monday, the highest since May 20) as Houthi attacks on Saudi infrastructure kept a geopolitical risk premium in the market (Reuters); WTI November futures were $104.03 (+0.36%). Monday's official closes (Robinhood equity quotes) set the bar the session has to defend: SPY $766.54 (+0.43%), QQQ $718.32 (+1.20%) and DIA $518.99 (-0.02%). The Mag 7 mostly bounced — AMZN $262.44 (+4.97%), TSLA $368.09 (+3.77%), NVDA $217.09 (+1.38%), GOOGL $344.20 (+1.06%) and MSFT $533.61 (+0.86%) — while META $704.95 (-0.62%) and AAPL $342.97 (-0.14%) lagged. Crypto faded with risk: BTC mark $81,411.87 (-0.76% vs its session open) and ETH mark $2,381.38 (-1.28%), Robinhood crypto quotes at 7:19 AM ET.
This morning's earnings are a clean sweep of beats so far (Robinhood earnings calendar, Oct 20, pre-open reports): Northrop Grumman (NOC) $7.89 vs a $7.19 estimate, RTX $2.26 vs $1.78, Hasbro (HAS) $2.90 vs $1.85, GE Aerospace (GE) $2.25 vs $2.01, GM $3.70 vs $3.61, 3M (MMM) $2.50 vs $2.39, Equifax (EFX) $2.26 vs $2.20 and Halliburton (HAL) $0.60 vs $0.58. Extended-hours trade is not rewarding all of them — GM printed $78.92 (-4.59% vs its $82.72 Monday close) and GE $306.71 (-1.48%) in Robinhood extended-hours prints — so guidance, not the headline EPS, is doing the talking. After today's close comes the week's first main event: Netflix (NFLX, est $0.82; the stock is down about 26% year-to-date into the print, TipRanks) and SpaceX (SPCX, est $0.16), plus United Airlines (UAL, est $2.59), Intuitive Surgical (ISRG, est $2.54), Capital One (COF, est $5.49) and Chubb (CB, est $6.74). Wednesday after the close: Meta (est $5.89) and Tesla (est $0.40). Levels to watch: QQQ closed $718.32 with extended trade at $714.12 — holding Monday's close is the rebound's first test; NVDA closed $217.09, extended $215.80, with Friday's $214.13 close below that; Brent at $110.07 — a push through Monday's $110.70 high adds pressure to everything rate- and fuel-sensitive. Watch today: whether the chip slide (CRWV, MU, INTC all red premarket) drags QQQ under its Monday close in the first hour, and whether Brent holds above $110 into the Netflix and SpaceX prints after the close.
The OnDeck Book
Account total equity $43,254.52, core portfolio equity $38,875.64 vs a $37,429.17 adjusted prior close (Monday session day change +$1,446.47, +3.86%), buying power $13,919.19, cash -$6,145.91, options market value $7,085.00 and API futures market value $7,452.75 (Robinhood portfolio pull, 7:18 AM ET; the API exposes futures only as this aggregate). Positions (official Oct 19 closes, Robinhood): SPCX 150 shares, avg cost $132.1302, closed $147.971 (+1.33% on the day, +11.99% vs avg cost), equity $22,195.65, extended-hours $146.07; HD 30 shares, avg cost $293.9184, closed $309.99 (+0.12%, +5.47% vs avg cost), equity $9,299.70, extended-hours $311.90; SOFI 200 shares, avg cost $17.0975, closed $14.295 (-1.75%, -16.39% vs avg cost), equity $2,859.00, extended-hours $14.13; QUBT 700 shares, avg cost $8.21, closed $6.445 (+1.34%, -21.50% vs avg cost), equity $4,511.50, extended-hours $6.29. Options — all long SPCX calls (Robinhood option positions + quotes, marks as of Oct 19 close): 3x 148C expiring Friday, Oct 23 (3 days), clearing cost $5.16/contract ($1,548 total) vs a $6.00 adjusted mark, market value $1,800.00, delta 0.520967; 6x 155C expiring Friday, Oct 23 (3 days), clearing cost $2.30/contract ($1,380 total) vs a $3.15 adjusted mark, market value $1,890.00, delta 0.33968; 7x 152.5C expiring Oct 28 (8 days), clearing cost $4.7143/contract ($3,300 total) vs a $4.85 adjusted mark, market value $3,395.00, delta 0.420981. The Oct 23 lines were trimmed on Oct 19 (from 12x/24x in Monday morning's brief to 3x/6x) and the 152.5C line was opened Oct 19. Futures: /METV26 (Micro Ether, Oct 2026; last trade Oct 30, 2026) long 65 contracts, avg 2,549.89 — web-verified baseline (robinhood.com, 2026-10-14; quantity/avg re-verified 2026-10-15), reported alongside the API aggregate futures market value of $7,452.75 above. Crypto: ETH 1.6 coins, clearing cost basis $3,916.98, mark $2,381.38 (Robinhood crypto quote, 7:19 AM ET), indicative value $3,810.21; USDG 102.881882 units total including Crypto Earn (web holdings verification, 2026-10-15; the API spot line shows only 1.0 unit); dust: DOGE 1.0, USDC 0.00993, ETH spot dust ~0.000001. SPCX note: SpaceX reports earnings today, Oct 20, after the close (est $0.16, Robinhood earnings calendar); Deutsche Bank weighed in on whether the stock jumps or tumbles after earnings (TipRanks via Robinhood news, Oct 19).
The account scoreboard for Monday’s session, day change against adjusted prior closes (Robinhood): Trading +3.86%, Agentic +19.57%.
Drafted premarket Monday, October 19, before the opening bell, after Friday capped the worst week since late June for the S&P 500 and the Nasdaq.
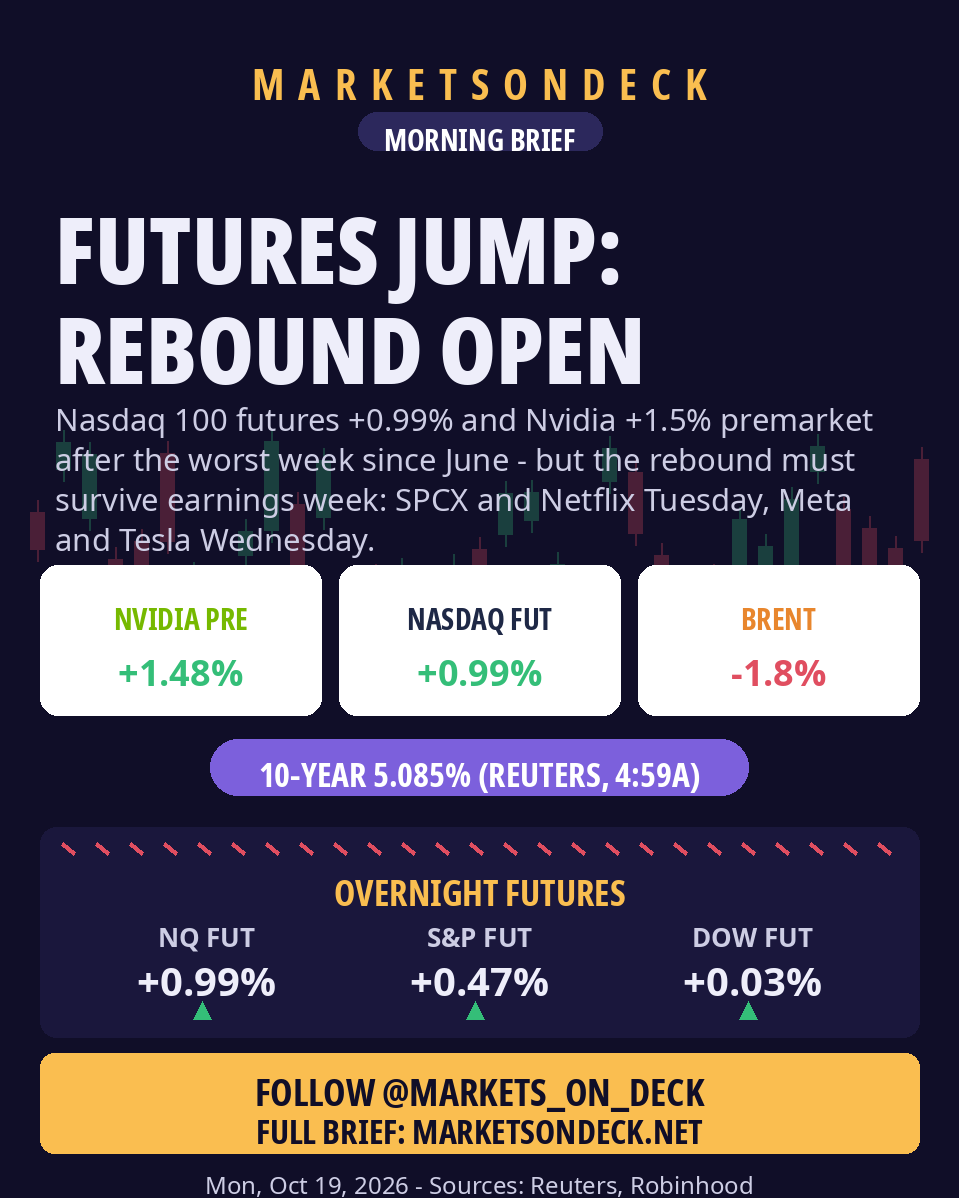
Nasdaq Futures Jump 0.99% as Nvidia Bounces Back — and Mag 7 Earnings Week Decides Whether the Rebound Is Real
After the Nasdaq’s worst week since June, futures are pointing the other way — Nasdaq 100 futures +0.99% and Nvidia +1.5% in extended-hours trade — but the rebound has to survive the biggest earnings gauntlet of the season, with SpaceX and Netflix on Tuesday and Meta and Tesla on Wednesday.
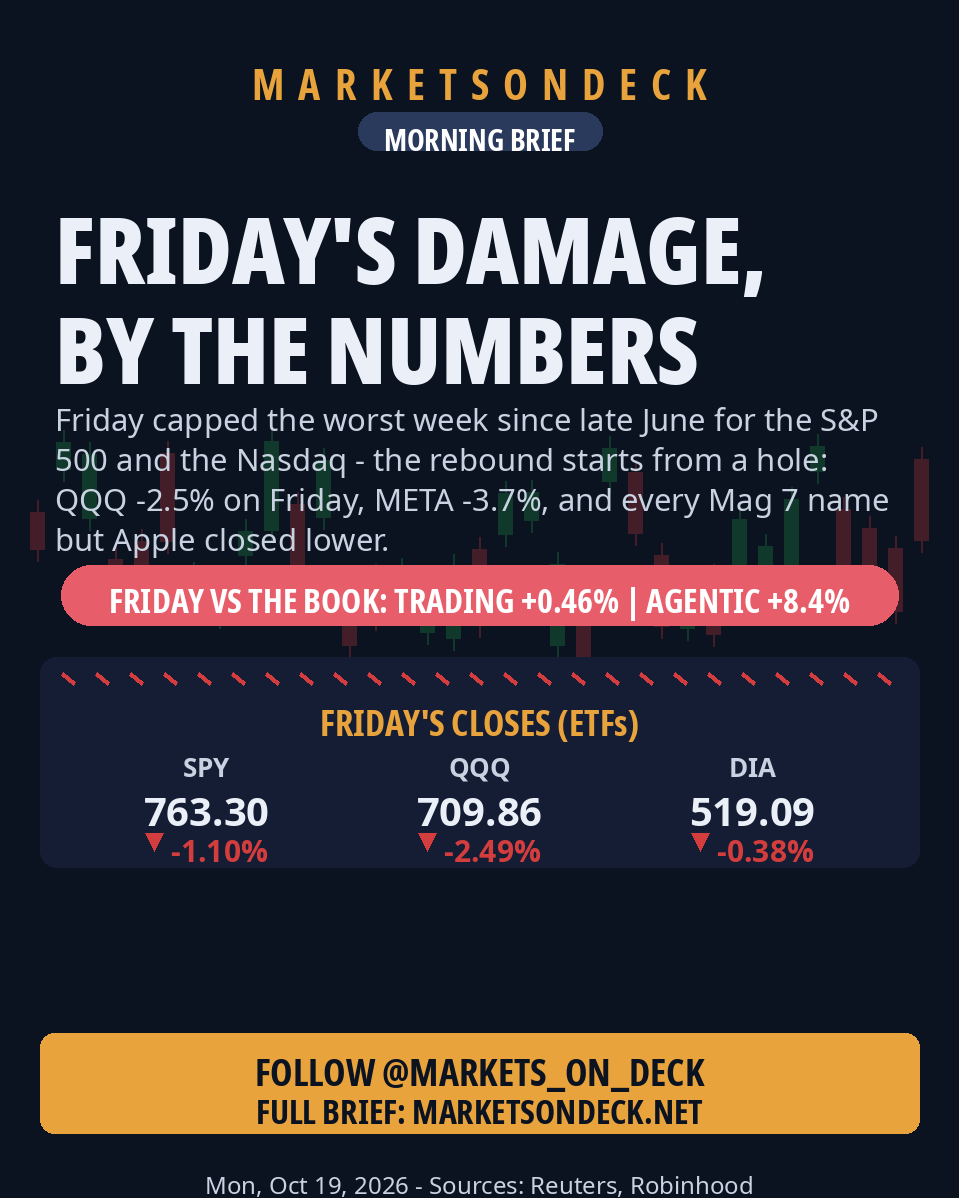
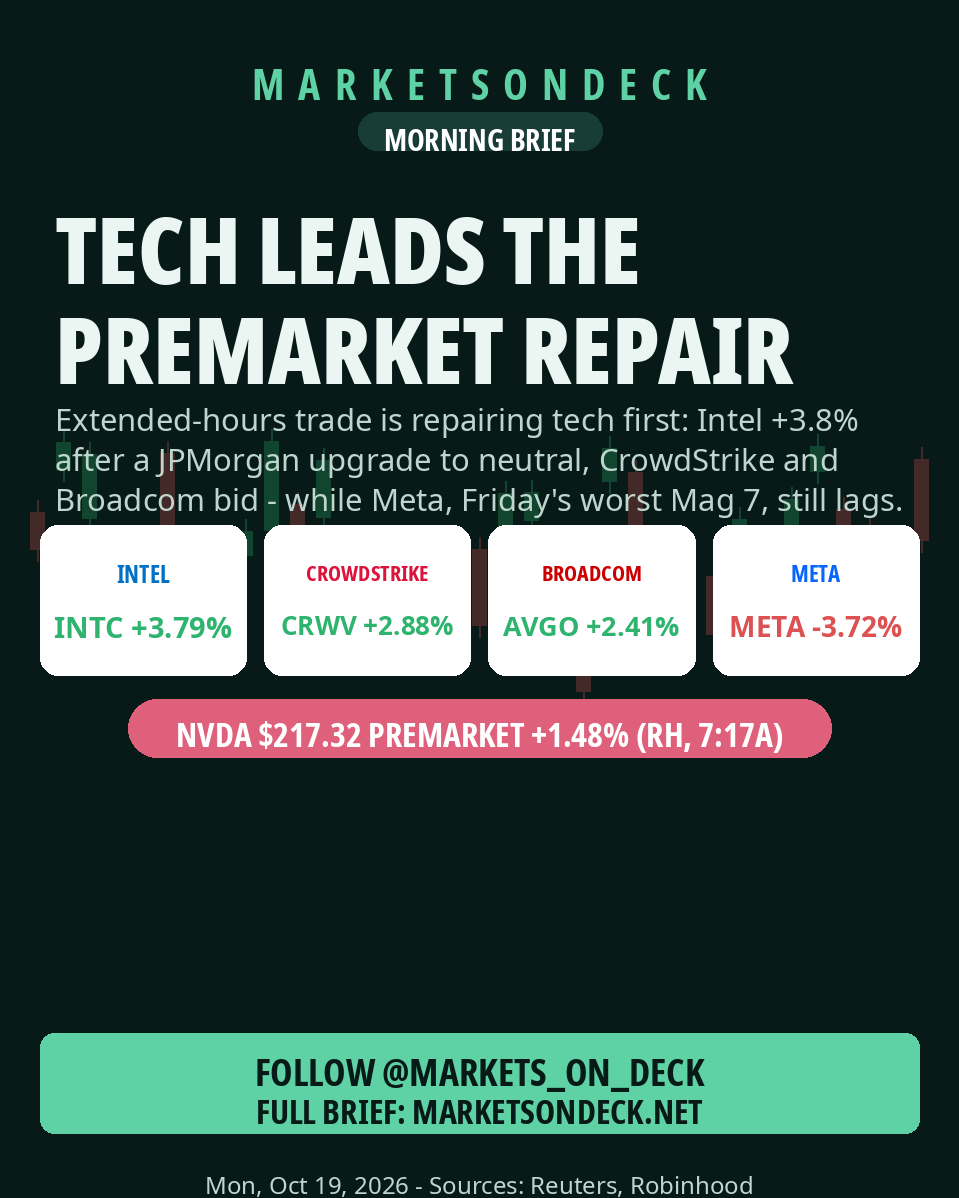
Futures point to a rebound open after Friday capped the worst week since late June for the S&P 500 and the Nasdaq Composite (Reuters). As of 4:59 AM ET (Reuters): Nasdaq 100 E-minis +292.25 points (+0.99%), S&P 500 E-minis +36 points (+0.47%) and Dow E-minis +18 points (+0.03%). Two of Friday’s headwinds eased: Brent futures fell 1.8% to around $107 a barrel after President Trump waived some sanctions on Russia, and the benchmark 10-year Treasury yield fell to 5.085% (Reuters). Friday’s official closes (Robinhood equity quotes) show the damage the rebound has to repair: $SPY $763.30 (-1.10% vs its $771.79 prior close), $QQQ $709.86 (-2.49% vs $728.00) and $DIA $519.09 (-0.38% vs $521.07). The Mag 7 closed almost uniformly lower — $META $709.34 (-3.72%), $GOOGL $340.59 (-2.47%), $TSLA $354.67 (-2.14%), $MSFT $528.95 (-1.94%), $AMZN $249.95 (-1.89%) and $NVDA $214.14 (-1.42%) — with $AAPL the only gainer at $343.41 (+0.41%). Extended-hours trade early Monday was repairing tech first: NVDA $217.32 (+1.48% vs its Friday close), QQQ $717.52 (+1.08%), SPY $767.02 (+0.49%), AVGO $336.74 (+2.41%), CRWV $63.16 (+2.88%) and INTC $93.20 (+3.79%), while META $704.97 (-0.62%) and TSLA $353.06 (-0.45%) still lagged (Robinhood extended-hours prints, ~7:17 AM ET). Intel’s premarket jump followed a JPMorgan upgrade to neutral from underweight (Reuters). Crypto was quiet: BTC mark $82,157.33 (-0.32% vs its session open) and ETH mark $2,414.46 (-0.30% vs open), Robinhood crypto quotes at 7:18 AM ET.
Today’s earnings calendar is light ahead of the week’s main events (Robinhood earnings calendar, Oct 19). Already reported this morning: Fifth Third (FITB) beat, EPS $1.13 vs a $0.87 estimate, and Cleveland-Cliffs (CLF) beat, $0.28 vs $0.24; VinFast (VFS) missed, -$0.53 vs a -$0.31 estimate. After today’s close: Steel Dynamics (STLD, est $5.41), Zions (ZION, est $1.65), Western Alliance (WAL, est $2.43), Crown Holdings (CCK, est $2.26), Wintrust (WTFC, est $3.30) and AGNC (est $0.39). The week builds fast: Tuesday brings GM (est $3.61) and GE Aerospace (est $2.01) before the open, then SpaceX (SPCX, est $0.16) and Netflix (NFLX, est $0.82) after the close; Wednesday brings Meta (est $5.89) and Tesla (est $0.40), both after the close. Levels to watch: NVDA closed Friday at $214.14 and traded at $217.32 in extended hours — reclaiming Thursday’s $217.23 close is the first sign the chip slide is over; QQQ closed $709.86 with extended trade at $717.52, still below its $728.00 Thursday close; SPY closed $763.30 with extended trade at $767.02.
Watch today: whether NVDA holds its extended-hours reclaim of $217.23 into the regular session and QQQ holds above $717.52 — if the rebound survives the first hour with oil lower and the 10-year at 5.085%, earnings week starts from strength; if NVDA fades back under Friday’s $214.14 close, Friday’s rout is not done.
The OnDeck Book
Account total equity $42,018.90, core portfolio equity $37,191.97 vs a $37,021.21 adjusted prior close (Friday session day change +$170.76, +0.46%), buying power $6,261.24, cash -$13,802.18, options market value $13,308.00 and API futures market value $5,374.20 (Robinhood portfolio pull, 7:16 AM ET; the API exposes futures only as this aggregate). Positions (official Oct 16 closes, Robinhood): SPCX 150 shares, avg cost $132.1302, closed $146.03 (-1.74% on the day, +10.52% vs avg cost), equity $21,904.50, extended-hours $145.85; HD 30 shares, avg cost $293.9184, closed $309.63 (+0.45% on the day, +5.35% vs avg cost), equity $9,288.90, extended-hours $309.00; SOFI 200 shares, avg cost $17.0975, closed $14.56 (-3.51% on the day, -14.84% vs avg cost), equity $2,912.00, extended-hours $14.63; QUBT 700 shares, avg cost $8.21, closed $6.365 (-6.94% on the day, -22.47% vs avg cost), equity $4,455.50, extended-hours $6.56.
Options — all long SPCX calls, BOTH lines expiring this week on Friday, Oct 23 (Robinhood option positions + quotes, marks as of Oct 16 close): 12x $148 calls (clearing cost $4.48/contract, $5,376 total) vs a $5.45 adjusted mark, market value $6,540.00, delta 0.474163; 24x $155 calls (clearing cost $2.505/contract, $6,012 total) vs a $2.82 adjusted mark, market value $6,768.00, delta 0.304625.
Futures in the Trading account: the /METV26 Micro Ether position — long 65 contracts at a 2,549.89 average entry (web-verified October 14 via robinhood.com; quantity and average re-verified October 15; the contract’s last trade date is October 30, 2026) — carried a futures market value of $5,374.20 in this morning’s Robinhood portfolio pull. Per-contract detail isn’t available through the API, so that aggregate market value is what’s reported here.
Crypto: ETH 1.6 coins held, clearing cost basis $3,916.98; ETH mark $2,414.46 at 7:18 AM ET (Robinhood), an indicative value of about $3,863.13 for the position. BTC mark $82,157.33, -0.32% vs its session open. USDG 102.881882 units total including Crypto Earn (web holdings verification, October 15; the API spot line shows only 1.0 unit); dust: CC 1.0, DOGE 1.0, USDC 0.00993. SPCX note: SpaceX fell 10.64% over the past week (TipRanks via Robinhood news, Oct 17) and reports earnings Tuesday, Oct 20 after the close (est $0.16).
The account scoreboard for Friday’s session, day change against adjusted prior closes (Robinhood): Trading +0.46%, Agentic +8.4% — against SPY -1.10%, QQQ -2.49% and DIA -0.38% on the day.
Why this matters: a green premarket after the worst week since June is a promise, not a rebound — it only counts if NVDA holds its reclaim of $217.23 through the open with oil and the 10-year both easing, and the answer sets up the biggest earnings week of the season. For the book, the stakes are concentrated: both SPCX call lines expire Friday, and SpaceX reports Tuesday night — this week’s tape decides them.
Drafted premarket Friday, October 16, before the opening bell, after Thursday's partial, Dow-led bounce from Wednesday's inflation-driven selloff.
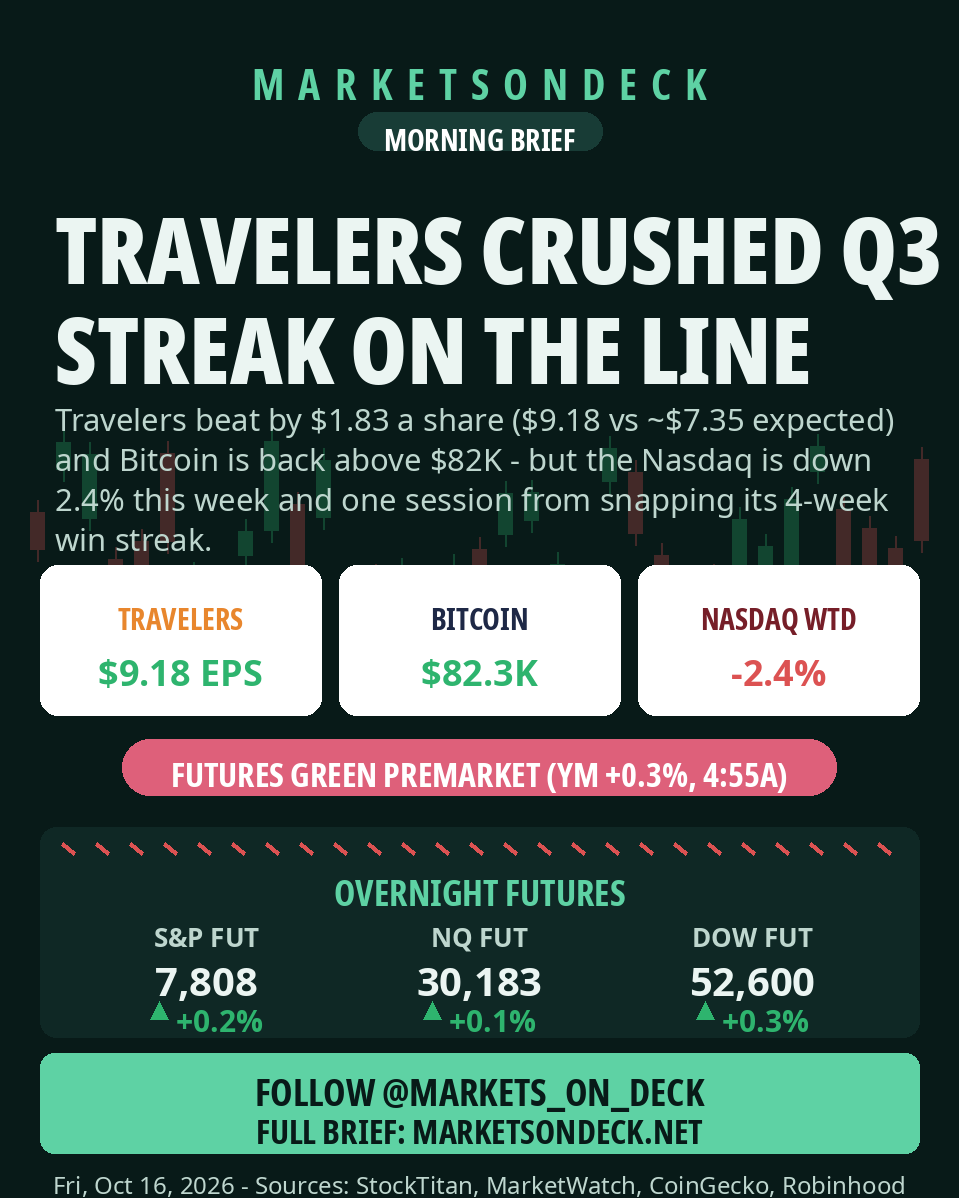
Travelers Just Crushed Estimates by $1.83 a Share — and the Nasdaq Still Faces Its First Losing Week in Five
The Nasdaq Composite is down 2.4% for the week and one session from snapping a four-week winning streak, even after Travelers smashed EPS estimates ($9.18 vs $7.35) and Bitcoin fought back above $82,000 — because the AI complex is still fragile after two hot inflation prints.
Futures point to a steadier open after Thursday’s rotation day. As of 4:55 AM ET (Regards of Wall Street premarket page, delayed quotes): S&P 500 E-minis 7,808 (+0.21%), Nasdaq 100 E-minis 30,183 (+0.13%), Dow E-minis 52,600 (+0.32%) and Russell 2000 futures +0.40%, with the VIX at 16.03 (-2.61%). The WSJ described futures and Treasurys as steady Friday morning as markets took a breather after Thursday’s volatile session, noting AI stocks remained fragile with chip makers slipping in premarket trade and CoreWeave down 2.5% premarket. Thursday’s official closes (Robinhood equity quotes): $SPY $771.74 (+0.28% vs its $769.60 prior close), $QQQ $728.04 (-0.12% vs $728.95) and $DIA $521.14 (+1.07% vs $515.63) — the Dow led as money rotated out of tech.
Mag 7 official closes: $MSFT $539.45 (+1.08%), $GOOGL $349.16 (+0.44%), $AMZN $254.71 (+0.25%), $META $736.48 (-0.14%), $AAPL $341.98 (-0.29%), $TSLA $362.42 (-1.29%) and $NVDA $217.23 (-1.84% vs its $221.30 prior close). Extended-hours prints around 7:17 AM ET were firmer for the laggards: TSLA $375.15, META $741.20, MSFT $541.99, GOOGL $350.50, AMZN $255.55 and SPY $773.31, while NVDA still lagged at $216.90 and QQQ sat at $727.80.
Rates steadied after Fed Chair Kevin Warsh, speaking overnight in Bangkok, declined to signal whether the Fed would hold or hike later this month (WSJ); the 10-year Treasury yield was around 5.08–5.10%, and CME FedWatch odds of a late-October hike fell to 15% from 28% yesterday, with an 89% chance of a hike by December unchanged (Investopedia). Crypto recovered with stocks: BTC mark $82,505.72 (+0.71% vs its $81,925.98 session open) and ETH mark $2,479.13 (+1.72% vs its $2,437.33 open), Robinhood crypto quotes at 7:18 AM ET — Bitcoin back above $82,000 after slipping below $80,000 in the midweek inflation selloff.
Earnings are financials-heavy and mostly reported already (Robinhood earnings calendar, October 16): Travelers (TRV) was the blowout — EPS $9.18 vs a $7.35 estimate. Regions Financial (RF) beat, $0.73 vs $0.66; M&T Bank (MTB) beat, $5.08 vs $4.94; Citizens Financial (CFG) beat, $1.41 vs $1.38; Truist (TFC) was the miss, $1.16 vs a $1.20 estimate. Still to come this morning: Webster Financial (WBS, est $1.63) and Comerica (CMA, est $1.45). The macro calendar adds U.S. import and export price indexes at 8:30 AM ET and September industrial production at 9:15 AM ET. Levels to watch: NVDA closed at $217.23 and was still offered premarket at $216.90 — it needs to reclaim its $221.30 prior close to say the chip slide is over; QQQ closed $728.04, just under its $728.95 prior close; SPY closed $771.74 with extended-hours trade at $773.31.
Watch today: whether the Nasdaq’s 4-week winning streak survives — the index is down 2.4% this week going into the Friday session, and NVDA’s extended-hours print ($216.90) still sits below the $221.30 prior close it needs to reclaim. A green Friday for chips is the difference between a five-week streak and the first losing week in five.
The OnDeck Book
Account total equity $41,307.80, buying power $11,439.43, cash -$7,999.29 (Robinhood portfolio pull, 7:17 AM ET). Positions, at Thursday’s official closes: HD 50 shares at $308.27 vs $293.92 avg (+$717.58, +4.88%), $310.00 in extended hours, +4.32% on the day Thursday. SPCX 100 shares at $148.64 vs $123.84 avg (+$2,479.97, +20.03%), $151.01 extended, -2.31% Thursday. SOFI 200 shares at $15.075 vs $17.10 avg (-$404.50, -11.83%), $15.13 extended, +6.01% Thursday. QUBT 700 shares at $6.86 vs $8.21 avg (-$945.00, -16.44%), $6.79 extended, +8.72% Thursday. Prices are Thursday’s official closes per the Robinhood portfolio pull at 7:17–7:18 AM ET; extended-hours prints from Robinhood equity quotes at ~7:18 AM ET.
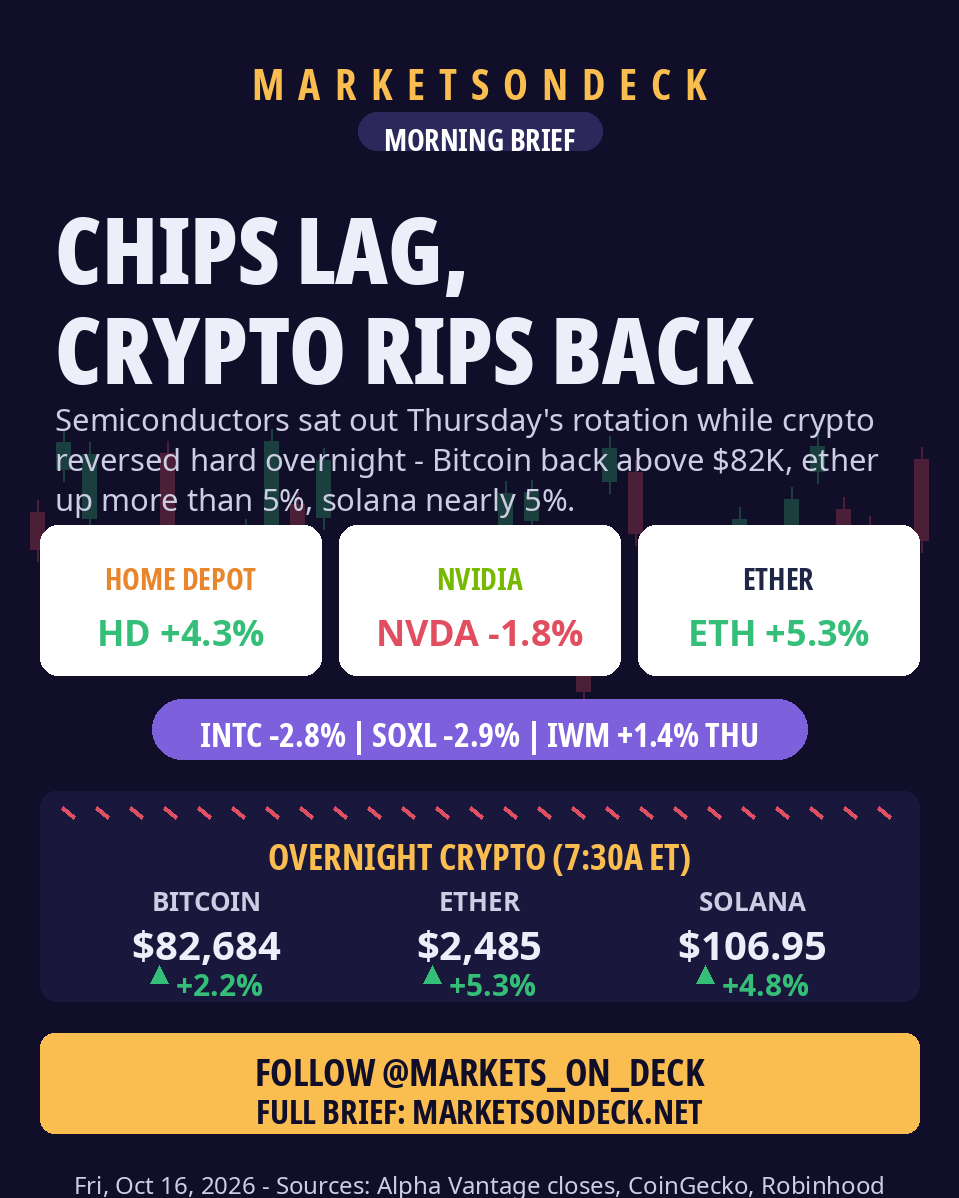
Options — two positions expire TODAY, Friday October 16 (0 days): SPCX $147 calls ×1 long (clearing basis $176, $1.76 per contract; mark $2.87, value $287, +$111 vs clearing basis, delta 0.639) and SPCX $152.50 calls ×2 long (clearing basis $476, $2.38 per contract; mark $0.66, value $132, -$344 vs clearing basis). Also open: SPCX $148 calls expiring October 23 ×7 long (clearing basis $2,796, $3.99 per contract; mark $4.93, value $3,451, +$655 vs clearing basis, 7 days) and SPCX $155 calls expiring October 23 ×14 long (clearing basis $3,260, $2.33 per contract; mark $2.18, value $3,052, -$208 vs clearing basis, 7 days). Total option market value $6,922 per the portfolio API, matching the sum of the four adjusted marks. Option marks are Thursday’s closes per Robinhood option quotes.
Futures in the Trading account: the /METV26 Micro Ether position — long 65 contracts at a 2,549.89 average entry (web-verified October 14 via robinhood.com; quantity and average re-verified October 15; the contract’s last trade date is October 30, 2026) — carried a futures market value of $5,505.50 in this morning’s Robinhood portfolio pull. Per-contract detail isn’t available through the API, so that aggregate market value is what’s reported here.
Crypto: ETH 1.60 coins held, clearing cost basis $3,916.98; ETH mark $2,479.13 at 7:18 AM ET (Robinhood), an indicative value of about $3,966.60 for the position. BTC mark $82,505.72, +0.71% vs its session open. USDG 102.881882 units total including Crypto Earn (web holdings verification, October 15; the API spot line shows only 1.0 unit); dust: CC 1.0, DOGE 1.0, USDC 0.00993.
The account scoreboard for Thursday’s session, day change against adjusted prior closes (Robinhood): Trading -0.24%, Agentic -1.68% — against the S&P 500 +0.3%, Nasdaq +0.1% and Dow +1.1% on the day.
Drafted premarket Thursday, October 15, before the opening bell, as September's Producer Price Index, retail sales, and jobless claims land at 8:30 a.m. ET — one day behind a hotter-than-expected Consumer Price Index print.
A hot CPI print sends chips and crypto reeling, new SpaceX call positions get opened mid-selloff, and the oldest options bet in the book is marked down 93% with one day left
$SPY closed Wednesday, October 14 at $769.63, down 1.08% ($8.38) — the sharpest one-day loss this brief has logged in several weeks, pulling the index about 1.1% below the $777.88 closing high it's tracked since August 13. $QQQ fell harder, down 1.98% to $728.84, while $DIA held up far better, down just 0.10% to $515.68 — the same kind of split between the Dow and the growth-heavy benchmarks this brief has flagged before, just with a much wider gap this time.
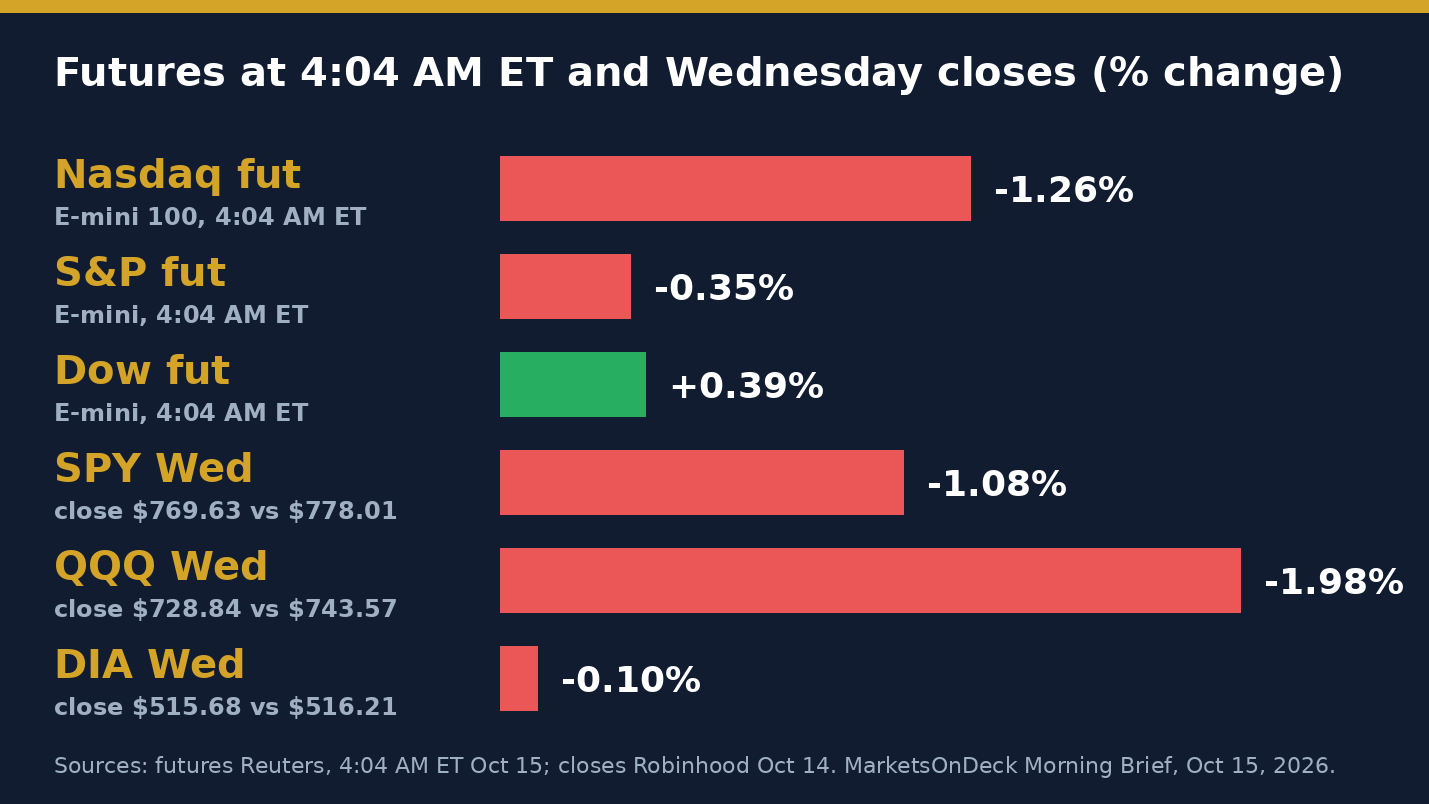
The cause was the number this brief has been counting down to since Monday. September's Consumer Price Index came in hotter than forecast Wednesday morning: headline inflation rose 3.7% year-over-year against a roughly 3.6% consensus, and core CPI (ex food and energy) rose 2.6% year-over-year and 0.3% month-over-month, both above expectations, per CNBC's Wednesday coverage and Yahoo Finance's live markets coverage. Energy did a lot of the work — a sharp gasoline-price increase accounted for roughly half the headline's monthly gain — and the 10-year Treasury yield rose to around 5.27% on the print. Technology was the weakest S&P sector on the day, and the move showed up loudest in the leveraged semiconductor ETFs this brief has tracked before: the 3x-bullish SOXL fell 13.32% to $110.58 while the 3x-bearish SOXS rose 13.55% to $42.49, per Alpha Vantage's Wednesday close data, with $NVDA down 3.07% to $221.50 and $INTC down 4.80% to $97.88 the same session.
Crypto didn't sit out Wednesday's risk-off mood overnight either, which is itself a shift from the calm this brief logged as recently as Tuesday. Bitcoin is down 2.92% to $80,950.48, ether is down a sharper 5.56% to $2,362.30, and solana is down 4.49% to $102.23, all as of about 7:30 a.m. ET.
The real, dated activity in the book happened during Wednesday's actual selloff, not after it. Home Depot (HD) in the Trading account had both of its call positions trimmed further Wednesday — the $295 calls expiring tomorrow, Friday, October 16, are down to 2 contracts from the 5 flagged here Tuesday, and the $300 calls expiring October 30 are down to 2 from 3. HD itself bucked the broader tape, closing Wednesday at $295.55 (up about 0.55% from Tuesday's $293.92 close) and trading higher still in premarket, around $299.00 (up a further 1.2%) as of 7:16 a.m. ET — putting both the shares (120 at a $293.92 average cost, about 1.7% above cost at the premarket print) and the $295 calls back in the money, with the $300 calls now just $1.00 away. SpaceX (SPCX), 100 shares at a $123.84 average cost, picked up two brand-new call positions during Wednesday's session instead: 5 contracts at the $152.50 strike expiring tomorrow, October 16, opened around 3:49 p.m. ET at an average premium of $2.38, and 4 contracts at the $155 strike expiring October 23, opened earlier the same day around 11:44 a.m. ET at an average premium of $3.90. Both were opened while SPCX itself was sliding — the stock fell to a $152.27 close and is down a further 2.8% in premarket, around $148.08 this morning (7:16 a.m. ET) — so neither new position has had a chance to work in its favor yet; the $152.50s closed Wednesday marked at $2.46, roughly flat on entry, while the $155s closed at $3.48, down about 10.8% on entry.
The oldest options bet still open in the book, SPCX's 2 calls at the $162.50 strike also expiring tomorrow, is the clearest loss in the book right now. Bought at an average premium of $3.20 a contract on October 9, that position closed Wednesday marked at just $0.23 — down about 92.8% from entry — with SPCX trading roughly 8.9% below that strike this morning and one trading day left after today. It's a real loss on a position logged here when it was opened, the same way every winning position gets reported; nothing about the rest of the book's gains changes that.
The rest of the Trading account moved lower with Wednesday's broader selloff. SoFi (SOFI), 200 shares at a $17.10 average cost, closed Wednesday at $14.23, about 16.8% below cost, and is trading near $13.94 in premarket, a further 2.0% lower; no company-specific news I could confirm today, just the same tech-selloff pressure hitting the rest of the tape. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed at $6.33, about 28.2% below cost, and is trading near $6.15 premarket, also quiet apart from the broader move.
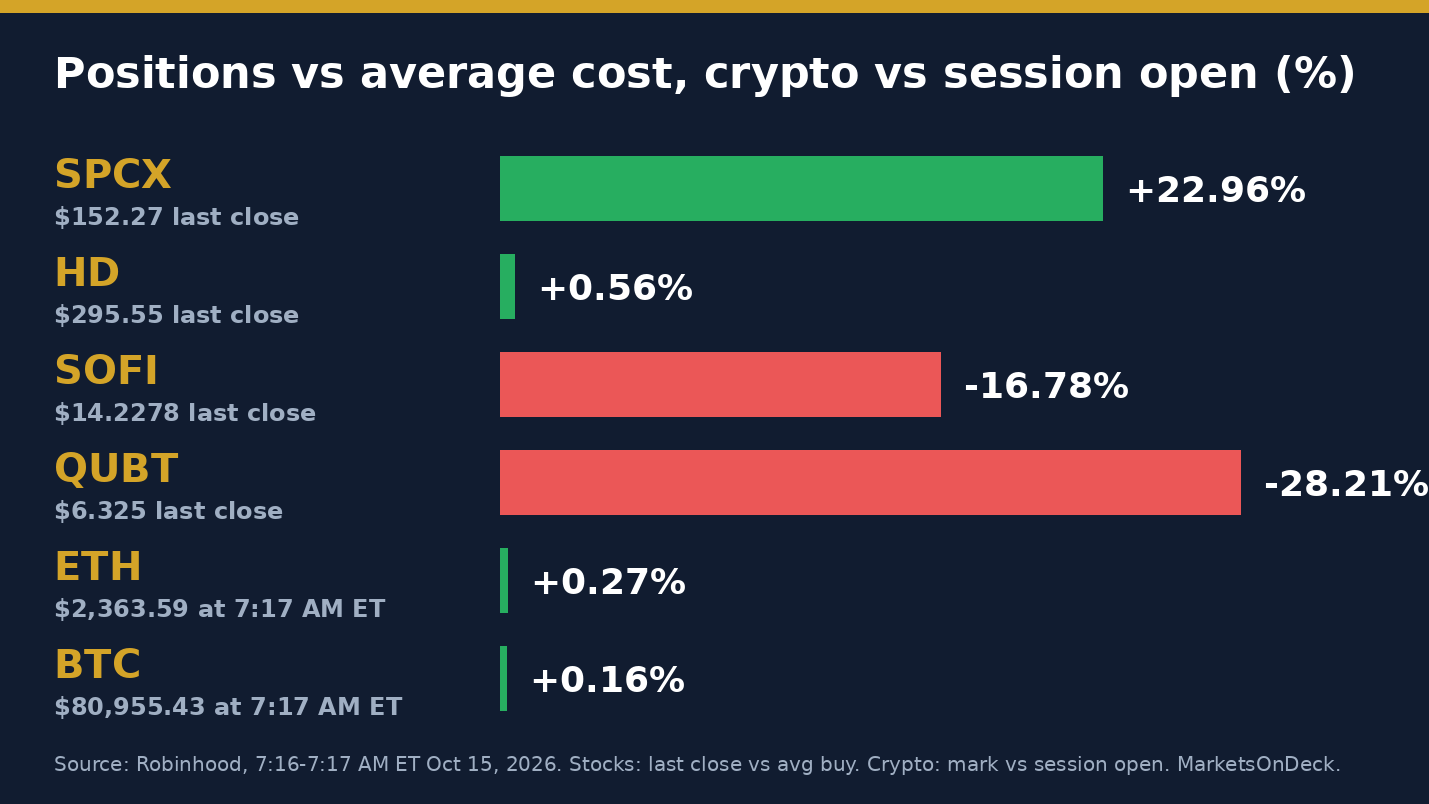
Futures in the Trading account: the /METV26 Micro Ether position — long 65 contracts at a 2,549.89 average entry (web-verified October 14 via robinhood.com; the contract's last trade date is October 30, 2026) — carried a futures market value of $3,716.10 in this morning's Robinhood portfolio pull. Per-contract detail isn't available through the API, so the aggregate market value is what's reported here.
Today brings the next real data test, one day behind Wednesday's CPI surprise: September's Producer Price Index, retail sales, and weekly jobless claims all land at 8:30 a.m. ET, with the Philadelphia Fed's manufacturing index following shortly after, per InvestingLive's week-ahead preview. There's no Fed meeting this week — the next rate decision is still October 27–28 — so this morning's data is the more immediate test of whether Wednesday's inflation scare was a one-off or the start of a trend.
Why this matters: Wednesday's hot CPI print did what hot inflation prints tend to do — it hit growth and chip stocks hardest and pushed yields higher — and this time it didn't stop at the close, carrying into an overnight crypto selloff that's sharper in ether than in bitcoin. For the book, the real story isn't the headline number itself; it's that new option risk got added on SpaceX in the middle of that exact selloff, while the oldest contract still open in the book lost roughly 93% of its value — both logged here as they happened, not after the fact, and neither is a reason to expect any particular outcome from here. Today's PPI, retail sales, and jobless claims data is the next real test of whether yesterday's inflation surprise was a one-day scare or the start of something the market has to keep pricing in.
Drafted premarket Wednesday, October 14, before the opening bell, ahead of this morning's 8:30 a.m. ET release of September's Consumer Price Index.
September CPI lands at 8:30 this morning as the bank-earnings wave keeps rolling, ASML's chip-demand optimism doesn't reach KLAC, and HD's Friday calls edge back toward their strike with two trading days left
$SPY closed Tuesday, October 13 at $778.03, down a slim 0.01% ($0.07) — essentially flat, holding just above the $777.88 closing high this brief has tracked since August 13, though still about 0.18% below the $779.42 record set October 6. $QQQ fell harder, down 0.33% to $743.59, and $DIA dropped 0.34% to $516.16 — a quieter, more uniform pullback than the split between the Dow and the other two benchmarks flagged here yesterday.
The actual event this morning is the one this brief has been counting down to for more than a week: the Bureau of Labor Statistics releases September's Consumer Price Index at 8:30 a.m. ET, with consensus looking for headline inflation up 0.6% month-over-month and 3.6% year-over-year, and core CPI (ex food and energy) up a smaller 0.2% month-over-month and 2.5% year-over-year, per a week-ahead preview from InvestingLive and this morning's live markets coverage from Yahoo Finance. A hotter-than-expected print is the real risk here — it's the kind of number that could put an October rate move back into the conversation, even though the Fed's own next decision isn't until October 27–28. The 10-year Treasury yield was sitting near 5.2% ahead of the release and Brent crude was still trading above $105, per Yahoo Finance's coverage this morning, while futures themselves were only modestly positioned either way as of this writing — Dow futures up roughly 0.3%, S&P 500 futures up about 0.2%, Nasdaq 100 futures little changed.
The Q3 bank-earnings wave flagged here yesterday is still running: JPMorgan reported Tuesday morning, with Goldman Sachs, Citigroup, and Wells Fargo also on Tuesday's schedule, and Bank of America and Morgan Stanley are both scheduled to report before today's open, per a Wednesday-earnings preview recapped by Forbes Argentina and a separate stock-calendar tracker. Bank of America was trading lower in premarket, which Yahoo Finance's live markets coverage this morning attributed to a regulatory fine — I couldn't independently confirm the specifics of that action as of this writing, so take that detail as reported rather than verified here. The same coverage also flagged ASML reiterating that chip supply won't meet demand for the foreseeable future, a message that's been lifting sentiment across chip names broadly.
That broader chip optimism doesn't appear to be reaching KLA Corporation (KLAC), the Agentic account's only position, though. KLAC fell 3.43% to $183.60 Tuesday even as NVDA rose 1.22% to $229.08 and Intel gained 1.71% to $103.08 the same session, per the site's own ticker data — a real divergence between a chip-equipment name and the fabless/chipmaker side of the trade KLAC usually tracks. KLAC was trading around $181.61 in premarket as of about 7:35 a.m. ET, down another 1.3%, pulling the roughly 1.0-share Agentic position (average cost $187.15) about 2.9% below that cost basis — the first time this brief has logged KLAC trading beneath its own average cost rather than above it. No fresh KLAC-specific headline I could confirm behind the move; it reads more like an equipment-specific pullback than the broader semiconductor story ASML's commentary is lifting.
Home Depot (HD) in the Trading account has the tightest dated item in the book again this morning. The 5 contracts of $295 calls expiring Friday, October 16 — down from the 8 flagged here as recently as yesterday's entry, a trim — have two trading days left, and premarket is putting them back in play for the first time in a few sessions: HD's only premarket print as of about 7:34 a.m. ET was $296.50, above the $295 strike, though on a thin, wide premarket book ($295.50 bid / $297.02 ask), so that's one print, not a confirmed trend. HD itself closed Tuesday at $293.93, essentially flat against the 120 shares' $293.92 average cost — the closest that comparison has been in a while. The 3 contracts of $300 calls expiring October 30 remain further out, about $3.50 (1.2%) away on that same premarket print.
SpaceX (SPCX), 100 shares at a $123.84 average cost in the Trading account, fell a sharper 4.18% Tuesday to $156.59 — still up 26.45% on cost despite the pullback — and the options side of that position tells a rougher story. The 2 calls at the $162.50 strike, also expiring Friday, October 16, were bought at an average premium of $3.20 a contract and are now marked around $0.95, down roughly 70% on that premium, with SPCX trading near $156.95 in premarket — about $5.55 (3.5%) out of the money with two trading days left. No company-specific headline I could confirm behind the drift. The shares are still a real winner on cost; this particular options bet, logged here when it was opened, is a real loss so far — both get reported the same way.
The rest of the Trading account was quiet. SoFi (SOFI), 200 shares at a $17.10 average cost, closed Tuesday unchanged at $15.23, about 10.9% below cost, and is trading a touch lower premarket around $15.16; no company-specific news I could confirm today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed down 0.87% to $6.87, about 22.0% below cost, and is trading near $6.83 premarket, also quiet.
Crypto isn't reflecting any of equities' CPI anxiety this morning — bitcoin is up 0.04% to $83,285.70, ether is up 0.06% to $2,498.78, and solana is up 0.79% to $106.88, all as of about 7:30 a.m. ET — a notably calmer tape than the one equities are bracing for at 8:30.
Tomorrow, Thursday, October 15, brings September's Producer Price Index and retail sales data, plus jobless claims, all at 8:30 a.m. ET — real data, but secondary to today's CPI print. There's no jobs report this week (September's already landed October 2; the next one isn't due until November 6), and the Fed's own next decision is still two weeks out, October 27–28.
Futures in the Trading account: the /METV26 Micro Ether position — long 20 contracts at a 2,698.325 average entry (baseline verified September 27; the contract expires this month, October 2026) — carried a futures market value of $4,160.00 in this morning's Robinhood portfolio pull. Per-contract detail isn't available through the API, so the aggregate market value is what's reported here.
Why this matters: today's actual test is a single number at 8:30 a.m. ET that nobody, including me, knows yet as this is being written — a hot CPI print revives the rate-hike conversation the market had mostly set aside, a soft one doesn't, and that's a real, unresolved split rather than something to call in advance. For the book, the more interesting split is already visible: ASML's supply-can't-meet-demand message is lifting chip sentiment broadly, but KLAC is moving the opposite direction from NVDA and Intel on the same tape, and SPCX's own options bet has lost roughly 70% of its premium even as the underlying shares sit comfortably ahead on cost. None of this is a signal to expect a particular outcome in any name; it's simply the real, mixed state of the book heading into a release that's about to turn today's premarket calm into something else, one way or the other.
Drafted premarket Tuesday, October 13, before the opening bell, as the first wave of Q3 bank earnings reports before today's open.
Bank earnings open Q3 season as chip-sector pressure pulls KLAC through its own cost basis, and HD's and SPCX's Friday calls both tighten into a near coin-flip
$SPY closed Monday, October 12 at $778.00, down 0.07% ($0.57) — a slim pullback that still leaves the index a touch above the $777.88 closing high this brief has tracked since August 13, though well off last Tuesday's $779.42 record. $QQQ fell harder, down 0.73% to $745.80, while $DIA actually rose 0.33% to $517.83 — the same kind of split between the Dow and the other two benchmarks this brief has flagged more than once this month.
That split traces to the same place it did a week ago Thursday: chip-adjacent names, not a broad macro move. The leveraged semiconductor ETFs show the scale of it — the 3x-bullish SOXL fell 8.18% Monday to $128.33 while the 3x-bearish SOXS rose 8.29% to $37.24 — with Intel down 3.20% to $101.35 and Nvidia off 1.29% to $226.32, per Alpha Vantage's Monday session data. KLA Corporation (KLAC), the Agentic account's only position, felt it directly: the stock closed Monday at $190.12, down about 2.8% from Friday's $195.57 close, pulling the position from roughly 3.0% above its $189.93 average cost at Friday's close to essentially flat against that cost at Monday's close, about 0.1% above it, with KLAC trading around $185.84 in premarket (down a further 2.25%) as of about 7:35 a.m. ET — a real swing across the cost line inside less than two sessions, with no fresh KLAC-specific headline behind it that I could confirm, just the same sector pressure.
Crypto isn't following equities' split in either direction this morning: bitcoin is up 0.20% to $83,481.78, ether is down 1.46% to $2,506.56, and solana is down a sharper 3.65% to $106.85, all as of about 7:31 a.m. ET. The rest of the premarket tape is extending Monday's pattern rather than reversing it — as of about 7:35 a.m. ET, SPY was roughly flat at $777.75, QQQ was down 0.69% to $740.86, and DIA was again higher, up 0.68% to $521.44.
The real calendar event today isn't a single stock, though — it's the first wave of Q3 2026 bank earnings. JPMorgan reported before the open this morning (around 6:38 a.m. ET, per 24/7 Wall St's earnings calendar), with Goldman Sachs and Wells Fargo also on today's premarket schedule alongside UnitedHealth and Johnson & Johnson, per Investrade's weekly event calendar. Going in, analyst consensus had JPMorgan around $5.93 a share on roughly $51.2 billion of revenue, per MarketBeat's earnings page — an estimate, not a result, and I couldn't independently confirm the actual reported numbers as of this writing. None of the names reporting today are held directly in either account, but the tone the banks set this morning is the real macro input the rest of the session reads from.
Home Depot (HD) in the Trading account has the tightest dated item in the book this morning. The 8 contracts of $295 calls expiring this Friday, October 16, are closer to the money than they've been all week: HD is trading around $293.67 in premarket, up about 1.05% from Monday's $290.62 close, putting the position roughly $1.33 (about 0.45%) out of the money with three trading days left. The 3 contracts of $300 calls expiring October 30 sit further out, about $6.33 (2.15%) away. The 120 HD shares themselves, at a $293.92 average cost, are essentially flat on that cost basis this morning — about 0.08% below it, the closest the position has traded to even money in recent memory.
SpaceX (SPCX), 100 shares at a $123.84 average cost in the Trading account — up about 31.0% on that cost as of this morning's premarket print — has an even tighter race. The 2 calls at the $162.50 strike, also expiring Friday, are sitting almost exactly on top of the strike: SPCX is trading around $162.28 in premarket, down about 0.70% from Monday's $163.42 close, putting the position just $0.22 (about 0.14%) out of the money. That's about as close to a coin flip as an option position gets with three trading days left, and no company-specific headline today that I could confirm to tip it either way — SPCX was among Monday's most actively traded names by volume, per Alpha Vantage, but the session move itself was modest, up 0.52%.
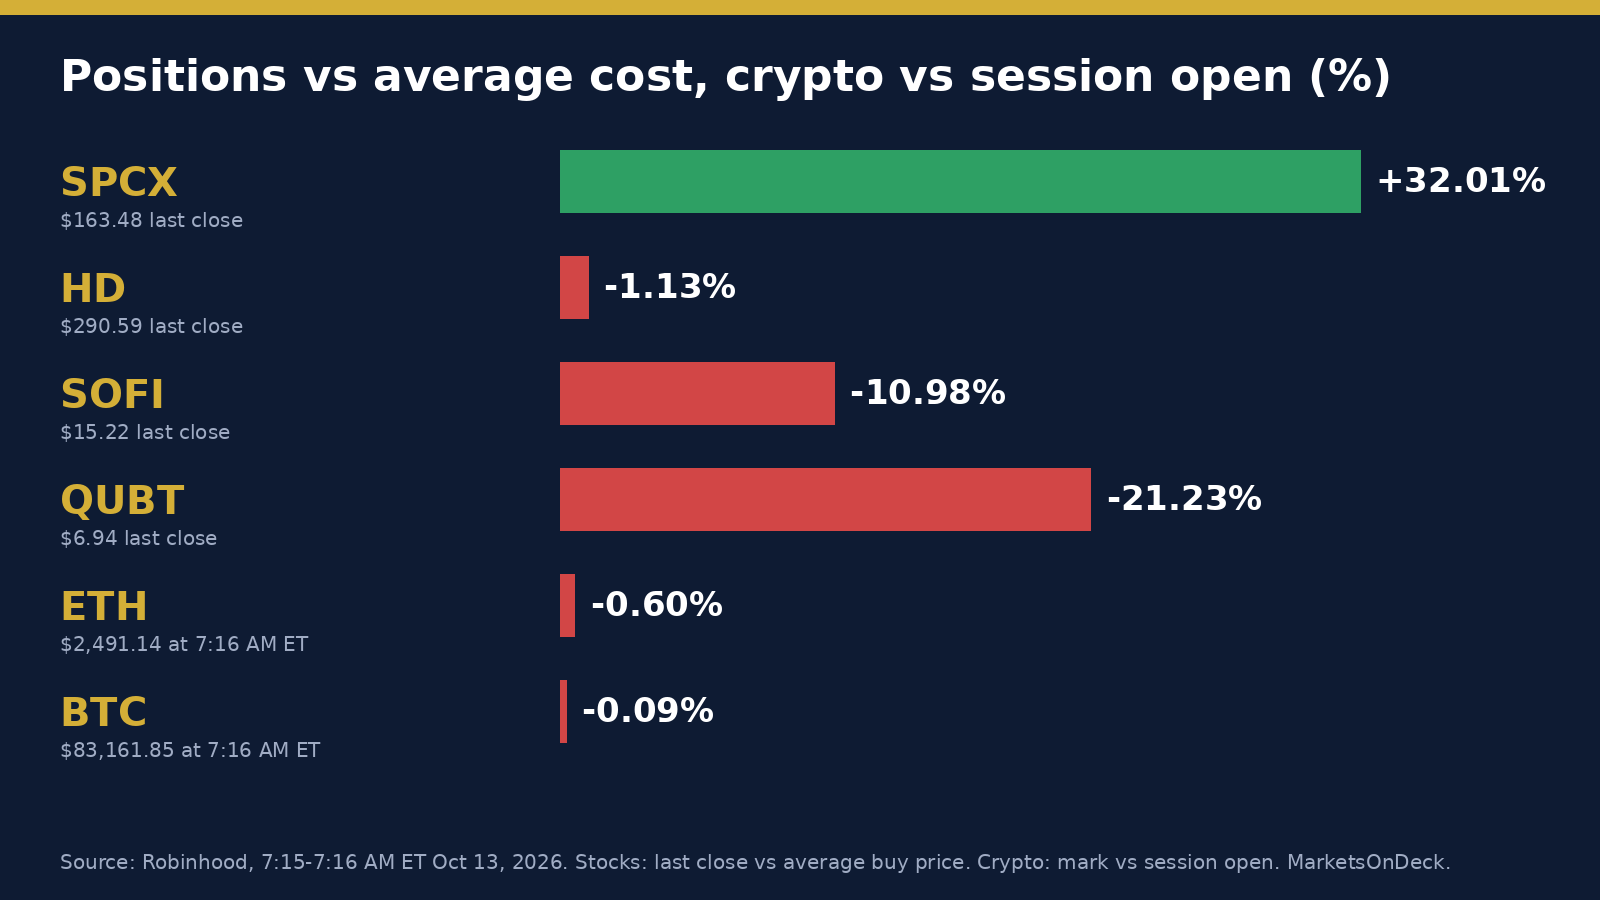
The rest of the book was quieter. SoFi (SOFI), 200 shares at a $17.10 average cost, is trading around $15.15 in premarket, down about 0.53% from Monday's close and now roughly 11.4% below cost, with no company-specific news I could confirm today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, is trading near $6.90, down about 0.43% from Monday's close and about 21.7% below cost, also quiet.
September's Consumer Price Index is now just one trading day out, due tomorrow, Wednesday, October 14 at 8:30 a.m. ET, with Producer Price Index data and September retail sales following Thursday, October 15, also at 8:30 a.m. ET, per InvestingLive's week-ahead preview. There's no Fed meeting this week — the next rate decision is still October 27–28 — so tomorrow's CPI print is the more immediate test of whether the data keeps supporting the easing case the market has been pricing in.
Futures in the Trading account: the /METV26 Micro Ether position — long 20 contracts at a 2,698.325 average entry (baseline verified September 27; the contract expires this month, October 2026) — carried a futures market value of $4,047.50 in this morning's Robinhood portfolio pull. Per-contract detail isn't available through the API, so the aggregate market value is what's reported here.
Why this matters: the real test this morning is whether the first wave of Q3 bank earnings sets a tone the rest of the market follows, or gets overshadowed by the same chip-sector pressure that's been showing up in leveraged semiconductor ETFs for over a week now — both are real, scheduled or already-in-motion events with outcomes that were genuinely unknown as this was being written. For the book, HD's and SPCX's Friday option positions are the cleanest dated items, both now sitting close enough to their strikes that this week's actual trading, not premarket noise, decides how they resolve, and KLAC's swing from above cost to below it inside one session is a reminder that sector-wide pressure can move a position meaningfully with no news specific to the name itself. None of this is a signal to expect a particular outcome in any name; it's simply what's real and dated heading into a session that includes bank earnings and a CPI print one day away.
Drafted premarket Monday, October 12, before the opening bell — the bond market is closed for Columbus Day, though NYSE and Nasdaq are trading as usual.
Oil spikes again as a deadlier new Houthi strike hits Riyadh's main airport over the weekend, equities hold dead calm in premarket, and fresh HD and SPCX call positions open right at their own strikes
$SPY closed Friday, October 9 at $778.61, up 0.60% ($4.68) — clearing the $777.88 closing high this brief has tracked since August 13 for a second time this month and leaving Thursday's chip-driven split fully behind it. $QQQ added 0.49% to $751.22, and $DIA rose 0.90% to $516.24 — a broadly higher session across all three benchmarks, a reversal of Thursday's narrower, sector-specific move.
Markets were closed over the weekend, so Friday's close is still the most recent session for the three equity benchmarks — and the real story since then happened overseas, not on a trading screen. Houthi forces struck Riyadh's King Khalid International Airport again Sunday, October 11, a day after a Saturday strike Saudi authorities said killed at least 12 people and wounded more than 300 — the deadliest attack on the kingdom in more than a decade — and the airport has stayed closed since Saturday, per Al Jazeera's Saturday coverage and its Monday follow-up. Oil is pricing the escalation: Brent crude was trading near $105 a barrel and WTI around $92 Monday morning, per Bloomberg's live oil-market coverage — a real risk premium building on top of the broader Mideast standoff this brief has tracked before, not a one-day spike.
Premarket equities aren't reflecting any of that yet, though. As of about 7:35 a.m. ET, SPY was up a slim 0.03% to roughly $778.8, QQQ was off about 0.14% to roughly $750.2, and DIA was up about 0.05% to roughly $516.5 — a quiet morning on the surface. The bond market itself is closed today for Columbus Day (NYSE and Nasdaq are trading as usual; it's only Treasuries sitting out), so there's no fresh yield print to read alongside this morning's oil move. Crypto is a touch firmer: bitcoin is up 0.29% to $83,315.43, ether up 1.64% to $2,545.15, and solana up 1.47% to $111.12, all as of about 7:32 a.m. ET.
The real, dated news in the book landed Friday rather than over the weekend. Home Depot (HD) in the Trading account picked up two new call positions Friday, October 9: 8 contracts at the $295 strike expiring this Friday, October 16, and 3 contracts at the $300 strike expiring October 30 — both added on top of the 120 HD shares at a $293.92 average cost already in the account, now down about 1.1% from that cost as HD trades almost exactly where it closed Friday, around $290.6 in premarket versus Friday's $290.74 finish. Both new contracts are out of the money for now — the $295s by about $4.4 (roughly 1.5%), the $300s by about $9.4 (roughly 3.2%) — with this week's trading, not the weekend's, deciding whether either closes the gap before expiration.
SpaceX (SPCX), 100 shares at a $123.84 average cost in the Trading account — up about 32.5% on that cost as of this morning's premarket print — also picked up a new options position Friday: 2 calls at the $162.50 strike, also expiring this Friday, October 16. That's the tightest strike in the book right now: SPCX closed Friday at $162.57, almost exactly on top of it, and is trading higher in premarket, around $164.10, which would put the position modestly in the money if that holds into the open. No new company-specific headline behind the move that I could confirm — it's trading in line with the broader book's otherwise quiet premarket tape.
The rest of the Trading account was quiet into the weekend. SoFi (SOFI), 200 shares at a $17.10 average cost, closed Friday at $15.80 and is trading lower in premarket, around $15.48 (about -2.0%), now roughly 9.5% below cost, with no company-specific news I could confirm today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed at $7.44 and is essentially flat premarket near $7.43, about 15.7% below cost. KLA Corporation (KLAC), the Agentic account's only position (about 1.0 share at a $189.93 average cost), closed Friday at $195.57 and is trading lower premarket, around $193.23 (about -1.2%), still up roughly 1.7% on cost, with nothing new specific to the name today.
The week ahead has two real dates stacked close together. JPMorgan, Citigroup, Wells Fargo, and Goldman Sachs are all scheduled to report third-quarter earnings before tomorrow's open, Tuesday, October 13 — the first real look at how the big banks are reading the same rate and credit environment this brief has tracked all month. September's Consumer Price Index follows Wednesday, October 14, with Producer Price Index data a day after that, October 15, both at 8:30 a.m. ET; the Fed's next rate decision is still October 27–28.
Why this matters: a deadlier new strike on Saudi Arabia's main airport over the weekend is pushing oil higher before the bell, and it's the kind of event that doesn't need a single stock's earnings to move the broader tape — it raises the cost of the macro backdrop every position in this book sits inside, whether or not that shows up in premarket prices yet. For the book itself, the real news isn't a reaction to the weekend at all — it's two new option positions on HD and one on SPCX opened Friday, each sitting close enough to its own strike that this week's actual trading, not the weekend's, decides how they resolve. None of this is a signal to expect a specific move in any name; it's simply what's real and dated heading into a week that also brings big-bank earnings and September's CPI before Friday's close.
Drafted premarket Friday, October 9, before the opening bell.
HD's last option contract finally clears its strike on expiration day itself, a chip-specific slide pulls Thursday lower while the Dow holds up, and SPCX keeps climbing without a new headline behind it
$SPY closed Thursday, October 8 at $773.77, down 0.44% ($3.45) — a second straight loss that leaves the index about 0.5% below the $777.88 closing high this brief has been tracking since August 13. $QQQ fell much harder, down 1.29% to $747.92, while $DIA actually gained 0.16% to $511.83 — a real split between the three benchmarks rather than a uniform pullback, with the Nasdaq-100 doing essentially all of Thursday's damage.
That split traces to one sector, not a broad macro move. Intel fell 5.22% to $107.22 and Nvidia fell 2.85% to $230.70 Thursday, and the scale of the chip-specific selling shows up even more clearly in the leveraged semiconductor ETFs: the 3x-bullish SOXL dropped 10.33% to $142.49 while the 3x-bearish SOXS rose 10.21% to $33.78, per Alpha Vantage's Thursday close data. I couldn't confirm a single headline tying Thursday's chip slide to a specific catalyst, but the fact that DIA actually closed higher the same session argues against a broad market-wide story — this reads as a sector-specific move, not the oil-and-yields macro thread flagged here Wednesday and Thursday.
Premarket this morning is bouncing back across all three benchmarks rather than extending Thursday's split: as of about 7:34 a.m. ET, SPY was up 0.46% to $777.29, QQQ up 0.82% to $754.04, and DIA up 0.12% to $512.47. Crypto isn't joining the bounce, though — bitcoin is up a slim 0.12% to $82,524.60, but ether is down 1.74% to $2,491.09 and solana down 2.71% to $110.01, all as of about 7:31 a.m. ET — a softer tape than equities' rebound, not a confirmation of it.
Home Depot (HD) in the Trading account has the one real, dated event in the book this morning: the single $287.50 call contract left after this week's trims — down from the 5 flagged here Tuesday to just 1 — expires this afternoon at 3:30 p.m. ET, and for the first time since this position was opened September 30, HD is trading solidly above that strike ahead of the bell. HD closed Thursday at $295.47, up fractionally from Wednesday, and is trading around $295.93 in early premarket — about $8.43 above the $287.50 strike, roughly 2.9% in the money. Barring a sharp reversal before the close, this is the first session the running HD-options thread here resolves in the money rather than racing the clock toward expiration. The shares themselves, 120 at a $293.92 average cost, are for the first time in this brief's recent entries trading above cost too, both at Thursday's close and in this morning's premarket print.
The rest of the Trading account was quieter. SpaceX (SPCX), 100 shares at a $128.32 average cost, closed Thursday at $160.57, up about 25.1% on cost, and jumped a further 4.3% in premarket to $167.54 — now up roughly 30.6% on cost — without any new company-specific headline I could confirm for today. The most recent confirmed catalyst is still Monday's Morgan Stanley reiteration and $300 price target flagged here earlier this week, which had already pushed the stock up about 18% for the month through Tuesday; today's premarket pop extends that move rather than restarting it on anything new. SoFi (SOFI), 200 shares at a $17.10 average cost, closed Thursday at $15.61, about 8.7% below cost, and is trading near $15.74 premarket, still about 8.0% below cost; the company confirmed this week it will report Q3 2026 results and hold its earnings call on Tuesday, October 27 at 8 a.m. ET, per its own investor-relations announcement — the next real scheduled catalyst for the name. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed Thursday at $7.45, about 15.4% below cost, and is trading near $7.57 premarket, about 14.1% below cost, with nothing new specific to the name today.
KLA Corporation (KLAC), now the Agentic account's only position (about 1.0 share at a $187.15 average cost), was one of the few chip-equipment names that didn't participate in Thursday's sector-wide slide — it closed essentially flat, down just 0.1%, to $196.72, about 5.1% above cost, even as Intel and Nvidia each fell sharply the same session. It's extending that relative strength into this morning, trading around $201.00 premarket, about 7.4% above cost — still no fresh company-specific news behind the move, but a real divergence from the rest of the chip trade worth having in view.
September's Consumer Price Index is still on the calendar for Wednesday, October 14, with Producer Price Index data following October 15, both at 8:30 a.m. ET — five and six trading days out, respectively, and still the next scheduled data point likely to move the broader tape; the Fed's next rate decision remains October 27–28.
Why this matters: Thursday's real story was narrower than it first looked — a chip-specific slide severe enough to show up as double-digit moves in leveraged semiconductor ETFs, sitting on top of a Dow that actually closed higher the same day, which is a different kind of session than the broad oil-and-yields selloff this brief tracked earlier in the week. For the book, HD's options are the cleanest dated item today: a position trimmed down to a single contract that spent weeks racing the clock out of the money is, for the first time, sitting above its strike on the actual day it expires — worth logging because the outcome is still unknown as this is being written, not because it predicts anything about how it resolves. SPCX's continued climb without a fresh headline behind it, and KLAC's resilience through a sector-wide chip selloff, are both real and both worth knowing, but neither is a reason to read more into today's tape than the numbers themselves support.
Drafted premarket Thursday, October 8, before the opening bell, as oil and Treasury yields pushed broader markets lower in early trading.
Oil and yields spike again on the Iran standoff, pulling $SPY back below its old record, and HD's Friday calls get one more add with two trading days left
$SPY closed Wednesday, October 7 at $777.34, down 0.22% ($1.75) — slipping back below the $777.88 closing high this brief has been tracking since August 13, just one session after Tuesday's $779.42 finish had cleared it for the first time. $QQQ fell a similar 0.25% to $757.78, and $DIA dropped 0.69% to $511.00 — a second straight day where the Dow proxy lagged the other two benchmarks after briefly leading them Monday.
The cause wasn't anything company-specific. Oil and Treasury yields drove Wednesday's pullback and are driving this morning's premarket weakness too, as the on-again standoff between the U.S. and Iran flared back up — the same conflict that has periodically spiked crude and rattled equities since the two countries' militaries first exchanged fire in February. Brent crude pushed back above $104 a barrel and the 10-year Treasury yield rose to around 5.34%, per Bloomberg's Wednesday markets coverage, and a separate Thursday outlook from Tickmill flagged the same mechanism working through today's session — surging crude and renewed Middle East tension pressuring global equities broadly, not any single name or sector. As of about 7:35 a.m. ET, SPY was down a further 0.51% to $773.27, QQQ off 0.74% to $752.13, and DIA down 0.90% to $506.43 — all three benchmarks extending Wednesday's loss rather than bouncing from it.
Crypto is reading the same risk-off tape rather than shrugging it off: bitcoin is down 1.46% to $82,486.68, ether off 1.56% to $2,537.23, and solana down a sharper 3.17% to $113.58, all as of about 7:30 a.m. ET — moving with this morning's equity weakness, not apart from it.
Home Depot (HD) in the Trading account had the one real, dated development in the book this morning. The $287.50 calls expiring tomorrow, Friday, October 9, grew to 6 contracts, another add on top of the 5 flagged here Wednesday — with two trading days left, including today, before expiration. HD itself is trading lower in early premarket, around $283.56, down from Wednesday's $285.77 close and further from the $287.50 strike than Tuesday's close came; the stock hasn't managed to close above that level since this contract was opened. HD shares themselves, 120 shares at a $293.92 average cost, are now about 3.5% below cost, giving back some of this week's recovery as the broader tape turns lower.
The rest of the book moved with the tape rather than against it. SpaceX (SPCX), 100 shares at a $128.32 average cost, is trading around $166.40 in early premarket, down from Wednesday's $167.60 close but still up about 29.7% on cost — no company-specific news behind the move, just the same risk-off mood. KLA Corporation (KLAC), now the Agentic account's only position (about 1.0 share at a $187.15 average cost), is down further to $192.11 premarket from Wednesday's $196.83 close, still up roughly 2.6% on cost. SoFi (SOFI), 200 shares at a $17.10 average cost, is trading near $15.38, down from $15.66, about 10.1% below cost. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, is near $7.54 premarket, down from $7.62, about 14.4% below cost — nothing new specific to either name today.
The next scheduled data point that could reshape this debate is still more than a week out: September's Consumer Price Index lands Wednesday, October 14, with Producer Price Index data following the next day. Until then, oil and the Iran standoff look like the more immediate driver of the tape.
Why this matters: a macro story — oil and yields reacting to a geopolitical conflict, not a change in any individual company's outlook — is pulling essentially every number in this brief lower together this morning, the book included. That's a different kind of morning than one driven by an earnings surprise or an analyst call: it says less about any specific name's prospects and more about how much risk appetite the market has left while a real conflict keeps resurfacing in the price of oil. For the book, HD's options are the one mechanical exception — a position with a real deadline tomorrow, getting bigger rather than smaller as that deadline approaches, worth watching simply because it's logged here before anyone knows how it resolves, not after.
Drafted premarket Wednesday, October 7, before the opening bell, ahead of today's FOMC minutes release at 2:00 p.m. ET.
$SPY closes at a fresh record while chips and crypto sell off on rate-cut doubts, and HD's short calls get trimmed to 5 contracts two days before expiration
$SPY closed Tuesday, October 6 at $779.42, up 0.59% ($4.59) — a fresh closing high, finally clearing the $777.88 record this brief has been tracking since it was set August 13. $QQQ added 0.51% to $760.04, and $DIA rose 0.48% to $514.55 — a broadly higher session on the surface, with growth and the Dow proxy moving together rather than splitting the way they have through most of the past month.
Underneath that headline number, the chip-equipment group had a rough day. KLA Corporation (KLAC) fell about 4.5% to close at $197.46, down from Monday's $206.85, as part of a broader semiconductor selloff that also hit Lam Research, Applied Materials, ASML, Micron, and AMD — investors trimming exposure to a group whose benchmark ETF had run up more than 80% in the first half of the year, on renewed valuation and rate concerns rather than anything specific to KLA's own demand picture, per Yahoo Finance's Tuesday coverage. KLAC is now the only position left in the Agentic account — about 1.0 share at a $187.15 average cost after this week's partial sale — and while the drop stings on the day, the position is still up about 5.5% on that cost basis given how cheap it was bought.
Crypto picked up the same rate-anxiety thread overnight rather than shrugging it off: bitcoin is down 3.00% to $83,645.91, ether down 5.19% to $2,572.76, and solana down 2.60% to $117.18, all as of about 7:30 a.m. ET — part of a market-wide liquidation wave topping $550 million over the past day tied to fading Fed rate-cut odds, a stronger dollar, and rising oil prices and Treasury yields, per FXStreet's Wednesday coverage.
That rate question gets its first real test today. The Fed releases minutes from its September 15–16 meeting — the one that delivered the first hike since 2023 — at 2:00 p.m. ET, the next real look at how the committee is squaring that decision against a jobs report since revised down by a net 60,000 jobs across July and August. The next scheduled inflation read, September's CPI, isn't due until Wednesday, October 14.
Home Depot (HD) in the Trading account had its own real, dated development: the $287.50 calls expiring this Friday, October 9, are down to just 5 contracts, a sharp cut from the 30 flagged here Monday. The trim came as HD actually tested the strike — Tuesday's intraday high was $287.14, just 36 cents away, before the stock settled back to a $286.69 close, up 1.97% on the day. HD shares themselves, 120 shares at a $293.92 average cost, are now about 2.5% below cost, continuing to claw back after last week's slide; the options side has three trading days left to find out whether the much smaller position finishes in the money.
The rest of the book was quieter. SpaceX (SPCX), 100 shares at a $128.32 average cost in the Trading account, closed Tuesday up 0.49% to $171.92 — still the most actively traded name in the book by volume — and is trading lower in early premarket, around $167.70, in line with the broader pullback in higher-valuation, rate-sensitive names rather than anything company-specific; the position is still up about 34% on cost. SoFi (SOFI), 200 shares at a $17.10 average cost, closed down 1.0% to $15.76, now about 7.8% below cost, with no company-specific news I could confirm today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed at $7.86, about 10.8% below cost, also with nothing new specific to the name today.
Why this matters: a fresh index-level high sitting on top of a real selloff in chips and crypto is itself the story this morning — the kind of split that usually means the market hasn't actually resolved the rate argument it's been having all week, it's just having it in different places at once. Today's FOMC minutes are the first real look at whether that argument has real support behind it. For the book, the HD calls are a smaller, more mechanical version of the same clock: three trading days left on a position that just got cut by roughly 83%, still testing a strike it hasn't yet closed above — not a reason to read anything into where it finishes, just the real state of a real position as the deadline gets close.
Drafted premarket Tuesday, October 6, before the opening bell.
Morgan Stanley goes bullish on SpaceX and cautious on KLA in the same week, and the book's own trims on both — plus a full exit from SPCH — land right alongside it
$SPY closed Monday, October 5 at $774.80, up 0.67% ($5.16) — within about 0.4% of the $777.88 closing high it set August 13, effectively erasing last week's pullback in one session. $QQQ added 0.85% to $755.98, and $DIA rose a smaller 0.19% to $512.07 — growth again setting the pace over the Dow, the same pattern that's shown up through most of the past month. Crypto is holding close to flat into this morning: bitcoin is down a slim 0.01% to $86,186.52, ether off 0.12% to $2,714.30, and solana down 0.51% to $120.16, all as of about 7:30 a.m. ET — a quieter premarket than Monday's own session delivered.
Today's calendar is light on top-tier data but not empty: the government's August trade balance report is due, alongside a 3-year Treasury note auction and scheduled remarks from Fed governors John Williams and Michelle Bowman, per XTB's Tuesday economic-calendar preview. None of that is the kind of release that moves the tape on its own, but it sets up a real one tomorrow: the Fed releases minutes from its September meeting — the one that delivered the first hike since 2023 — Wednesday, October 7 at 2:00 p.m. ET, the next real look at how the committee is squaring that decision against a jobs report since revised down by a net 60,000 jobs across July and August. The following inflation read, September's CPI, isn't due until Wednesday, October 14.
The real thread this morning is one analyst desk reaching opposite conclusions on two names actually held across both accounts, in the same week. Morgan Stanley's Adam Jonas reiterated an Overweight rating on SpaceX (SPCX) Monday with a $300 price target, arguing in a note titled "Cheap and Getting Cheaper" that the stock's headline multiple understates the value building in Starlink, Starship, and AI compute ahead of the next Starship flight, per Benzinga's Monday coverage. SPCX itself jumped 7.6% Monday to close at $171.09, implying roughly 75% further upside to Jonas's target from that close. I hold the name directly through the Trading account, now 100 shares at a $128.32 average cost after a partial sale trimmed the position from the 110 shares flagged here Monday — up about 33.3% on the new cost basis as of Monday's close.
The same firm went the other way on KLA Corporation (KLAC) this morning: Morgan Stanley cut its price target to $227 from $253 while keeping its Overweight rating, trimming the multiple it applies to the stock to 28 times from 36 times even as it raised its own calendar-2027 revenue forecast for KLA to $21.4 billion from $20.4 billion and its EPS estimate to $6.77 from $6.23, per a Tuesday note recapped by Rallies — a valuation reset, not a change in the underlying demand case, the same distinction this brief has drawn on other KLA notes before. The Agentic account made its own real move on the name this week: KLAC is now down to roughly 1 share at a $187.15 average cost, a sharp cut from the 2.28 shares at $189.93 flagged here Monday — a real partial sale, though the average cost dropping too is more than a simple partial sale would typically produce, worth logging as-is rather than explained away. KLAC closed Monday at $206.85, putting the smaller position about 10.5% above its new cost basis. The Agentic account's SPCH, the fund targeting twice SpaceX's daily move and a position flagged here gaining over 15% just Monday, no longer shows as an open position in this morning's account check — fully closed out rather than carried into today, leaving KLAC as the account's only remaining position.
Home Depot (HD) in the Trading account is unchanged on the share side at 120 shares and a $293.92 average cost, with HD closing Monday at $281.15 and trading a touch higher premarket at $283.00 — still about 4.3% below cost. The options side kept growing, though: the $287.50 calls expiring this Friday, October 9, are now 30 contracts, up from the 20 flagged here October 2 — another add, not a new position, and one now racing a real deadline. With three trading days left and HD sitting $6.35 out of the money, the position needs a real move higher by Friday's close to finish in the money.
The rest of the book was quiet. SoFi (SOFI), 200 shares at a $17.10 average cost in the Trading account, closed Monday at $15.92, down about 6.9% from cost, with nothing new since this year's stablecoin rollout with Mastercard and heading into its own Q3 earnings date, October 27. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, also in the Trading account, closed Monday at $7.94, down about 9.9% from cost, with no fresh company-specific news since last week's Dirac-3S announcement.
Why this matters: the same analyst desk reaching opposite conclusions on two names in the book in the same week — bullish on SpaceX's longer-dated growth story, more cautious on KLA's near-term multiple despite raising the underlying earnings numbers — is a reminder that a price-target change is a read on valuation, not a verdict on the business. The book's own trims on both KLAC and SPCX, plus the SPCH exit, are already real moves logged here as they happen rather than explained afterward. None of this is a signal to act on any position differently; it's simply what the real numbers and the real account activity said heading into tomorrow's FOMC minutes.
Drafted premarket Monday, October 5, before the opening bell.
A weak jobs report lands and the rally keeps going anyway, SPCX's launch tripleheader pays off, and KLAC shrugs off three analyst target cuts
$SPY closed Friday, October 2 at $770.10, up 0.80% ($6.11) — a second straight gain that leaves the index about 1.0% below the $777.88 closing high it set August 13. $QQQ added 1.05% to $749.80, and $DIA rose 0.55% to $511.42 — tech again out in front of the Dow, a pattern that's shown up through most of the past month. Crypto is extending the same risk-on tone into this morning: bitcoin is up 1.02% to $86,175.91, ether up 0.72% to $2,719.24, and solana essentially flat, down 0.29% to $120.86, all as of about 7:31 a.m. ET. Markets were closed over the weekend, so Friday's close is still the most recent session for the three equity benchmarks.
The real story behind that rally is the one number that came in sharply short. September's jobs report, released Friday morning, showed nonfarm payrolls up just 29,000 against a consensus of roughly 84,000, with the unemployment rate ticking up to 4.2%, per the Bureau of Labor Statistics and CNBC's Friday coverage. August's initial count was revised down to 133,000, and July flipped from a reported gain to an outright loss of 10,000 — a net 60,000 fewer jobs than previously reported across the two months. Wage growth stayed modest, up 0.1% month-over-month and 3.0% year-over-year. A miss that size would normally read as bad news on its own, but equities rallied anyway: the market's framing was that a softening labor market makes Fed easing more likely rather than less, the same logic this brief has been tracking heading into the October 27–28 meeting.
This week's calendar is lighter than the one that just ended, but not empty: the ISM services PMI for September is due today, the Fed releases minutes from its September meeting Wednesday, October 7, and initial jobless claims follow Thursday. The next broad inflation read, September's CPI, isn't until Wednesday, October 14 — a week and a half out, not this week's story, but close enough to keep in view.
SpaceX (SPCX) in the Trading account, 110 shares at a $127.22 average cost, was the one real standout in the book: the stock closed Friday up 7.38% to $159.00, putting the position about 25.0% above cost. The company pulled off a genuine operational feat Thursday into Friday — three separate launches in roughly a 13-hour span, something SpaceX has done only once before. Crew-13 lifted off from Cape Canaveral carrying four astronauts to the International Space Station on the fastest Dragon trip yet; the Transporter-18 rideshare mission followed, carrying 130 payloads including a prototype satellite for Google's Project Suncatcher AI constellation; and a Falcon Heavy closed out the day just before midnight with the classified NROL-97 mission for the National Reconnaissance Office, per Space.com's and Yahoo Finance's coverage. The Agentic account's SPCH, the fund targeting twice SpaceX's daily move, read the same day even more sharply — up 14.58% Friday to $11.08, putting that position about 35.8% above its $8.16 cost.
KLA Corporation (KLAC), the Agentic account's other position (2.28 shares at a $189.93 average cost), closed Friday up 3.33% to $207.01, now about 9.0% above cost — a real gain that came despite, not because of, this week's sell-side tone. Three firms cut their price targets on the name this week: Stifel to $250 from $270 (still Buy, citing a valuation reset rather than a change in the demand story, per Investing.com's coverage of the note), Wells Fargo to $245 from $305 (Overweight), and UBS to $200 from $215 (Neutral) — all three keeping their underlying ratings intact even as they trimmed targets. The stock shrugging off three separate cuts in the same week it gained is itself worth having in view, whatever it ends up meaning for the name.
The rest of the book was quieter and unchanged position-wise from Friday's entry. SoFi (SOFI), 200 shares at a $17.10 average cost in the Trading account, closed down 0.45% to $15.77, about 7.8% below cost, with nothing new today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed down 2.15% to $8.21, about 6.8% below cost, also quiet. Home Depot (HD), 120 shares at a $293.92 average cost, closed Friday at $282.85, up slightly (about 0.14%) from Thursday's $282.46 — still about 3.8% below cost, with premarket trading this morning at $283.89, a touch higher, nothing dramatic.
Why this matters: Friday's jobs miss is the kind of data point that cuts both ways — weak enough to raise real concern about the labor market, read by equities as support for the Fed easing rather than holding, which is why the rally and the bad number arrived together instead of canceling out. For the book, SPCX and its leveraged SPCH position are the week's clearest evidence that a real operational catalyst — three launches in one day — can still move a stock on top of whatever the broader tape is doing, while KLAC's gain through three analyst target cuts this week is a reminder that sell-side price targets and near-term price action don't always move together. None of this is a signal to act on any position differently; it's simply what the real numbers said heading into this week.
Drafted premarket Friday, October 2, before the opening bell and before this morning's jobs report.
The jobs report this brief has been counting down to finally lands, crypto is running well ahead of stocks premarket, and HD keeps getting bigger into its own slide
$SPY closed Thursday, October 1 at $764.39, up 0.23% ($1.76) — a second straight gain that leaves the index about 1.7% below the $777.88 closing high it set August 13. $QQQ added 0.37% to $742.51, while $DIA was nearly flat, up 0.03% to $508.71 — a quieter, more synchronized session than most of this week's, with none of the three benchmarks doing much work in either direction.
Today is the date this brief has been flagging for two weeks: the September jobs report is due at 8:30 a.m. ET, with the number still unreleased as of this writing. Given the funding fights that have hit Washington more than once this year, it was worth actually checking whether today's release was even still on — it is: Congress passed a stopgap funding bill in September that keeps the government open through December 11, so unlike a shutdown year, there's no funding lapse standing between this morning and the report, per CBS News' coverage of the vote. That just means the number is coming on schedule — it says nothing about what the number itself will say.
Premarket is mostly just waiting on it: as of about 7:35 a.m. ET, SPY was up roughly 0.5% to $767.88, QQQ up about 0.6% to $747.10, and DIA up about 0.6% to $511.56 — a mild, unified lean higher ahead of the number, nothing dramatic. Crypto is not waiting the same way: bitcoin is up 3.1% to $86,484.28, ether up 1.47% to $2,745.60, and solana up 3.46% to $122.01, all as of about 7:31 a.m. ET — a real divergence from the muted equity premarket, not just crypto's usual higher volatility.
Home Depot (HD) in the Trading account keeps growing into its own decline rather than away from it. The position is now 120 shares at a $293.92 average cost, up from the 100 shares at $297.03 flagged here Thursday — another add. HD itself closed Thursday at $282.46, down about 0.7% from Wednesday, leaving the position down about 3.9% from the new average cost. A Trefis piece published early this morning put a number on the slide: HD is down 12.6% over the past month with no single clear catalyst behind it, and its operating margin has compressed over the past three years, a combination the piece frames as a genuinely riskier setup than the stock's history of recovering from past shocks would suggest, per Trefis. The options side grew too: the $287.50 calls expiring October 9 are now 20 contracts, up from the 10 flagged Wednesday (both tranches opened September 30) — another add, not a new position. Separately, the two short-dated contracts flagged here Thursday as racing today's jobs number into expiration — HD's $300 calls and TSLA's $365 calls, both expiring today — are no longer showing as open positions in this morning's account check; both were closed out ahead of the report rather than carried into it.
The Agentic account's CCL call, flagged here Thursday as having a sell order queued against it, is the same story — no longer an open position this morning, closed before today's session rather than carried into Carnival's next move.
KLA Corporation (KLAC), the Agentic account's other position (2.28 shares at a $189.93 average cost), closed Thursday up 2.52% ($4.91) to $199.84, putting the position about 5.2% above cost. A research note out early this morning tied KLA's inspection and metrology equipment to the broader AI chip manufacturing supply chain that TSMC and others rely on to improve yield on complex processors — the same AI-capex thesis this brief has covered on KLA before, reinforced rather than replaced by today's note, per a Substack research piece whose specific revenue figures aren't independently verified here.
Quantum Computing (QUBT), 500 shares at an $8.81 average cost in the Trading account, has real, dated news of its own: the company announced Dirac-3S on Thursday, an upgraded version of its quantum optimization machine built for commercial deployment, scaling to nearly 9,980 variables with a modular architecture, with first customer shipments expected in November, per HPCwire. The stock itself hasn't reacted yet — QUBT closed Thursday down 0.83% to $8.38, leaving the position down about 4.9% from cost, with the news still fresh enough that the market may not have fully priced it in.
The rest of the book is quieter. SpaceX (SPCX) in the Trading account is now 110 shares at a $127.22 average cost, down from 153 shares at $124.25 flagged earlier this week — a partial sale, not a new catalyst-driven move. SPCX closed Thursday down 1.72% to $148.26, still up about 16.5% on the new cost basis. The Agentic account's SPCH, the fund targeting twice SpaceX's daily move, is unchanged at 4 shares and an $8.16 average cost, closing Thursday down 3.48% to $9.70, up about 18.9% on cost. SoFi (SOFI), 200 shares at a $17.10 average cost, closed Thursday up 0.83% to $15.85, still down about 7.3% from cost, with nothing new since the Form 144 filings covered earlier this week.
Once today's number is out, the next scheduled data point worth watching is the September Consumer Price Index on Wednesday, October 14, with Producer Price Index data following October 15 and the Fed's next rate decision due October 27–28.
Why this matters: today's actual catalyst is the 8:30 a.m. jobs number itself, not anything premarket is doing ahead of it — a weak print keeps the case for a Fed pause intact heading into the October 27–28 meeting, a strong one reopens the hike debate, the same framing this brief has carried for two weeks waiting for this exact morning to arrive. For the book, HD is the one position where the math keeps getting more lopsided by the day: a stock down double digits over the past month, met with repeated adds on both the shares and the options side rather than a step back — worth having in view specifically because it's logged here before anyone knows whether that pattern ages well or badly, not after.
Drafted premarket Thursday, October 1, before the opening bell.
HD's slide deepens as the position grows, and two short-dated calls now race Friday's jobs report
$SPY closed Wednesday, September 30 at $762.59, down 0.21% ($1.61) — a second straight session pulling the index further from the $777.88 closing high it set August 13, now about 2.0% below it. $QQQ held up better, up 0.25% to $739.80, while $DIA lagged hardest of the three, down 0.91% to $508.21 — the same tech-outperforms-Dow pattern that's shown up through most of the past month, just with the Dow's leg wider than usual.
There's no single overnight headline driving this morning. A scan of today's broader financial-news feed turns up mostly single-name analyst notes unrelated to the book (a Scotiabank call on CMS Energy, Jefferies on Teledyne, Goldman trimming its T-Mobile target) rather than anything macro. Crypto is reading the quiet the same way: bitcoin is essentially flat, down 0.06% to $83,825.10, ether up 0.02% to $2,696.80, and solana off 1.49% to $117.69, all as of about 7:31 a.m. ET. With the cash session not yet open, there's no premarket print yet on SPY, QQQ, or DIA to report.
The real test of the week lands tomorrow, not today: the September jobs report is due Friday, October 2 at 8:30 a.m. ET, with consensus looking for roughly 90,000 jobs added, down sharply from August's 162,000, per Kiplinger's economic-calendar preview — a weak print would cement the case for a Fed pause, a strong one would revive October hike talk. That date turns out to matter for the book directly too, not just the index level, which is where this morning's real story is.
Home Depot (HD) in the Trading account is now 100 shares at a $297.03 average cost, up from 75 shares at $300.70 — an add, logged here plainly. It came against a stock that kept sliding: HD closed Wednesday at $284.49, down 1.23% ($3.55) from Tuesday's $288.04, a fresh low below the $289.10 level flagged in this brief Tuesday, leaving the position down about 4.2% from the new average cost. There are also two HD call positions open on top of the shares: 10 contracts at the $287.50 strike expiring October 9 (opened Wednesday) and 2 contracts at the $300 strike expiring tomorrow, October 2 (opened September 23). The $300s are now $15.51 out of the money with one trading day left — a real chance they expire worthless unless HD rallies roughly 5.5% by Friday's close, worth saying plainly rather than leaving out.
TSLA exposure in the book is options-only: 7 calls at the $365 strike, also expiring tomorrow, October 2 (the position was built in pieces starting September 28). TSLA closed Wednesday at $354.81, up 0.56%, leaving the $365s about $10.19 out of the money with the same one-day runway as HD's $300s — both now racing the same Friday close, the same morning the jobs report lands before the bell. TSLA also picked up two real, dated headlines this week: a wrongful-death lawsuit filed in Travis County, Texas today alleges a Model 3 "suddenly and unexpectedly accelerated" before a fatal crash, per Yahoo News' Thursday coverage — Tesla has denied similar unintended-acceleration claims before, and federal safety findings have typically pointed to driver input rather than a vehicle defect in past cases — and separately, the SEC cleared Tesla's board-crafted "auto-vote" proxy mechanism for wider use Tuesday, a governance story that drew criticism from some shareholder activists. Neither is a reason to expect a specific move in the stock; both are real and worth having in view given the options expiring into tomorrow's close.
The Agentic account's Carnival (CCL) call — 1 contract at the $25 strike expiring October 16, opened back on September 2 — is sitting on real, verified gains from this week's news rather than speculation. Carnival reported record third-quarter results Tuesday, including $1.9 billion in net income (an all-time Q3 high) and $7.6 billion in customer deposits (also a record, up 7% year-over-year), and said 2027 is already half-booked at record occupancy and pricing — the stock jumped as much as 13% on the report, per FX Leaders' Wednesday coverage. Morgan Stanley followed Wednesday by raising its price target on the name to $32.50 from $31, keeping an Overweight rating, per Yahoo Finance. CCL itself gave back some of the pop Wednesday, closing at $24.54, down 2.27% ($0.57) from Tuesday's $25.11 — just under the $25 strike. There's currently a sell order queued against the single contract; whatever happens with it will be logged here after the fact, not decided here.
The rest of the book is quieter. SpaceX (SPCX), 153 shares at a $124.25 average cost in the Trading account, closed Wednesday up 1.01% to $150.74, still up about 21.3% on cost; the Agentic account's SPCH, the fund targeting twice SpaceX's daily move, is now down to 4 shares from 8 (average cost unchanged at $8.16, consistent with a partial sale rather than any repricing), and closed at $10.04, up about 23.0% on its remaining cost basis. The only SPCX-adjacent item today is a routine Form 4 ownership-disclosure amendment from insider Antonio Gracias, filed Wednesday — nothing that reads as material. KLA Corporation (KLAC), the Agentic account's other position (2.28 shares at a $189.93 average cost), closed Wednesday down 1.16% to $194.25, still up about 2.3% on cost, with nothing new since Tuesday's AI-backlog story covered here. SoFi (SOFI), 200 shares at a $17.10 average cost, closed at $15.71, down about 8.1% from cost, quiet since Monday's insider Form 144 filing. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed at $8.44, down about 4.2% from cost, still shadowed by Monday's disclosure of a self-dealing investigation into company officers — unresolved, with no update today.
Why this matters: tomorrow's jobs report is the real catalyst this week, and it lands at 8:30 a.m. before two short-dated option positions in the book — HD's $300 calls and TSLA's $365 calls — both expire that same afternoon, meaning Friday's number has a direct, dated effect on two live positions rather than just the index level. For the rest of the book, HD's equity add came while the stock kept making fresh lows, and CCL's real earnings-driven gain is the week's one unambiguous win worth noting alongside it — the point of logging both here, win or loss, is the same reason this brief exists at all: a timestamp before the outcome, not after it.
Drafted premarket Wednesday, September 30, before the opening bell — and before this morning's PCE report.
PCE day finally arrives, and KLA's AI-backlog number is the one real move in a quiet premarket
$SPY closed Tuesday, September 29 at $764.61, down 0.13% ($1.00) — a second straight loss that leaves the index about 1.7% below the $777.88 closing high it set August 13. $QQQ actually gained, up 0.24% to $738.31, while $DIA slipped in line with SPY, down 0.20% to $512.98 — a split session, quieter than Monday's synchronized decline but the same tech-holds-up-better pattern that's shown up through most of the month.
This morning is the one every recent entry here has been counting down to. The Bureau of Economic Analysis releases the August Personal Consumption Expenditures price index — the Fed's own preferred inflation gauge — at 8:30 a.m. ET, alongside the ADP private-payrolls report and the final read on second-quarter GDP, all landing in the same half hour. Forex-market previews of the release, including BabyPips' event guide, have consensus looking for headline PCE up around 0.4% month-over-month (3.7% year-over-year) and core PCE up 0.3% (3.3% year-over-year) — estimates, not the actual print, since this is being written before the number exists. It's the first real data test of whether the disinflation path holds up against a bond market that spent last week pushing the 10-year Treasury yield to a 19-year high and the 30-year to its highest level since 2004.
Premarket trading is holding almost perfectly still ahead of it: as of about 7:35 a.m. ET, SPY, QQQ, and DIA were each within a few hundredths of a percent of Tuesday's close — a rare morning where none of the three benchmarks has a premarket story of its own, a market waiting rather than reacting. Crypto is reading the same caution instead of diverging from it, which is itself worth noting: bitcoin is down 0.71% to $83,727.01, ether off 1.50% to $2,690.41, and solana down 0.60% to $119.40, all as of about 7:32 a.m. ET — a small, orderly pullback, not the kind of split from equities this brief has flagged on other mornings.
The one genuine mover in the book has nothing to do with this morning's data. KLA Corporation (KLAC), the Agentic account's other position (2.28 shares at a $189.93 average cost), closed up 4.03% Tuesday to $196.53 after the company disclosed its order backlog has surged to $12.57 billion, driven by AI-infrastructure-linked demand for its process-control equipment — the same buildout this brief has tied KLA to before, now showing up as a concrete number rather than a thesis, with analysts framing it as keeping pace with rivals Applied Materials and ASML in the same race. KLAC is down slightly premarket, to about $195.00 as of about 7:34 a.m. ET, putting the position roughly 2.7% above cost — Tuesday's real gain mostly intact even as the stock gives a small piece of it back this morning.
The rest of the Trading account skewed the other way. Home Depot (HD), 75 shares at a $300.70 average cost, had fallen to a 52-week low of $289.10 by mid-afternoon Tuesday, per Investing.com — roughly 30% below its high and enough to push its Relative Strength Index into oversold territory — then kept sliding into the close, finishing the session even lower at $288.04. Analysts are split on what that means: Stifel reiterated a Hold rating on the name this week, while UBS is still at Buy. HD is little-changed premarket at $287.99, leaving the position down about 4.2% from cost, with no company-specific catalyst behind the move beyond the technical level itself.
SoFi (SOFI), 200 shares at a $17.10 average cost also in the Trading account, is still digesting this week's Form 144 filings disclosing insider Kelli Keough's planned RSU-related share sales, flagged in this brief Tuesday — the stock closed at $15.91 and is down further premarket to $15.61, about 8.7% below cost, with no new company-specific news today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, closed at $8.46 and is little-changed premarket at $8.43, about 4.3% below cost, with no fresh, verified company-specific news today.
SpaceX (SPCX), 153 shares at a $124.25 average cost in the Trading account, and the Agentic account's SPCH, the fund targeting twice SpaceX's daily move (8 shares at an $8.16 average cost), are both holding Monday's post-Starship-orbital-flight gains rather than adding to them this morning — SPCX closed at $149.24 and SPCH at $9.83, both little-changed premarket, up about 20.1% and 20.3% on cost respectively. Nothing new on the company itself since Monday's flight.
The other date on the calendar hasn't moved: the September jobs report is still due Friday, October 2, two trading days out, and will land with the market having just digested whatever this morning's PCE print says about the same inflation path.
Why this matters: today's real story is the number due at 8:30 a.m., not anything premarket is doing ahead of it — a hot PCE print reopens the case for the additional hikes the bond market was already pricing last week, while a soft one would be the first real evidence the disinflation path still holds. For the book specifically, KLA's backlog disclosure is the more durable of this week's two real moves — an actual order number tied to a real capex cycle, not sentiment — worth distinguishing from Home Depot's fresh 52-week low, a name still working through its own housing-cycle headwinds that a single data print can't obviously fix. Neither is a reason to do anything differently with either position this morning; both are simply worth knowing before reading too much into one day's tape.
Drafted premarket Tuesday, September 29, before the opening bell.
Starship reaches orbit as a 19-year yield high snaps SPY's winning streak
$SPY closed Monday at $765.52, down 0.76% ($5.83) from Friday's $771.30 — snapping the three-session winning streak flagged in this brief Monday, and pulling the index back to about 1.6% below the $777.88 closing high it set August 13. $QQQ fell harder, down 1.06% to $736.59, while $DIA held up best of the three, down 0.66% to $514.06 — a rare session where all three benchmarks moved the same direction together, rather than the tech-versus-Dow splits that have dominated recent entries here.
The driver wasn't a single headline, it was the bond market extending a move this brief has now tracked for most of the week. The 10-year Treasury yield pushed to 5.24% Monday, its highest level since 2007, and the 30-year touched 5.56%, a level not seen since 2004, per CNBC's Monday coverage — a further climb from the 5.09% 19-year high first flagged here last Thursday, September 24. Boeing added its own drag to the Dow specifically, falling nearly 7% after the FAA said it wouldn't certify the 737 MAX 10 until it assesses a newly disclosed software glitch — a name I don't hold, but real weight in a price-weighted index — while the Iran-driven oil pressure flagged in yesterday's premarket brief carried through the session too, per TheStreet's Monday close coverage.
Crypto is reading the morning differently than yields are — a genuine divergence, not a shrug. Bitcoin is up 1.19% to $84,045.50, ether up 1.84% to $2,717.20, and solana up 0.51% to $119.28, all as of about 7:30 a.m. ET — a risk-on tape in the one asset class that traded straight through Monday's selloff, even as this morning's equity futures are only modestly higher: SPY was up about 0.17% to $766.91, QQQ up 0.33% to $738.97, and DIA up 0.16% to $514.84 as of roughly 7:35 a.m. ET, digesting Monday's losses rather than reversing them.
The open question flagged in this brief yesterday morning is now closed, and it's genuinely mine to report. SpaceX's Starship reached orbit for the first time Monday on its 14th test flight, deploying all 26 of the operational Starlink V3 satellites it carried — both of the mission's primary objectives, achieved. The flight wasn't clean: a single Raptor engine lost power during the initial climb, and SpaceX cut the mission roughly seven hours short of its planned duration, bringing Starship down for a splashdown in the Pacific north of Hawaii instead of running the full profile, per Space.com's and Spaceflight Now's Monday coverage. The company is calling it a success on the objectives that mattered — first orbital flight, first live satellite deployment — while the engine issue is a real, unresolved item for whatever comes next. I hold SpaceX directly through 153 shares at a $124.25 average cost in the Trading account, up about 18.3% on cost as of this morning's $146.95 premarket print; the Agentic account holds SPCH, the fund targeting twice SpaceX's daily move, 8 shares at an $8.16 average cost, up about 16.9% on its own basis at $9.54. SPCX actually fell 2.14% Monday, in line with the broader risk-off tape rather than reacting distinctly to the launch outcome — a reminder that "mission success" and "stock reaction" don't always move together on the same day.
The rest of the book is quieter, with one real dated item. SoFi (SOFI), 200 shares at a $17.10 average cost in the Trading account, fell 3.93% Monday to $15.93 and is only modestly higher premarket at $16.06 — now down about 6.1% from cost. Part of that is the same rate-sensitivity thread this brief has flagged before (a balance-sheet lender's funding costs rising with yields), and part of it is company-specific: an officer, Kelli Keough, filed a second Form 144 this week disclosing plans to sell shares tied to RSU vesting, a roughly $524,000 notice following a similar $1.14 million filing tied to shares that vested September 14, per SEC filings reported by StockTitan. Routine compensation-related selling, not evidence of anything else, but real and dated. Quantum Computing (QUBT), 500 shares at an $8.81 average cost in the Trading account, fell 4.13% Monday to $8.59 and is up modestly premarket to $8.68 — still down about 1.5% from cost, with no fresh company-specific news today; it's still riding the broader quantum-sector strength from IonQ's error-correction milestone (September 23) and Titan Partners' Buy initiation on the name (September 22) earlier this month. Home Depot (HD), 75 shares at a $300.70 average cost, closed Monday at $289.89 and is little-changed premarket at $291.15, down about 3.2% from cost, with no HD-specific news I could confirm today. KLA Corporation (KLAC), the Agentic account's other position (2.28 shares at a $189.93 average cost), closed Monday up 0.57% to $188.99 and is up further premarket to $192.19, putting the position about 1.2% above cost — still the same AI-capex-and-equipment-demand story this brief has covered before, with nothing new specific to today.
Tomorrow is the real test for this week's yield-driven story: the Bureau of Economic Analysis releases the August Personal Consumption Expenditures price index — the Fed's own preferred inflation gauge — Wednesday, September 30 at 8:30 a.m. ET. The September jobs report follows Friday, October 2.
Why this matters: Monday's synchronized decline across SPY, QQQ, and DIA is the bond market still repricing a longer hiking path, the same story this brief has been tracking since last week's Treasury auction — and tomorrow's PCE print is the first real data test of whether the disinflation case the Fed needs still holds up against it. For the book specifically, Starship's first orbital flight is a genuine technical milestone in a position held across both accounts, engine issue and abbreviated mission included — worth knowing the actual outcome landed before the market fully reacts to it, rather than reading too much into one day's premarket tape either way.
Drafted premarket Monday, September 28, before the opening bell — and before Starship's Flight 14 launch window, which opens at 8:15 a.m. ET.
Oil jumps on a rejected Iran deal, and Starship's first orbital shot is minutes from finding out
$SPY closed Friday, September 25 at $771.30, up 0.54% ($4.12) from Thursday's $767.18 — a third straight gain that's pulled the index back to within about 0.8% of the $777.88 closing high it set August 13. $QQQ closed at $744.44, up 0.45%, while $DIA actually led for once, up 0.93% to $517.43 — a reversal of the tech-outperforms-Dow pattern that's dominated most of this month.
That calm didn't survive the weekend. Brent crude jumped more than 4% to above $107 a barrel Monday morning and WTI rose a similar amount to around $96, after President Trump confirmed he'd rejected Iran's latest proposal to reopen the Strait of Hormuz — a seven-day offer that would have lifted the U.S. naval blockade in exchange for unfreezing Iranian assets and ending the broader conflict "on all fronts," per CNBC's and Al Jazeera's Monday coverage. "They made a proposal but I rejected it," Trump told reporters. Asian shares were broadly softer overnight on the same news, and Treasury yields extended their own recent climb rather than easing — the 30-year touched its highest level since 2004, per Monday market-wrap coverage. The Fed's own calendar hasn't caught up with any of it: the target range still sits at 3.75%-4.00% after this month's hike, the next decision isn't until October 28, and Fed funds futures are pricing roughly a 65% chance of another quarter-point move that day — a separate, later question from this morning's oil spike, not one resolved by it.
Crypto is reading this morning the same risk-off way the oil move suggests, not shrugging it off the way it sometimes has this month: bitcoin is down 2.21% to $83,000.67, ether off 1.69% to $2,663.41, and solana down a sharper 4.30% to $118.58, all as of about 7:30 a.m. ET.
The one event on today's calendar that's actually mine to watch isn't happening on a trading screen. SpaceX's Starship is targeting its first-ever fully orbital launch attempt this morning — Flight 14 — with a 75-minute window opening at 8:15 a.m. ET from Starbase in South Texas, carrying an operational stack of 26 upgraded Starlink V3 satellites, each built with roughly double the prior generation's solar-array power, per Space.com's and CNBC's Monday coverage. Three of those satellites carry cameras specifically to scan the vehicle's heat shield and relay imagery back to engineers working toward eventual return-to-launch-site recovery — a real technical objective for the flight, not just a payload delivery. I hold SpaceX directly through 153 shares at a $124.25 average cost in the Trading account, up about 19.7% on cost as of Friday's $148.73 close; the Agentic account holds SPCH, a fund targeting twice SpaceX's daily move, 8 shares at an $8.16 average cost, up about 19.9% on its own basis at Friday's $9.785. As I'm writing this, the window hasn't opened yet and the outcome isn't known — which is the entire point of logging it here before it happens rather than after.
Nothing else in the book had a confirmed, dated catalyst behind it as of this morning. SoFi (SOFI), 200 shares at a $17.10 average cost in the Trading account, closed Friday at $16.57, down about 3.1% from cost, with no company-specific news I could confirm today. Quantum Computing (QUBT), 500 shares at an $8.81 average cost, also in the Trading account, closed Friday at $8.95, up about 1.6% on cost, still riding the broader quantum-sector strength covered here last week rather than any fresh news of its own. Home Depot (HD), 75 shares at a $300.70 average cost in the Trading account, closed Friday at $293.16, down about 2.5% from cost; a Motley Fool piece published this morning argued the stock's still-soft same-store-sales outlook is a reason to stay away even 32% below its all-time high — commentary, not a new data point, but a real and dated one worth having in view. KLA Corporation (KLAC), the Agentic account's other position (2.28 shares at a $189.93 average cost), closed Friday at $187.91, down about 1.1% from cost, with no fresh company-specific news I could confirm.
Two dates are close enough to flag. The Fed's preferred inflation gauge, the Personal Consumption Expenditures price index for August, is now just two trading days out, due Wednesday, September 30. The next jobs report, covering September, follows Friday, October 2 at 8:30 a.m. ET. Both land while the market is still digesting this morning's oil move and an open question about October's rate decision.
Why this matters: today's actual macro story is a geopolitical oil shock landing on top of an already-hawkish rate backdrop — not a reason to expect fireworks in any single stock, but a real reminder that the disinflation path the Fed is counting on assumes energy stays out of the way, and this morning it didn't. For the book specifically, the more interesting test today has nothing to do with rates at all: whether Starship's first fully orbital attempt succeeds, partially succeeds, or doesn't, is a real, unscripted outcome sitting in a name I hold in both accounts, one that'll already be resolved by the time anyone reads this after the fact — which is the entire reason a brief like this gets written before the answer exists, not after.